



Ear Wash Station Market: Beyond the 4.65% CAGR Story—Key Shifts Explained

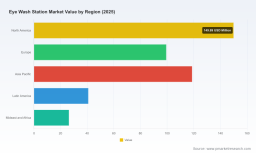
The Eye Wash Station Market: Strategic Trends and Commercial Opportunities Through 2032
The global market for emergency eye wash stations has entered a phase of measured, steady expansion. From 2020 through 2025, total market revenue climbed from approximately USD 300.0 million to USD 435.0 million, reflecting a compound trajectory that underscores the essential nature of workplace safety infrastructure. Looking ahead to the 2026–2032 forecast horizon, the market is projected to grow at a CAGR of 4.65 percent, reaching an estimated USD 596.0 million by 2032. This growth profile is not explosive, but it is structurally resilient. Emergency first-aid equipment sits at the intersection of regulatory compliance, industrial activity levels, and organizational risk management priorities. As long as those foundational drivers remain intact, the market maintains a predictable revenue floor alongside pockets of incremental upside.
Behind the headline numbers, however, lie structural shifts that demand attention from manufacturers, distributors, procurement leaders, and investors. The market is no longer moving purely on compliance-driven replacement cycles. It is being reshaped by evolving technical expectations, tightening performance standards, supply chain recalibration, and shifting application profiles across high-exposure industries. Understanding these dynamics is essential for anyone positioning themselves in the safety equipment space.
Current Market Landscape and Critical Challenges
The eye wash station market operates as a mature but still evolving segment within the broader workplace safety equipment ecosystem. Revenue growth over the past half-decade has been supported by steady industrial output, ongoing laboratory expansion, and consistent investment in occupational health infrastructure. Rather than experiencing abrupt cyclical swings, the market reflects the incremental nature of compliance upgrades, facility build-outs, and periodic modernization programs. The forecast period through 2032 suggests continued expansion, but at a pace that rewards companies with disciplined product planning, strong service networks, and clear differentiation rather than those relying solely on volume-driven commoditization.
Three core challenges and inflection points are shaping how participants navigate the market today.
Compliance complexity and specification drift. Emergency eyewash requirements are not static checklists. Regulatory frameworks and recognized standards continue to refine expectations around water temperature, flow consistency, activation speed, and maintenance protocols. For manufacturers and specifiers alike, this creates a moving target: products must satisfy baseline compliance while also aligning with installation practices, testing routines, and user training expectations that vary by facility type, region, and internal safety policies. The challenge is not simply meeting a standard once; it is designing systems that remain compliant over their service life under real operating conditions.
Total cost of ownership versus upfront purchase price. Many procurement decisions still default to initial cost, even though the operational footprint of an eyewash station can be substantial. Plumbed systems involve plumbing integration, water quality management, and ongoing testing programs. Self-contained units reduce infrastructure dependence but require cartridge or solution replacement, inventory management, and scheduled service. Combination units and higher-performance configurations add complexity and cost. Organizations increasingly need to evaluate installed cost, maintenance burden, downtime risk, and compliance documentation rather than treating eyewash stations as discrete commodity purchases.
Uneven adoption across facility types and geographies. While large industrial operators and accredited laboratories tend to have mature safety programs, smaller facilities, newer industrial zones, and certain emerging market environments may lag in standardization. This creates a bifurcated market where some segments demand advanced features and frequent replacement cycles, while others remain price-sensitive or delay investment until regulatory inspection or incident-driven reassessment forces action. Participants must therefore balance portfolio scope: offering accessible entry-level solutions while preserving higher-margin options for performance-conscious buyers.
These challenges also represent the market's pressure points for innovation. Companies that reduce compliance uncertainty, simplify maintenance, or make total cost easier to quantify are better positioned to capture specification wins and retain end users over time.
Key Drivers Shaping the Market
The market's trajectory is being pulled by several interconnected forces. Individually, each matters; together, they define where growth is likely to concentrate and where competitive advantage will be earned.
Eye Anatomical Model Market
Technical innovation and performance differentiation
One of the most significant drivers is the ongoing push toward better flushing performance, faster activation, and more predictable user experience. Innovative rinsing technologies, improved flow distribution, and ergonomic actuation mechanisms are becoming meaningful differentiators, especially in environments where seconds matter and the margin for error is small. Products designed to deliver consistent dual-eye coverage, tepid water delivery, and intuitive activation address both compliance goals and practical usability concerns. In laboratory and healthcare-adjacent settings, compact footprints, easy integration with existing wall or bench configurations, and reduced risk of cross-contamination during use are also shaping purchasing preferences.
For manufacturers, the strategic implication is clear: technical features are increasingly tied to specification decisions. Product leadership now extends beyond build quality into performance reliability, ease of testing, and the ability to document compliance over time. This elevates the importance of engineering discipline, validation data, and post-sale support in competitive positioning.
Regulatory expectations and standards enforcement
Regulatory frameworks continue to anchor demand for emergency eyewash infrastructure. Occupational safety requirements mandate suitable facilities for immediate flushing where eyes or body may be exposed to harmful corrosive materials. In practice, this creates a baseline obligation for employers operating in at-risk environments and pushes safety equipment from optional courtesy infrastructure into essential compliance assets.
At the same time, recognized performance and installation guidance continues to sharpen expectations around continuous flow, tepid water delivery, minimum flush duration, and simultaneous eye coverage. Manufacturers and facility managers must therefore consider not only whether a unit exists, but whether it performs correctly under required conditions and can be maintained accordingly. This dynamic reinforces demand for compliant products and services, while also raising the stakes for installation, testing, and recordkeeping practices. In effect, regulation is not only stimulating purchase volume; it is also increasing the cost of non-compliance and rewarding organizations that treat eyewash readiness as an integrated program rather than a point purchase.
Demand-side behavior and organizational risk culture
Buyer behavior is shifting from reactive compliance toward proactive risk management. In chemical-intensive industries, pharmaceutical operations, electronics manufacturing, and oil and gas facilities, the consequences of inadequate first-aid readiness are visible and potentially severe. As a result, safety equipment is increasingly evaluated through the lens of incident mitigation, employee protection, and operational continuity rather than solely regulatory checking.
This cultural shift influences purchasing in several ways. Facilities are more likely to standardize across sites, prefer combination units in high-risk zones, and invest in products that simplify inspection and maintenance workflows. Laboratory environments, in particular, often prioritize immediate accessibility and space-efficient designs that support rapid deployment without disrupting sensitive workflows. In parallel, growing awareness of worker welfare and safety branding can make higher-specification units more attractive, especially where organizations are trying to signal a strong safety culture to staff, auditors, or partners.
Supply chain structure and regional manufacturing dynamics
Cost structure and supply resilience are becoming more prominent in purchasing and product strategy. Manufacturers must navigate raw material pricing, component availability, shipping volatility, and the operational requirements of maintaining consistent quality across different production locations. At the same time, regional sourcing options are shaping buyer considerations around lead times, customization, and support responsiveness.
This environment favors companies that can balance scale with flexibility. For some buyers, domestically produced or well-supported regional products offer perceived advantages in documentation, service proximity, and specification familiarity. For others, competitive pricing and broader portfolio availability from international manufacturers create attractive alternatives, especially in price-sensitive segments or fast-growing industrial markets. The result is a more varied competitive field in which differentiation often comes from a combination of product reliability, service access, and the credibility of compliance support rather than price alone.
Competitive Landscape and Leading Strategies
The market features a diverse set of participants spanning established manufacturers, safety-focused brands, laboratory specialists, distributors, and international producers. This diversity reflects the broad application base of emergency eyewash equipment and the different ways customers evaluate solutions. The presence of multiple competent suppliers also means that competitive advantage depends heavily on execution: product design, compliance alignment, service coverage, and go-to-market clarity.
Parts Washer Market
Strategic positioning among leading participants
Several companies illustrate the range of successful strategic approaches in the market.
Haws Corporation has built a strong identity around flushing performance and application-specific engineering. Its emphasis on advanced rinsing technology for industrial, laboratory, and healthcare settings positions it as a solution provider for buyers who prioritize performance consistency and specialized use cases. This approach helps the company compete on specification quality rather than solely on price, particularly in environments where superior flushing performance is directly tied to safety outcomes.
Guardian Equipment Company is widely recognized for emergency eyewash and shower equipment that covers wall-mounted, pedestal-mounted, and combination configurations. Its alignment with ANSI/ISEA Z358.1 and OSHA expectations gives buyers a straightforward compliance narrative, which is valuable in procurement environments where standardization and audit readiness matter. The breadth of mounting options and unit types also supports flexibility across facility layouts and risk zones.
Bradley Corporation focuses on industrial emergency eyewash stations, safety showers, and combination units with customizable features for high-risk chemical exposure areas. This positions the company well in environments where exposure risk is significant and where specifiers want solutions that can be adapted to specific operational conditions. Customization capability can be a decisive factor when standard off-the-shelf configurations do not fully match site requirements or when facilities seek to consolidate safety equipment specs across complex installations.
Speakman Company offers plumbed and portable eyewash stations along with replacement parts and safety showers. This combination of product supply and parts availability supports longer-term customer relationships by addressing the maintenance and replacement cycle. For many end users, ongoing service access and parts availability are as important as the initial purchase, especially when compliance testing and operational readiness must be sustained over time.
Haws Safety Products under Honeywell brings the recognizable Fendall® brand into industrial and laboratory settings with eye wash stations and cartridges designed for immediate flushing. The brand and cartridge-based approach can resonate with buyers looking for predictable performance, simplified resupply, and familiarity across multiple sites. In laboratory contexts especially, compact cartridge-based solutions may offer a practical balance between readiness and infrastructure demands.
Hughes Safety Company designs ANSI-compliant eyewash stations, self-contained units, and emergency showers for global industrial and workplace use. Its international orientation and compliance-focused portfolio make it relevant for organizations operating across multiple jurisdictions or seeking a consistent safety equipment standard across global facilities. For multi-site enterprises, that consistency can reduce specification fragmentation and simplify training and maintenance programs.
LOC Scientific targets laboratory eye wash station units designed for immediate emergency rinsing and compliance in research and industrial labs. By concentrating on laboratory-specific needs, it addresses a segment where accessibility, space constraints, and rapid response expectations are particularly acute. Niche focus can be a strong competitive lever when the end user environment has distinct operational requirements and when general-purpose products do not fit as cleanly.
Unicare stands out as a pioneer manufacturer based in India, producing eye/face wash stations and safety showers with in-house engineering for industrial and laboratory applications. This reflects the growing relevance of regional manufacturing capability and self-contained engineering resources. For buyers in emerging industrial markets or those seeking localized supply and support, such providers can offer attractive combinations of price, responsiveness, and application understanding.
EyewashDirect.com operates as a distributor and provider of eyewash stations, safety showers, and repair parts from leading manufacturers. Its role highlights the continued importance of distribution channels in this market. Many buyers prefer consolidated sourcing, technical guidance, and access to multiple brands when specifying safety equipment. Distributors that can combine product breadth with compliance-oriented support often serve as important intermediaries between manufacturers and end users.
Sysbel Manufacturing, based in China, supplies laboratory and industrial eye wash systems, including emergency eyewash solutions for chemical splash protection. Its presence underscores the growing influence of international manufacturers in both laboratory and industrial segments, particularly where cost competitiveness, export capability, and expanding portfolio range align with buyer needs.
How the competitive structure is evolving
The market is neither highly concentrated nor fragile. The competitive share distribution suggests room for multiple winners, with leadership determined by product relevance, service quality, and specification influence rather than by scale alone. Over time, three evolutionary patterns are likely to persist.
Consolidation through capability, not just acquisition. Some tightening may occur as larger platforms strengthen their safety portfolios or as distributors integrate broader product lines. However, meaningful consolidation will likely be driven by the desire to offer more complete compliance, service, and specification support rather than by eliminating competition purely for market share.
Segmentation by application and performance tier. As buyers become more sophisticated, the market will continue to differentiate between baseline compliance units and higher-performance or specialized solutions. Manufacturers that can clearly articulate why a given design is better suited to a specific environment—chemical processing areas, laboratory benches, outdoor sites, or multi-hazard work zones—will have stronger positioning.
Entry and expansion from regional and international suppliers. New and expanding suppliers can gain traction by offering competitive alternatives in specific geographies or application niches. This creates both opportunity and pressure for incumbents to defend specification relationships, demonstrate reliable performance, and maintain strong service networks.
Future Trends and What They Mean for Opportunities
Over the next three to five years, the eye wash station market is likely to be shaped by trends that blend compliance, technology, and operational practicality. These trends are not speculative shifts; they are extensions of current pressures and buyer priorities.
Trend 1: Compliance-as-program instead of compliance-as-equipment
Emergency eyewash readiness will increasingly be treated as an ongoing operational program rather than a one-time installation decision. That means greater emphasis on testing routines, documentation, activation reliability, solution or cartridge management, and user training. For suppliers, this opens opportunities in service, replacement parts, inspection support, and products designed to make compliance easier to sustain. For buyers, it argues for selecting equipment and partners that reduce administrative and maintenance friction over the asset lifecycle.
Trend 2: Performance features become default purchasing criteria
As the market matures, features that improve flushing effectiveness, speed of access, temperature control, and ease of use are likely to move from differentiators to expected attributes in many segments. This will reward manufacturers with clear engineering advantages and penalize those competing only on price in specification-driven environments. The commercial opportunity lies in translating technical performance into practical outcome language that resonates with safety managers, facility engineers, and procurement teams.
Trend 3: Broader application diversification and regional growth paths
Demand will continue to spread across chemical, pharmaceutical, electronics, oil and gas, and other industrial or laboratory environments, but the pace and mix will vary. In some regions, expanding industrial activity and laboratory build-outs will support stronger volume growth. In others, replacement cycles and compliance upgrades will be the main driver. This unevenness creates targeted opportunities: companies that align product portfolios with high-exposure segments and regional demand patterns can capture disproportionate relevance in the markets that matter most to them.
PW Consulting
Potential risks and uncertainties
Several uncertainties deserve attention. Regulatory expectations or interpretation can shift, affecting specification requirements and maintenance burdens. Economic cycles may pressure capital spending, particularly among smaller operators or in segments where safety equipment competes with more immediate operational priorities. Supply chain disruptions or input cost volatility can affect margins and delivery reliability. In addition, if buyers over-emphasize lowest initial cost, the market may experience pressure on quality differentiation and service investment. Companies that depend on a narrow product range or on a single geography may also face greater exposure if demand patterns shift unexpectedly.
Strategic Actions for Decision Makers
Different participants should approach the market with different priorities, but several actionable themes apply across roles.
For manufacturers and product developers, clarity of application focus is essential. Rather than competing broadly on volume alone, define where your design advantages actually matter—whether that is flushing performance, laboratory compactness, combination-unit flexibility, cartridge-based resupply, or serviceability. Invest in the documentation, validation, and support materials that help specifiers justify selection during procurement reviews. In parallel, treat maintenance and parts availability as part of the product story, because long-term compliance depends on them.
For investors and strategic planners, the market offers steadier demand characteristics than many discretionary industrial categories, but the best opportunities are likely to come from companies with defensible positioning in specification-driven segments. Look for participants that can demonstrate consistent compliance alignment, meaningful product distinction, and reliable routes to end users through distribution, service, or direct enterprise relationships. Capital allocation should favor structures that can withstand pricing pressure while still investing in performance and support.
For procurement teams and facility operators, the strongest buying decisions will come from evaluating total ownership impact rather than unit price alone. That includes installation requirements, testing burden, water quality considerations, cartridge or solution replacement logistics, replacement part availability, and the consistency of the solution across multiple sites. Where possible, standardize specifications to reduce training and maintenance complexity, and ensure that selected units genuinely match the exposure profile of each zone rather than defaulting to a single model across all areas.
Across all of these roles, timely and detailed market intelligence matters because the eye wash station market is not driven by a single force. It is shaped by overlapping regulation, technical expectations, application needs, and regional dynamics. Decisions made without a clear view of those layers can lead to over-investment in the wrong product tier, missed specification opportunities, or insufficient attention to service and compliance sustainability. The broader market trajectory is constructive, but the real value lies in understanding where growth is concentrated, which product attributes are becoming non-negotiable, and how competitive advantage is being earned on the ground.
Conclusion
The eye wash station market is expanding along a stable, compliance-anchored path, with growth reinforced by industrial activity, laboratory demand, and the continued institutionalization of workplace safety programs. Yet the most important developments are not simply the headline revenue figures. They are the shifts in how products are specified, maintained, and justified; the increasing importance of performance and usability; and the growing influence of service, distribution, and regional manufacturing in shaping buyer choices. Participants that treat eyewash readiness as a long-term operational commitment—and build products, bundles, and relationships accordingly—are best positioned to benefit from the market's next phase of growth.
For detailed analysis of this topic, please visit the official page: Eye Wash Station Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


