



Logistics Robots Market 2032: Why 16.8% CAGR and 63% Palletizing Shift Redefine Growth

The Logistics Robots Market: Navigating Growth, Innovation, and Strategic Opportunity
The logistics robots market has evolved from a niche automation segment into a foundational pillar of modern supply chain infrastructure. Between 2020 and 2025, the market expanded from approximately $66.8 million to $120.5 million, reflecting a compound annual growth rate of 16.8% that extends through the 2026–2032 forecast window. By the end of the projection period, revenue is expected to approach $295 million, driven by sustained adoption across warehousing, material handling, and last-mile operations. This trajectory is not merely a function of technological novelty; it represents a structural realignment in how goods are moved, sorted, and stored amid persistent labor constraints, rising throughput expectations, and the need for operational resilience.
Within this growth story, concentration patterns reveal a market still in transition. The top three players capture roughly 45% of revenue, while the top five account for 56%, indicating a landscape where established automation vendors coexist with agile, software-driven entrants. The diversity of offerings—from automated guided vehicles and autonomous mobile robots to robotic arms and specialized end-effectors—demonstrates that logistics automation is no longer a one-size-fits-all proposition. Instead, success increasingly depends on how well solutions integrate with existing facility layouts, warehouse management systems, and broader enterprise data architectures.
Market Landscape and Critical Inflection Points
From Isolated Automation to Ecosystem Integration
For much of the past decade, logistics robotics deployments focused on discrete, repeatable tasks within controlled environments. Today, the prevailing shift is toward layered automation ecosystems where mobile platforms, fixed automation, and software orchestration converge. Facilities are no longer evaluating robots as standalone tools; they are assessing how robotic fleets interact with inventory algorithms, demand forecasting models, and labor scheduling systems. This integration imperative is reshaping procurement cycles, implementation timelines, and the value proposition of vendors who can deliver both hardware reliability and intelligent software layers.
Labor Dynamics and Throughput Pressure
Persistent workforce volatility continues to act as a fundamental catalyst. High turnover, shifting labor availability, and escalating training costs have pushed operators to seek automation that augments rather than entirely replaces human activity. At the same time, consumer expectations for faster, more accurate fulfillment have compressed tolerance for bottlenecks. The result is a market where throughput per square foot, error reduction, and flexibility during demand spikes have become central decision criteria. Companies are increasingly treating robotics not as a capital expenditure isolated from operations, but as a lever for stabilizing service levels under variable conditions.
Worldwide Logistics Automatic Robotics Machine Market
Cost Structures and Implementation Complexity
While the promise of automation is clear, the economics of deployment remain uneven. Upfront capital, integration effort, and change management requirements can delay payback periods, particularly for mid-sized operators. Steel tariffs of 25% implemented in 2025 have added pressure to equipment costs across robotics and conveyor systems, with domestic steel price increases partially neutralizing the expected advantages of localized sourcing. These dynamics are pushing buyers to evaluate total cost of ownership more rigorously, favoring solutions that minimize retrofit complexity, support phased rollouts, and offer predictable operating expenses.
Core Drivers Shaping Market Trajectory
Technological Innovation and Embodied Intelligence
The most consequential driver is the maturation of embodied intelligence and AI-enabled navigation. Modern autonomous mobile robots are increasingly capable of dynamic path planning, obstacle recognition, and task adaptation without extensive fixed infrastructure. Recent product introductions illustrate this direction: in May 2026, SEER Robotics launched an AI delivery robot ready for immediate deployment alongside an embodied wheeled humanoid robot base, signaling a push toward versatile platforms that can handle both final-mile delivery and warehouse operations. Similarly, Geek+ introduced its Brain embodied intelligence platform and RoboShuttle V5 at MODEX 2026, reinforcing the industry’s move toward software-defined robotics that can be reconfigured as operational needs change.
These advancements reduce the traditional friction of warehouse automation: fixed guide paths, extensive site preparation, and rigid workflow assumptions. Instead, fleets can be scaled incrementally, retasked across shifts, and coordinated through centralized orchestration layers. For operators, this means automation can follow demand rather than requiring demand to conform to automation design. For vendors, differentiation is shifting from mechanical performance alone to the quality of perception, fleet coordination, and integration APIs.
Policy, Safety Standards, and Regulatory Clarity
Regulatory and standards development is quietly reshaping deployment confidence. The ANSI/A3 R15.06-2025 safety standard, which updates ISO 10218-1:2025, introduces revised risk assessment practices, functional safety expectations, and cybersecurity requirements for industrial robots. As safety frameworks become more explicit, organizations gain clearer guidance for integrating collaborative and autonomous systems alongside workers, reducing ambiguity that historically slowed adoption in mixed human-robot environments.
Policy momentum is also emerging in specific geographies. In the United Kingdom, the 2025 Industrial Strategy and Digital and Technologies Sector Plan introduced reforms including a Regulatory Innovation Office and a clearer route to market for delivery robots. Such developments matter because they reduce time-to-deployment uncertainty for last-mile and urban logistics applications. When regulators provide predictable pathways, innovators can invest with greater confidence, and operators can plan pilots with more reliable approval timelines.
Demand-Side Shifts and the Rise of Robotics-as-a-Service
On the demand side, adoption patterns are broadening beyond large-scale distribution centers. As of November 2025, 60% of U.S. warehouses had integrated AI into their operations, with projections indicating this figure could reach 80% in the coming years. This AI penetration is closely intertwined with robotics adoption because intelligent software layers make robotic fleets more useful: they enable better task allocation, predictive maintenance, and dynamic responsiveness to order profiles.
The economics of adoption are also evolving through Robotics-as-a-Service models, which grew by 42% according to IFR World Robotics 2025 data. IFR reported 102,900 transportation and logistics robots sold in 2024, making this the largest professional service robot application class. RaaS growth reflects a preference among many operators for variable-cost models that lower upfront capital exposure and align automation expenses with utilization. For a market where operational flexibility is paramount, subscription and outcome-based pricing are becoming meaningful differentiators, particularly for seasonal businesses and companies managing multiple sites with varied automation needs.
Supply Chain Realities and Cost Resilience
Supply chain volatility continues to influence purchasing behavior and vendor selection. Beyond steel tariffs, organizations are weighing the resilience of their automation supply chains: component availability, lead times, and service support networks all affect the reliability of robotic deployments. Vendors that provide transparent supply chain strategies, modular hardware designs, and robust remote support capabilities are gaining favor because they reduce the risk of prolonged downtime. In parallel, the push toward software-defined fleets is making it easier to adapt hardware bases to new tasks via firmware and orchestration updates, which helps protect prior investments as operational requirements change.
Competitive Dynamics and Strategic Positioning
Portfolio Breadth Versus Specialized Excellence
The competitive field spans global automation incumbents, AMR specialists, and emerging players focused on embodied intelligence, humanoid platforms, and cloud robotics. Companies such as Amazon Robotics, ABB, KUKA, Toyota Industries, Fanuc, Yaskawa, KION Group, Daifuku, and MiR bring scale, industrial manufacturing heritage, and deep integration experience. Their competitive strength often lies in the ability to combine robotics with broader material handling systems, service networks, and long-standing customer relationships.
At the same time, specialist firms are carving distinct positions. Geek+ has maintained a leading position in AMR and embodied intelligence warehouse logistics, emphasizing full fleet solutions for order fulfillment and storage. Locus Robotics focuses on AI-powered autonomous mobile robots and robots-to-goods picking systems that align closely with labor-constrained picking workflows. Rapyuta Robotics promotes cloud robotics with ASRS and upgraded PA-AMR systems designed for modular warehouse automation, appealing to operators seeking flexibility across site configurations. Addverb Technologies has expanded its footprint with carousel automation and interface robots tailored for high-order storage centers, while Exotec has pushed higher-density storage through next-generation Skypod systems with advanced software and improved space utilization.
Differentiation Through Software, Safety, and Service
Hardware motion is increasingly table stakes; competitive advantage is accruing to firms that excel in fleet orchestration, safety certification, and service economics. The emphasis on updated safety standards and cybersecurity requirements elevates the importance of vendors who can document compliance rigorously and support secure integration with enterprise IT. Service models are equally critical: remote diagnostics, over-the-air updates, and predictable maintenance windows reduce the operational burden on warehouse teams and strengthen the business case for automation. In markets where labor is scarce and skilled technicians are even scarcer, service reliability can be as decisive as robot speed or payload.
Market Evolution: Consolidation, Fragmentation, and New Entrants
The market is unlikely to settle into a single dominant structure. Instead, it is evolving along multiple axes. Large automation groups may consolidate capabilities through acquisitions that add software, vision, or mobile capabilities to fixed automation portfolios. Simultaneously, fragmentation persists at the application layer, where niche players address specific workflows such as tote handling, final-mile delivery, or high-density storage. New entrants are also emerging with humanoid and embodied platforms, expanding the design space beyond traditional pallet and cart movement. This pluralistic structure benefits buyers because it creates options across price points, deployment styles, and integration complexity, but it also complicates vendor selection and underscores the need for clear evaluation criteria aligned with operational goals.
Forward Outlook: Three Trends Defining the Next Wave
Trend 1: Software-Defined Fleets Become the Norm
Over the next three to five years, the market will increasingly separate the value of hardware from the value of orchestration. Robots will be expected to adapt to changing layouts, task mixes, and throughput targets through software upgrades rather than physical reconfiguration. This trend favors platforms with open integration architectures, robust simulation tools, and analytics that help operators optimize task assignment and utilization. The commercial opportunity lies in solutions that can demonstrate measurable improvements in pick density, travel efficiency, and changeover time without requiring major facility redesign.
Trend 2: Broader Application Footprints Beyond Traditional Warehousing
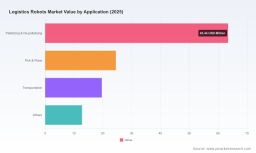
While palletizing, de-palletizing, pick-and-place, and internal transportation remain dominant use cases, the application frontier is expanding. Final-mile deliveries, mixed human-robot collaboration in active aisles, and modular automation for smaller sites are gaining traction. In the United Kingdom, regulatory reforms have opened clearer routes for delivery robots, and product launches in embodied wheeled platforms point toward more versatile machines capable of operating across warehouse and urban environments. As these applications mature, the market will likely see more cross-site deployments where the same platform family supports multiple functions, improving asset utilization and simplifying fleet management.
Trend 3: Cost Optimization and Phased Adoption Models
Given equipment cost pressures and integration complexity, adoption will continue to shift toward phased rollouts and flexible financial models. Operators will favor deployments that prove value in a limited area before expanding, especially when steel tariffs and domestic material costs elevate baseline equipment expenses. Robotics-as-a-Service and outcome-linked pricing will remain attractive for organizations seeking to manage capital exposure and align automation spend with volume variability. Vendors that can offer transparent cost structures, scalable pilots, and rapid time-to-value will be better positioned to convert interest into committed deployments.
PW Consulting Automotive & Machinery Research Center
Risks and Uncertainties to Monitor
Several factors could temper or redirect growth. 만일 steel and component cost pressures persist, payback periods may lengthen for capital-intensive projects, slowing adoption among price-sensitive segments. Regulatory divergence across regions could create uneven deployment paths, particularly for mobile and delivery applications that cross jurisdictional boundaries. Cybersecurity expectations will continue to rise, requiring vendors and operators to invest in secure integration and data governance. Finally, the pace of AI adoption in warehouses will influence how quickly robotic fleets realize their full potential; without strong software integration and change management, advanced hardware can underperform relative to expectations.
Strategic Actions for Decision-Makers
For Manufacturers and Automation Vendors
Differentiate beyond kinematics. The most defensible positions will combine reliable mobile platforms with strong orchestration software, clear safety and cybersecurity documentation, and service models that reduce operational friction. Prioritize integration readiness with existing warehouse management and enterprise systems, and invest in simulation and deployment tooling that shortens implementation cycles. As application diversity increases, modular hardware and flexible tasking capabilities will help customers adapt without discarding prior investments.
For Investors
Look for value creation at the intersection of software, fleet management, and service economics. Companies that can demonstrate repeatable deployment processes, strong utilization metrics, and scalable RaaS or outcome-based models are better aligned with the market’s shift toward flexible cost structures. Pay attention to safety compliance maturity and cybersecurity posture, as these increasingly influence procurement decisions in mixed-use environments. Sector breadth matters too: exposure across warehousing, material handling, and final-mile applications can provide resilience if one segment slows.
For Procurement and Operations Leaders
Define the problem before selecting the platform. Clarify whether the priority is throughput stability, labor augmentation, space efficiency, or flexibility across sites, then evaluate vendors against those outcomes rather than nominal specifications. Favor phased pilots that can validate performance under real order profiles, and model total cost of ownership with realistic integration and service costs. As equipment cost pressures persist, consider flexible financial models and modular deployments that let you scale credible results rather than committing to large fixed installations upfront.
From Insight to Execution
The logistics robots market is moving from rapid expansion to more nuanced value creation. Growth rates remain strong, but the next phase will reward those who can align automation with operational realities: integration complexity, safety expectations, cost pressures, and the need for flexible deployment models. Companies that treat robotics as part of a broader, software-enabled logistics strategy will be better equipped to capture the upside while managing risk.
For decision-makers seeking detailed segmentation data, regional and application-level revenue breakdowns, competitor benchmarking, and customized strategic recommendations, the full PW Consulting research report provides the granular evidence base needed to translate these market dynamics into concrete investment and deployment decisions.
Worldwide Warehouse Robots Market
For detailed analysis of this topic, please visit the official page: Logistics Robots Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


