



Shot Blasting Machines Market: Why 6.32% CAGR and Automation Shift Commercial Dynamics

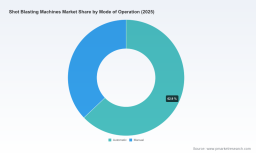
Shot Blasting Machines Market: Strategic Trends and Commercial Opportunities
The global shot blasting machines market is undergoing a structural transformation defined by automation, digital integration, and shifting end-use priorities. With a projected compound annual growth rate of 6.32 percent and an expanding revenue trajectory from approximately $1.5 billion in 2025 toward over $2.3 billion by 2032, the sector reflects sustained industrial demand for surface preparation, cleaning, and finishing solutions. Growth is not merely a function of volume; it is increasingly shaped by how manufacturers align equipment capabilities with stricter cleanliness standards, labor constraints, and operational efficiency targets. Understanding where momentum is building, and which forces are reshaping competitive positioning, is essential for executives evaluating capital deployment, product strategy, or procurement direction.
Market Landscape and Core Challenges
The market has moved through a period of steady expansion, recovering from earlier cyclical softness and reaccelerating as industrial throughput improved across multiple regions. Revenue figures have climbed consistently year over year, supported by replacement cycles, capacity additions in casting and forging, and broader investments in surface treatment infrastructure. This trajectory signals a market that is stabilizing around higher baseline demand, yet one that is also entering a more demanding operational environment where incremental efficiency gains matter as much as unit sales.
Several forces are creating friction and opportunity at the same time. First, the link between surface preparation quality and downstream performance is becoming more visible across metal-intensive industries. Cleanliness, profile consistency, and blast repeatability now carry direct implications for coating adhesion, corrosion resistance, and component life. That makes shot blasting less of a commodity service and more of a controlled process step, raising expectations for equipment precision and documentation.
PW Consulting
Second, labor availability and skill constraints are altering how plants use existing equipment. In several major markets, shortages of experienced metalworking technicians are limiting utilization rates and increasing the cost of manual interventions. This dynamic is pushing organizations to favor machines that reduce operator dependency, simplify changeovers, and maintain output even with thinner skilled-labor pools.
Third, material and consumable volatility is forcing a sharper focus on total cost of ownership. Abrasive media usage, dust handling, and wear-part replacement directly affect operating economics. When media prices fluctuate and alternative materials compete for adoption, manufacturers are increasingly evaluating blast systems not only by purchase price but by consumption control, recovery efficiency, and integration with broader material management practices. These challenges are not purely restrictive; they are also helping separate operators who treat blast cleaning as a cost center from those who treat it as a process capability that can be optimized.
Key Drivers Reshaping the Market
Market momentum is being driven by a combination of technology maturation, regulatory pressure, demand-side behavior, and supply-side cost dynamics. These drivers are interacting, not operating in isolation.
Technology Innovation and Process Control
The most visible shift is the move from standalone mechanical systems toward connected blast platforms that provide visibility into media consumption, wheel wear, and process consistency. Intelligent monitoring and data-linked controls are making it easier to balance output quality with consumable usage. For operators, that means fewer unplanned interruptions, more predictable cleaning results, and stronger alignment between surface preparation and downstream workflow. The practical value is not just automation itself, but the ability to standardize results across shifts, batches, and product mixes.
Alongside connectivity, equipment design continues to evolve around throughput, ergonomics, and serviceability. Machines are being configured to handle a wider range of part geometries and throughput requirements while reducing manual handling. That is especially relevant where mixed production schedules or shorter runs demand flexible equipment rather than rigid high-volume lines. The market is increasingly rewarding systems that combine repeatability with practical adaptability.
Regulatory and Standards Pressure
Regulatory expectations around worker exposure, dust control, and surface cleanliness are strengthening the case for more controlled blast environments. Filtrations, containment, and protective features are becoming central to equipment selection rather than peripheral add-ons. In parallel, widely referenced surface cleanliness standards are pushing structural fabricators and metal processors toward more consistent automated preparation methods.
Cast Steel Shot & Grit Market
The commercial consequence is twofold. Equipment that can demonstrate reliable compliance and cleaner outputs gains a qualitative advantage in bid-sensitive environments. At the same time, buyers are less willing to treat blast capacity as interchangeable, since cleanliness and handling requirements increasingly influence qualification decisions. This is expanding the premium on engineered systems that integrate dust management, media recovery, and controlled blast intensity into a cohesive process.
Demand-Side Shifts in End-Use Industries
End-use demand is becoming more segmented and performance-driven. Automotive and aerospace remain influential, but the nature of demand is shifting toward consistent surface quality, tighter throughput expectations, and components that must meet demanding service environments. Foundries and metal processors continue to rely on shot blasting for casting cleaning and scaling removal, but they are also weighing equipment against broader line efficiency and inspection readiness. Construction, rail, shipbuilding, and other industrial applications contribute to demand in their own ways, particularly where heavy components, infrastructure materials, or repaired assets require dependable surface treatment.
A notable change is that buyers increasingly view blast equipment as part of a broader quality and throughput system. That means machine selection is more closely tied to downstream finishing, coating, inspection, and rework reduction. The implication is that performance claims grounded in process control, media efficiency, and repeatable outcomes are becoming more persuasive than broad equipment descriptions alone.
Supply Chain and Cost Structure Dynamics
Cost pressures are reshaping purchasing logic. Raw material swings, regional production differences, freight variability, and service-part availability all influence the delivered economics of shot blasting equipment. As a result, buyers are paying more attention to system-level operating costs, including media life, wheel wear, filtration load, and maintenance downtime. This is particularly important in environments where machines run frequently and downtime carries disproportionate production penalties.
Shot Peening Machine Market
At the same time, regional manufacturing footprints are becoming strategically relevant. Localized support, faster parts availability, and proximity to end markets can reduce operating risk. In several cases, expanding production capacity in or near high-growth regions is being used to improve service response and strengthen competitive positioning. This points to a market where hardware capability still matters, but responsiveness and execution may differentiate suppliers as much as product specifications.
Competitive Landscape and Leading Strategies
The competitive field is diversified, with global players, regional specialists, and application-focused manufacturers coexisting across different machine types, technologies, and service models. Market concentration remains moderate, indicating that share is distributed across a broad set of participants rather than resting with a small group of dominant incumbents. That structure leaves room for differentiation through technology, application expertise, regional presence, and aftermarket support.
Strategic Positioning of Leading Players
Several companies illustrate distinct strategic arcs within the market. International manufacturers with broad portfolios are emphasizing integrated solutions that span wheel blast and air blast systems, batch and continuous processes, and industrial surface preparation across multiple end markets. Their positioning tends to rely on a wide application base, global service networks, and established product ranges that can be adapted to varied customer requirements.
Other players have leaned toward engineering depth and digital-enabled process control. Smart platform capabilities, real-time wear monitoring, and integration with plant systems are being used to position equipment as a productivity and quality enabler rather than a standalone cleaning device. This strategy is particularly relevant for customers seeking consistent output and lower consumable waste in demanding production environments.
Regional and specialized manufacturers continue to play an important role by focusing on specific machine configurations, material types, or local support expectations. Their advantage often lies in responsiveness, customization, and close alignment with regional fabrication or foundry practices. For buyers prioritizing shorter lead times, local service, or application-specific tuning, these suppliers can be highly competitive.
Recent Moves Shaping the Landscape
Recent activity highlights where competition is intensifying. The rollout of IoT-linked blast platforms with analytics for abrasive media consumption and wheel wear points to a market that is moving toward data-informed operation. Demonstrations combining live performance testing, augmented reality, and optimization sessions indicate growing interest in practical efficiency gains rather than product novelty alone. Participation in international trade events and facility expansion in high-growth regions further suggests that manufacturers are investing in visibility, capacity, and localized support to capture demand more effectively.
Taken together, these developments suggest a competitive environment in which differentiation is increasingly built on three layers: core machine reliability, process intelligence, and service responsiveness. Companies that can align those layers with customer operating priorities are better positioned to capture share in a market where specifications alone are no longer a sufficient advantage.
Consolidation, Fragmentation, and New Entry
The market is not trending toward rapid monopoly-style consolidation. Instead, it appears to be evolving through selective consolidation at the service and technology levels while remaining broad at the product level. Larger players may pursue complementary capabilities, regional reach, or application coverage, but fragmentation persists because blast cleaning requirements vary widely by part type, material, throughput, and labor context. New entrants can still find opportunity by serving niche applications, offering lower-cost configurations, or focusing on fast regional support. However, long-term credibility tends to depend on consistent performance, parts availability, and the ability to demonstrate measurable savings in media usage, downtime, and rework.
Future Trends to Watch
Over the next three to five years, several trends are likely to define how the market evolves and where commercial value accumulates.
- Process intelligence becomes standard rather than exceptional. Connected monitoring, consumables analytics, and integration with plant systems will increasingly be expected in higher-value installations. The commercial opportunity lies in reducing total operating cost, improving consistency, and making blast performance easier to manage across shifts and product variations.
- Automation and labor-efficient designs gain preference. As skilled-worker constraints persist in several regions, equipment that reduces manual intervention, simplifies setup, and supports steady utilization will be favored. This trend creates opportunities for manufacturers who can prove that their machines maintain output with fewer dependent labor inputs.
- Compliance and cleanliness become stronger purchase criteria. Regulatory expectations and surface quality requirements will continue to push buyers toward equipment with better containment, filtration, and repeatable surface preparation. Suppliers that can tie equipment capabilities to documentation, consistency, and risk reduction will have an advantage in qualified and bid-sensitive environments.
These trends are not risk-free. Technology integration can raise upfront complexity and require training, data management, and support infrastructure that smaller users may find difficult to absorb. Material price volatility can still disrupt operating budgets, especially when alternative media options shift demand patterns. And if regional economic conditions slow capital investment, demand may become more replacement-driven than expansion-driven, which would reward reliability and service more than new unit sales. Capital intensity, installation constraints, and the need for practical process adaptation also mean that the strongest opportunities will likely accrue to players who can pair advanced functionality with implementable, site-specific solutions.
Actionable Guidance for Decision Makers
For manufacturers, the strategic priority is to move beyond equipment selection as a purely mechanical decision. Investments should be evaluated against total operating cost, cleanliness consistency, service accessibility, and integration with existing production workflows. The most resilient product and capacity strategies are likely to emphasize flexible configurations, measurable consumable efficiency, and support models that help customers sustain utilization. Companies that can demonstrate how blast performance reduces downstream rework or improves coating readiness will find stronger commercial traction than those competing mainly on headline specifications.
For investors, the attractive question is not simply whether demand will continue to grow, but which business models can convert growth into durable margins. Preference should be given to organizations with clear aftermarket revenue streams, repeatable installation and service processes, and credible differentiation in efficiency or compliance-related capabilities. It is also worth watching how regional expansion, localized support, and digital-enabled offerings reshape competitive dynamics, since these factors can influence both market share and long-term return profiles.
For procurement and operations leaders, the practical focus should be on total cost of ownership and process reliability. Selection criteria should include media consumption behavior, wear-part accessibility, filtration and containment readiness, changeover simplicity, and the supplier’s ability to support consistent utilization. Where possible, buyers should seek performance evidence tied to their own part types and throughput conditions rather than relying on generic capability claims. Aligning blast equipment with downstream quality requirements and labor realities can materially reduce operating risk.
Strategic decisions in this market are best made with detailed segmentation, regional nuance, and application-specific benchmarks in view. A targeted view of machine types, technology preferences, operational modes, end-use demand, and regional dynamics can clarify where investment, procurement, or partnership opportunities are most likely to pay off. For decision makers seeking a deeper breakdown of market size by segment, regional trajectories, competitive positioning, and scenario-based demand outlooks, the full PW Consulting report provides the supporting detail needed to translate these trends into concrete next steps.
For detailed analysis of this topic, please visit the official page: Shot Blasting Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


