



Pomegranate Market 2026-2032: Why 6.8% CAGR Growth Redefines Future Strategy

The Pomegranate Market: Strategic Trends and Commercial Opportunities Through 2032
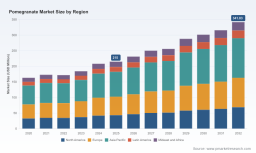
The global pomegranate market has transitioned from a niche seasonal offering to a mainstream, multi-segment commercial category. Total market revenue crossed the 215 million USD threshold in the base year, reflecting consistent expansion across production geographies and value-added formats. The sector has demonstrated a compound annual growth rate of 6.8 percent across the forecast horizon, a pace that positions pomegranates ahead of many legacy fruit categories but still requires deliberate portfolio strategy to capture. Revenue figures across the historical and projected periods illustrate a trajectory that moved from 163.15 million USD in 2020 to 341.83 million USD by 2032, with particularly pronounced expansions occurring after 2023. Such progression is not simply a function of acreage expansion; it reflects structural shifts in how fruit is processed, formulated, and positioned across food, wellness, and personal care applications.
For executives evaluating exposure to this category, the takeaway is that pomegranate is no longer a single-commodity story. The market now operates as an ecosystem where fresh fruit distribution, juice and concentrate processing, and ingredient-level applications for supplements and cosmetics interact with each other. This interconnected structure means that shifts in one segment can rapidly alter demand, pricing, and margin profiles across the broader chain. Understanding the interplay between volume growth, product-form diversification, and regional production patterns is essential before committing capital or reformulating supply strategies.
Key Structural Challenges and Inflection Points
Three pressures are reshaping how participants compete and where profitability is likely to concentrate. First, water intensity and irrigation discipline are becoming strategic variables rather than operational details. Recent scoping work in Western Cape orchards and commercial field trials have demonstrated that optimized irrigation scheduling can improve yield, fruit quality, and water use efficiency at the same time, which indicates that water management is a direct lever on quality consistency and cost structure rather than a compliance cost alone.
Second, labor exposure in high-touch orchard systems continues to pressure margins. Pruning and multi-stage harvesting can account for a substantial share of annual operational expenses in established European orchards, alongside significant upfront investment per hectare. This cost reality means that differentiation increasingly depends on agronomic efficiency, mechanization readiness, and yield consistency, not simply access to premium labeling or origin prestige.
Third, the category is being reshaped by the dominance of a few high-volume production centers alongside scattered but growing cultivation in newer regions. The structural imbalance between large-scale sourcing geographies and fragmented downstream processors creates both sourcing advantages and concentration risk, particularly for companies that rely on a narrow band of origin points or single processing formats. The practical implication is that resilience planning must account for agronomic variability, logistics continuity, and the ability to pivot across fresh and processed channels when weather, labor, or regulatory conditions shift.
Key Drivers Shaping the Pomegranate Market
The growth path is being generated by several reinforcing forces that operate across technology, regulation, consumer behavior, and cost structure. These drivers do not simply lift volume; they change which business models are likely to outperform.
Technological and Agronomic Innovation
Precision orchard management is becoming a core competitive advantage. Field evidence from commercial monitoring indicates that adjusting irrigation to a carefully managed fraction of evapotranspiration can improve fruit quality and yield while reducing cost and certain quality defects such as sun cracking. Equally important, the findings underline that evapotranspiration levels can vary widely across seasons and sites, so standardized irrigation assumptions are increasingly inadequate. For processors and brand owners, the strategic implication is that fruit quality consistency is becoming more dependent on upstream production discipline and traceability than on downstream blending or formulation alone.
Policy and Regulatory Context
Regulatory and environmental pressures are reinforcing the shift toward water-smart cultivation and documentation-intensive supply chains. In markets where water availability is tightening or where agricultural resource management is being scrutinized more closely, orchard-level efficiency is increasingly tied to license to operate. At the same time, cultivation expansion in newer regions is often supported by targeted investment in high-density systems and structured production programs. The broader lesson is that regulatory trends are not only creating constraints; they are also shaping where and how expansion is economically viable, particularly in regions where water productivity can be measured and improved.
Demand-Side Transformation
Consumer and corporate purchasing behavior is moving pomegranate further into wellness-oriented and convenience-driven use cases. Fresh fruit remains a foundation, but demand from food and beverage applications continues to be the largest consumption channel, reflecting both traditional culinary use and broader incorporation into beverages and formulated products. At the same time, nutraceutical and supplement use, along with cosmetics and pharmaceutical applications, adds a higher-value demand layer that rewards standardized extracts, stable concentrates, and ingredient-grade consistency. For commercial strategy, this means the same raw crop can support multiple value pathways, but each pathway requires different quality thresholds, formulation controls, and positioning.
Supply Chain and Cost Structure Evolution
Cost structure is being redefined by the interaction of labor intensity, capital investment per hectare, and the economics of processing form. Orchards that rely heavily on manual pruning and repeated harvesting face structurally higher operating costs, while growers adopting denser plantings and more controlled inputs can improve unit economics if they can sustain quality and yield. On the processing side, the economics of juice, concentrate, and other processed forms depend on fractionation efficiency, shelf-life management, and the ability to serve both bulk ingredient buyers and branded consumer channels. The combined effect is that margin leadership is increasingly determined by integrated efficiency from orchard to finished product, rather than by any single step in isolation.
Competitive Landscape and Leading Strategies
The competitive environment includes vertically integrated growers, branded fruit and juice operators, organic-focused processors, and international ingredient exporters. The market remains moderately fragmented at the top, with concentration levels indicating room for consolidation but also for differentiated niches. That combination matters because it means scale is not the only path to leadership; consistency, origin storytelling, certification, and format specialization can all support premium positioning.
Strategic Positioning of Key Players
Vertically integrated operators that control both growing and processing have a structural advantage in managing quality, timing, and channel mix. By managing cultivation alongside juice and value-added products, these companies can reduce dependency on third-party sourcing and create tighter feedback loops between orchard outcomes and finished product specifications. Their differentiation often rests on branded narrative, consistent supply, and the ability to offer multiple formats from a single origin. These are powerful advantages in consumer-facing channels, but they also require disciplined execution across agronomy, cold chain, and product development.
Organic and family-oriented processors compete through provenance, minimal-processing positioning, and consumer trust. In categories where label simplicity and clean formulation matter, these players can command attention even without the broadest distribution footprint. Their challenge is scaling while preserving the operational discipline and certification standards that support their positioning. For ingredient buyers, such producers can be attractive where traceability and organic integrity are procurement priorities.
PW Consulting Health Care Research Center
International ingredient exporters, particularly from major production geographies, play a different role: they supply bulk fruit products, pulps, concentrates, pastes, and fresh fruit for broader distribution networks. These companies are important to the market because they provide volume flexibility and geographic reach, especially for processors and formulators that need consistent input supply across seasons. Their competitive edge typically comes from sourcing scale, processing capability, export logistics, and the ability to match specifications for both food service and industrial buyers.
How the Landscape Is Evolving
The market is showing signs of both consolidation and fragmentation depending on the segment. In branded consumer channels, scale and marketing intensity favor players who can sustain shelf presence and brand recognition. In ingredient and processed forms, the trend is more fragmented, with regional and origin-specific suppliers competing on cost, quality consistency, and service reliability. At the same time, newer cultivation regions are expanding, which introduces additional sourcing diversity and can reduce dependence on a narrow set of origins over time.
Another important shift is the growing relevance of supply-side innovation as a competitive differentiator. Where water productivity, irrigation scheduling, and yield optimization are measurable and improved, suppliers can offer better quality and more predictable delivery. This is gradually turning agronomic performance into a commercial asset rather than a private operational matter. Companies that can document efficiency, quality stability, and responsible resource use are better positioned to enter higher-value contracts and withstand volatility in labor or weather conditions.
Future Trends and Commercial Opportunities
Looking ahead across the next three to five years, several trends are likely to define where value is created and where risk accumulates.
Trend One: Water-Smart Production as a Purchasing Criterion
Water productivity is moving from an operational concern to a procurement differentiator. Evidence from orchard monitoring and irrigation studies indicates that optimized water use can support both quality and cost performance, which suggests that buyers will increasingly favor suppliers who can demonstrate responsible irrigation management and consistent output under variable conditions. The commercial opportunity lies in tying sourcing decisions to measurable production efficiency, not only to price or origin. Suppliers able to provide verifiable efficiency data, stable quality, and documented yield improvement are likely to gain preference in higher-value contracts and long-term supply arrangements.
The uncertainty here is that water conditions, regulatory expectations, and climate variability differ significantly by region. Strategies that work where evapotranspiration is highly variable may need adjustment in other contexts, and over-reliance on a single improvement model could leave some operators exposed if local conditions change.
Trend Two: Format Diversification Will Outpace Single-Channel Growth
The market will continue to reward companies that can move fluidly across fresh fruit, juice and concentrate, and other processed forms. This diversification matters because different formats absorb seasonality and price volatility differently, and because downstream demand is spread across food and beverage, nutraceuticals, supplements, and cosmetics or pharmaceutical uses. Companies that can align product-form capability with the quality requirements of each channel are better positioned to capture multiple revenue streams from the same crop base.
The strategic opportunity is to treat product form as a portfolio decision rather than an operational afterthought. Where a company can efficiently fractionate fruit into fresh, juice, concentrate, or ingredient-grade outputs, it can better serve both consumer-facing and industrial buyers. The risk is that format expansion can dilute focus or strain quality control if processing lines, specification management, and customer support are not designed to handle varied applications.
Trend Three: Origin Expansion and Sourcing Reconfiguration
Cultivation is expanding in regions that have historically been smaller players, supported by investment in production systems and targeted development programs. This trajectory introduces new sourcing options and gradually broadens the geographic base of supply. For buyers, the opportunity is greater flexibility, potential cost arbitrage, and reduced concentration risk. For growers and processors, it is a chance to enter supply chains that value differentiated origin, consistent quality, and documented efficiency.
Garnet Market
The uncertainty is execution. Newer production regions often face startup costs, learning-curve effects, and logistics complexity. The most attractive opportunities will not automatically go to regions with expansion potential; they will go to those that can combine growth with quality reliability, export readiness, and credible performance data.
Actionable Guidance for Decision-Makers
For Manufacturers and Consumer-Facing Brands
Treat pomegranate as a multi-format portfolio rather than a single ingredient. Build flexibility into sourcing and processing so that fresh, juice, concentrate, and value-added forms can be balanced according to demand and margin. Where possible, align product development with applications that reward consistency and documentation, since those uses are likely to grow alongside wellness and personal care demand. Prioritize suppliers whose agronomic discipline and quality traceability are visible and verifiable, as those attributes are increasingly tied to commercial reliability.
For Investors
Evaluate exposure across the value chain rather than assuming that volume growth alone translates into returns. The most resilient opportunities are likely to be found where operational efficiency, format diversification, and measurable sustainability performance reinforce one another. Look closely at companies that can demonstrate water productivity improvements, controlled labor exposure, and the capability to serve more than one demand channel. Equally important, assess concentration risk in sourcing regions and the readiness of supply bases to adapt to weather, labor, and regulatory shifts.
Avocado Market
For Procurement and Supply Chain Leaders
Diversify origin exposure while maintaining specification rigor. Multi-origin strategies can reduce vulnerability to localized weather, labor, or logistics disruption, but they only work if quality standards and documentation are consistently applied across suppliers. Consider sourcing criteria that include irrigation efficiency, yield stability, and the ability to provide evidence of production discipline. Where possible, structure relationships that allow flexibility across processed forms so that supply continuity can be maintained when fresh-market conditions or processing availability shift.
Closing Perspective
The pomegranate market is entering a phase where commercial success depends less on simple category growth than on structural clarity: how fruit is produced, how it is processed into different forms, and how well participants can demonstrate value beyond price. The combination of water-smart production, format diversification, and broadening origin geography is expanding the strategic surface area of the category. That expansion rewards companies that can align quality, efficiency, and application fit across multiple channels. It also raises the cost of passive sourcing, since buyers and investors alike are increasingly exposed to agronomic variability, labor intensity, and concentration risk. In that environment, the most valuable next step is to move from broad category confidence to precise, segment-level intelligence that supports sourcing, product, and investment choices with greater certainty.
For detailed analysis of this topic, please visit the official page: Pomegranate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


