



Composite Insulators Market: Why 6.98% CAGR Redefines 2032 Revenue Trajectory

Composite Insulators Market: Strategic Trends and Commercial Opportunities Through 2032
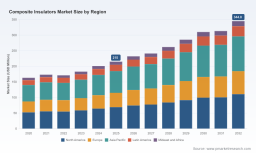
The composite insulators market has transitioned from a niche alternative to a mainstream component in high-voltage infrastructure, reflecting a structural shift in how utilities and OEMs approach reliability, weight, and maintenance economics. Valued at approximately 215.0 million USD in 2025 and projected to reach 344.8 million USD by 2032, the market follows a compound annual growth rate of 6.98 percent across the 2026–2032 forecast window. Growth from 163.15 million USD in 2020 to 215.0 million USD in 2025 illustrates a steady expansion trajectory, with momentum accelerating through the end of the decade. This trajectory is not simply volume-driven; it signals a maturing value proposition where polymer-based designs are increasingly selected for their durability in harsh environments, reduced creepage requirements, and compatibility with modular grid architectures.
Behind the headline numbers lies a market that is gaining confidence but not without friction. The sector is navigating raw material volatility, evolving certification expectations, and a competitive landscape that is consolidating around firms with differentiated manufacturing depth. For executives and investors, the question is no longer whether composite insulators will capture additional share, but where the highest-margin segments will form, which capabilities will separate winners from commoditized producers, and how supply chain and regulatory dynamics will shape returns over the next five years.
A Market at an Inflection Point
The current landscape is defined by three intersecting pressures that are reshaping strategy across the value chain. First, cost structures are increasingly sensitive to input price swings, particularly in resin and fiberglass, which directly influence pultrusion economics and margin stability. Second, international standards are tightening, raising the bar for sheath integrity, interface quality, and long-term performance validation. Third, the supplier base is undergoing selective consolidation, with larger multinational groups acquiring specialized production assets to secure technology, capacity, and certification portfolios. These forces are not isolated; together they are increasing the importance of process integration, quality assurance, and regional compliance readiness.
For market participants, the practical implication is that scale alone is no longer a sufficient advantage. Competitors that can control core manufacturing steps, align product designs with updated standards, and demonstrate consistent performance in demanding applications are better positioned to defend pricing and win long-term utility contracts. Firms that remain dependent on fragmented sourcing or minimal differentiation face greater exposure to price competition and specification-driven disqualification.
Core Drivers Reshaping Demand and Supply
Several structural drivers are underpinning the market’s expansion, and each carries distinct implications for product strategy and commercial positioning.
Technological innovation continues to broaden the applicability of composite insulators. Advances in silicone rubber formulations and hollow-core engineering are enabling lighter, more hydrophobic solutions that perform well in polluted or high-humidity environments. The release of new high-consistency silicone rubber for composite insulator production illustrates how material innovation is opening design space for manufacturers, especially where traditional porcelain or glass solutions carry weight, breakage, or maintenance penalties. At the same time, process technologies that improve interface quality and sheath uniformity are becoming more important as standards raise minimum performance thresholds.
Policy and regulatory evolution is sharpening the focus on compliance and interoperability. Updated frameworks such as IEC 61109 Edition 3.0 and EN IEC 62217:2025 are reinforcing expectations around sheath thickness, interface quality, and defined performance classes for polymeric high-voltage insulators. These revisions do more than set technical baselines; they reduce ambiguity for specifiers and create a more uniform path for manufacturers seeking to serve multiple regions. In practice, this is encouraging producers to invest in certification readiness and to design families of products that can be validated across transmission, substation, and distribution contexts.
Demand-side behavior is also changing. Utilities and industrial operators increasingly favor solutions that reduce footprint, simplify installation, and lower long-term maintenance burden. Composite insulators are gaining traction where their mechanical resilience and corrosion resistance translate into lower lifecycle risk, especially in remote corridors, coastal settings, or regions with aggressive atmospheric contamination. At the same time, the broader push toward grid modernization and expanded transmission capacity is lifting volumes across both overhead lines and substation equipment, broadening the addressable base beyond traditional replacement cycles.
PW Consulting Chemical & Energy Research Center
Supply chain and cost dynamics remain a critical variable. Pultruded fiberglass profiles for composite insulator cores generally cost between 5 and 15 USD per linear foot, or roughly 2 to 10 USD per pound depending on resin selection and customization. This range underscores how sensitive production economics are to glass fiber and resin pricing, and why manufacturers with integrated processes or disciplined procurement strategies can achieve more stable margins. When raw material prices fluctuate, the impact is not limited to input cost; it ripples through lead times, quotation reliability, and the ability to scale capacity without eroding unit economics.
Competitive Landscape and Leading Strategies
The competitive environment is characterized by a mix of technologically specialized manufacturers, regionally concentrated producers, and multinational groups pursuing targeted expansion. Market concentration remains moderate, with the top three firms holding approximately 24.6 percent and the top five about 26.2 percent of the market. This fragmentation suggests room for both differentiation and consolidation, depending on the segment and geography.
Worldwide Low Voltage Insulators Market
Leading players are pursuing distinct strategic positions. Some manufacturers emphasize full vertical integration in hollow composite insulator production, building end-to-end control over core fabrication, housing, and final assembly. This model is particularly valuable where OEMs and utilities prioritize traceability, repeatability, and the ability to offer alternative gas or insulation options. Others compete on breadth of product families, covering suspension, line post, pin, tension, and bushing types across transmission, substation, and distribution networks. That breadth can be a strong commercial advantage when specifiers want a single source for multiple asset classes, especially in large-scale grid build-outs.
A third strategic theme is technology-led specialization. Certain producers focus on epoxy-resin glass fiber cylinders and high-temperature injection or advanced molding technologies that target substation and line applications requiring precise mechanical and electrical performance. These capabilities can support premium positioning when paired with rigorous qualification data and strong service networks. In parallel, manufacturers active in Asia and India continue to expand capacity and export reach, often competing on combination of cost, scale, and growing technical credibility. Their growth reflects both domestic demand and the broader international search for reliable supply alternatives.
Recent industry developments offer a clear window into how the landscape is evolving. The introduction of new silicone rubber materials for composite insulator production highlights the ongoing push to improve material consistency and processing efficiency. Meanwhile, corporate moves such as the acquisition of composite insulator production facilities by a larger group, including machinery and intellectual property, point to a strategy of securing specialized manufacturing assets and expanding capacity in established industrial regions. This kind of transaction suggests that controls over core processes, proprietary know-how, and certified production lines are becoming strategic assets rather than mere operational inputs.
Trade show participation and regional exhibition activity also indicate where companies are concentrating commercial effort. Exhibiting advanced high-voltage composite insulators at international grid equipment events and utility-focused conferences signals a continued emphasis on face-to-face specification engagement, particularly in markets where project pipelines are active and relationships with utilities, contractors, and system integrators matter.
Taken together, the competitive picture suggests three unfolding dynamics. First, differentiation is shifting toward process depth, materials expertise, and certification readiness rather than catalog breadth alone. Second, consolidation is likely to continue in pockets where complementary technologies, regional access, or specialized production assets create clear value. Third, new entrants and expanding regional manufacturers will keep pressure on pricing in commodity-adjacent segments, while more engineered applications remain open to firms with strong technical validation and application support.
Forward Outlook: Trends and Commercial Implications
Over the next three to five years, the market is likely to be shaped by the intersection of materials progress, standards-driven specification clarity, and selective consolidation. The first trend is the continued migration of composite insulators into higher-value applications where performance under stress, weight reduction, and maintenance savings justify the choice over traditional alternatives. This shift will not be uniform; it will concentrate in environments where contamination, humidity, vibration, or access limitations make polymer-based designs especially advantageous.
Composite Insulated Panels Market
The second trend is the growing importance of compliance as a commercial differentiator. As updated standards raise expectations for sheath quality, interface integrity, and consistent high-voltage performance, manufacturers that can demonstrate robust qualification processes and repeatable production control will gain an advantage in tender evaluations and OEM supply agreements. Certification readiness is becoming less of a back-office function and more of a market-access requirement, particularly for suppliers targeting multiple regions or working with large multinational buyers.
The third trend is the continued realignment of manufacturing capacity and ownership. Strategic acquisitions and capacity expansions in established production hubs indicate that scale, technology control, and localized capability will matter more as customers seek reliable supply and shorter qualification cycles. At the same time, raw material sensitivity will keep cost discipline and formulation flexibility in focus, especially where resin and fiberglass pricing can compress margins or disrupt quoting.
These trends create concrete commercial opportunities. There is room for product strategies that pair material consistency with application-specific design, enabling suppliers to serve both transmission and substation segments without diluting manufacturing focus. There is also opportunity in regional expansion where grid investment is accelerating and where localized support, certification alignment, and service responsiveness can outweigh pure price competition. For buyers, the opportunity lies in reducing lifecycle risk through more predictable performance and in consolidating the supplier base where quality assurance and technical support can be managed more efficiently.
Risks and uncertainties remain. Raw material volatility can quickly alter cost assumptions and erode the economics of capacity expansions if not managed with hedging, formulation options, or process efficiencies. Regulatory updates, while beneficial in the long run, can impose rework, retesting, or redesign costs if product families are not aligned early. In addition, intensified competition in volume-oriented segments may pressure margins even as premium segments expand, creating a bifurcated market where profitability depends heavily on positioning and execution.
Strategic Implications for Decision Makers
Manufacturers should prioritize capabilities that convert technical advantage into commercial advantage. That means investing in process integration where it strengthens quality, consistency, and traceability; aligning product families with updated standards before specification cycles lock in; and building formulation and procurement flexibility to absorb raw material swings. Where possible, firms should also consider targeted expansion of engineered product lines rather than undifferentiated catalog growth, since higher-value applications are likely to reward proven performance and application support more than breadth alone.
Investors should evaluate exposure not just to market growth but to the underlying drivers of margin durability. Capacity expansions, technology acquisitions, and regional entry decisions all look more attractive when paired with certification readiness, material expertise, and a clear route to utility or OEM demand. The most resilient opportunities are likely to emerge where operators can demonstrate control over critical production steps and where the customer base values reliability and lifecycle performance enough to support disciplined pricing.
Procurement and specification teams should treat composite insulator selection as a lifecycle decision rather than a unit-price comparison. Evaluating sheath quality, interface design, material consistency, certification status, and supplier process control can reduce installation risk and long-term maintenance exposure. Consolidating suppliers where supported by strong technical documentation and consistent qualification data may also improve procurement efficiency, especially across transmission, substation, and distribution programs with overlapping performance requirements.
Closing Perspective
The composite insulators market is entering a phase where growth is increasingly tied to technical credibility, standards alignment, and strategic control of manufacturing depth. The pathway from 215.0 million USD in 2025 to 344.8 million USD by 2032 will not be evenly distributed across every supplier or segment. Instead, value will accrue to participants that can combine material innovation, compliance readiness, and operational discipline with a clear focus on the applications where composite designs deliver the strongest economic and technical case. For organizations operating in or adjacent to this market, the most valuable next step is to map these shifts against specific product portfolios, regional pipelines, and procurement strategies, and to update assumptions as standards, materials, and ownership structures continue to evolve.
For detailed analysis of this topic, please visit the official page: Composite Insulators Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


