



DSL Chipset Market 2026: Understanding the [5.94%] CAGR Beyond Reported Figures

DSL Chipsets Market: Strategic Trends and Commercial Opportunities
The DSL chipsets market has entered a period of measured but steady expansion, driven by the continuing need for high-speed broadband access in regions where fiber deployment remains incomplete or economically challenging. Valued at approximately USD 215.0 million in 2025, the market is projected to reach USD 322.0 million by 2032, reflecting a compound annual growth rate of 5.94 percent. This trajectory indicates a mature segment that is not experiencing explosive growth, but rather a sustained, technology-driven evolution shaped by infrastructure realities, competitive dynamics, and shifting demand patterns. For executives and investors operating in broadband hardware, semiconductor supply chains, or telecommunications infrastructure, understanding the forces shaping this market is essential to positioning for the next cycle of investment and product development.
The historical trajectory from 2020 through 2025 reveals a market that has recovered from pandemic-era supply disruptions and stabilized around a baseline of consistent demand. Growth has been supported by incremental upgrades to existing copper-based access networks, particularly in residential and commercial environments where last-mile connectivity continues to rely on xDSL technologies. The forecast period through 2032 suggests that DSL chipsets will maintain relevance, though the pace of expansion will be moderated by the gradual migration toward fiber and wireless alternatives in certain geographies. The market's resilience lies not in volume breakthroughs, but in the ability of chipset vendors to deliver higher throughput, improved power efficiency, and more flexible architectures that extend the useful life of copper infrastructure while accommodating next-generation access requirements.
Market Overview: Positioning in a Mature but Evolving Segment
The DSL chipsets market operates at the intersection of legacy infrastructure and modern broadband expectations. Copper-based networks remain deployed across large portions of the global access landscape, particularly in areas where fiber rollout has been delayed by terrain, cost, or regulatory hurdles. In these environments, DSL chipsets continue to serve as the enabling technology for delivering broadband services that meet contemporary speed and reliability standards. The market's size and growth profile reflect a balance between ongoing replacement cycles, incremental upgrades, and the introduction of higher-performance variants such as VDSL2 and G.fast, which have gained traction in dense urban and suburban deployments where copper vectoring can deliver meaningful throughput improvements.
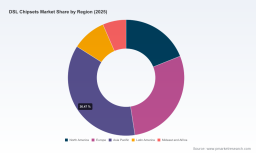
Several structural features define the current market environment. Demand is distributed across residential, commercial, and industrial applications, with residential connectivity representing the largest share of end-use volume. Regional demand patterns vary considerably, with Asia Pacific representing the largest market by value, followed by Europe and North America. Latin America and the Middle East and Africa contribute smaller but growing shares, often driven by infrastructure expansion programs and emerging broadband adoption. The market is characterized by moderate concentration, with the top three players accounting for roughly a quarter of total revenue and the top five holding approximately a third. This fragmentation indicates that no single vendor dominates the landscape, creating room for specialized players, regional competitors, and technology-focused entrants to compete on performance, cost, and support capabilities.
The competitive environment is further shaped by the coexistence of established semiconductor manufacturers and specialized DSL technology providers. Broadcom, MaxLinear, Texas Instruments, Intel's Lantiq division, Qualcomm's Ikanos portfolio, STMicroelectronics, Marvell, Realtek, Sckipio, and Hitron Technologies each occupy distinct positions in the value chain, with product portfolios spanning ADSL, VDSL, and G.fast solutions. The presence of multiple well-resourced incumbents alongside niche specialists suggests a market where differentiation is driven by architecture, power management, signal processing capability, and the ability to support high-density deployment scenarios. This diversity also implies that pricing pressure and technology migration risks are distributed unevenly across vendors, depending on their product focus and geographic exposure.
Key Challenges and Inflection Points
Despite the market's steady growth profile, several challenges and transition points warrant attention. The first is the ongoing tension between copper-based access and fiber migration. While DSL chipsets continue to serve a meaningful role in existing networks, the long-term trajectory of broadband infrastructure favors fiber in many developed markets. This does not eliminate demand for DSL solutions, but it does require vendors and buyers to assess where copper upgrades remain economically viable and where fiber investment will eventually render DSL chipsets obsolete in specific service areas. The inflection point lies in determining the pace of fiber rollout and the extent to which G.fast and VDSL2 can sustain service quality in the interim.
PW Consulting
A second challenge is supply chain concentration risk. Advanced G.fast and VDSL2 chipsets are increasingly manufactured on leading-edge CMOS nodes at a limited set of foundries, including TSMC and Samsung. This concentration creates potential production vulnerability, particularly in the event of geopolitical disruptions or capacity constraints. For manufacturers and buyers who rely on these advanced nodes, the risk is not merely theoretical; it affects lead times, cost stability, and the ability to scale production in response to demand fluctuations. The implication is that supply chain resilience is becoming a strategic consideration, not just an operational one.
A third challenge comes from pricing dynamics in volume-sensitive segments. In ADSL customer premises equipment markets, particularly in Asia and emerging economies, Chinese semiconductor vendors have developed competitive domestic alternatives that exert downward pressure on average selling prices. This pricing pressure complicates margin expectations for incumbents and raises the bar for differentiation. At the same time, geopolitical restrictions have limited the penetration of certain Chinese DSL chipsets in Western markets, creating a bifurcated competitive landscape where regional accessibility and trade policy influence market share as much as product performance.
Together, these challenges point to a market that is not standing still. Vendors and buyers must navigate the intersection of technology lifecycle, supply chain exposure, and regional competitive dynamics. The companies that succeed will be those that can align product roadmaps with realistic infrastructure timelines, manage sourcing risk, and maintain differentiation in the face of pricing pressure.
Key Growth Drivers
Technology Innovation and Signal Processing Advances
Technology development remains a central driver of market activity. Chipset vendors have increasingly focused on improving throughput, reducing noise, and enhancing power efficiency within the constraints of copper-based transmission. Intel's Lantiq division, for example, has emphasized AI-enhanced DSP algorithms for DSL applications, targeting throughput improvements in the 20 to 30 percent range. Such advances are significant because they extend the capability of existing copper infrastructure without requiring immediate fiber replacement, allowing service providers to improve customer experience while managing capital expenditure. Similarly, Broadcom's BCM65x00 family and BCM65550 G.fast vector processor chipsets support high-density multi-DSL and vectoring applications across ADSL2+, VDSL2, and G.fast standards, reflecting a focus on central office and access equipment that can handle multiple line types in a single platform.
MaxLinear's recent product activity illustrates another dimension of technological progress. The company's announcement of an intelligent modular power management solution for next-generation broadband SoCs, supporting DSL, fiber, cable, and fixed wireless access gateways, highlights a shift toward integrated architectures that address power, thermal, and modularity requirements across multiple access technologies. This kind of cross-platform competence is valuable because it allows equipment manufacturers to streamline design cycles and reduce component complexity, even as they support diverse access standards.
Policy and Regulatory Environment
Policy and regulatory developments also shape market dynamics. In the United States, the CHIPS Act incentives have enhanced domestic semiconductor processing capacity, with new facilities expected to create approximately 2,000 jobs by 2029. While the CHIPS Act is broader than DSL chipsets, its impact on domestic manufacturing capacity and supply chain diversification is relevant to any semiconductor segment that depends on advanced nodes and stable production environments. Improved domestic capacity can reduce exposure to geopolitical risk and support more predictable sourcing for vendors and buyers who prioritize supply assurance.
At the same time, regulatory and trade dynamics continue to influence regional market access. Geopolitical restrictions have limited the penetration of certain Chinese DSL chipsets in Western markets, even as those vendors maintain strong deployments in China and other regions. This divergence creates a fragmented competitive landscape where product availability is shaped not only by technical merit, but also by trade policy and national security considerations. For multinational equipment manufacturers, this means that chipset selection cannot be evaluated in isolation from sourcing geography and regulatory risk.
Demand-Side Shifts and Infrastructure Realities
Demand-side behavior continues to support DSL chipset relevance in specific contexts. Residential broadband remains a primary application, with consumers and households expecting reliable connectivity for streaming, remote work, education, and smart home services. In areas where fiber is not yet available, copper-based solutions continue to meet these needs, and upgrades to VDSL2 or G.fast can deliver meaningful improvements in speed and stability. Commercial and industrial applications also contribute to demand, though at lower volume shares, as businesses and facilities rely on broadband access for operations, monitoring, and connectivity in environments where fiber deployment may be delayed or impractical.
The broader demand picture is influenced by the pace of infrastructure investment and the economic calculus of upgrading versus replacing. In many markets, extending the life of copper networks through higher-performance chipsets is a cost-effective strategy, particularly when paired with vectoring and other throughput-enhancing techniques. This demand dynamic supports continued chipset sales, but it also requires vendors to justify the value of DSL solutions against the backdrop of fiber migration plans and wireless alternatives.
Supply Chain and Cost Structure Considerations
Cost structure and supply chain strategy are increasingly important drivers of competitive outcomes. The concentration of advanced node manufacturing among a limited number of foundries means that cost volatility and supply risk are not evenly distributed. Vendors that can secure reliable access to leading-edge production, or that can architect chipsets to operate effectively on more accessible process nodes, may gain an advantage in cost predictability and delivery assurance. At the same time, pricing pressure in ADSL CPE segments from competitive domestic alternatives in China underscores the importance of managing bill-of-materials costs and offering value that goes beyond raw chipset performance.
The cost dynamic also intersects with product architecture. Integrated power management, modular designs, and support for multiple access standards can reduce system-level costs for equipment manufacturers, creating value that is not captured by chipset pricing alone. In this sense, the commercial opportunity is not only in selling chipsets, but in enabling lower total cost of ownership and simpler integration for the broader access ecosystem.
Competitive Landscape and Leading Strategies
The competitive landscape is defined by a mix of broad-line semiconductor companies and DSL-focused specialists. Broadcom and Intel's Lantiq division occupy positions that emphasize vector processing, high-density support, and algorithm-driven throughput improvements. Broadcom's BCM65x00 family and BCM65550 G.fast vector processor address central office and multi-DSL scenarios, while Intel's Lantiq division leverages AI-enhanced DSP to target measurable throughput gains. These strategies reflect a focus on performance and integration in environments where dense line handling and advanced signal processing are critical.
MaxLinear differentiates through broadband SoC power management and modular architectures that span DSL, fiber, cable, and FWA gateways. This approach positions the company as a supplier capable of supporting next-generation access equipment with integrated power and control solutions, rather than offering DSL chipsets in isolation. Texas Instruments contributes analog components and integrated circuits optimized for DSL applications, including low-noise pre-amps and ADC-capable components, supporting the signal chain requirements of DSL systems. Qualcomm's Ikanos Communications portfolio provides ADSL, VDSL, and G.fast chipset options for broadband applications, while STMicroelectronics supplies semiconductor solutions and components for xDSL standards in access network equipment. Marvell offers DSL chipset solutions for broadband access and CPE applications, with support for VDSL and G.fast technologies.
Realtek focuses on cost-effective DSL chipsets primarily for ADSL CPE segments in Asia and emerging markets, reflecting a strategy centered on volume and affordability. Sckipio specializes in G.fast chipset solutions for high-density DSL deployments, targeting environments where advanced copper vectoring is a priority. Hitron Technologies develops DSL chipsets and gateways for CPE and broadband access platforms, combining chipset and endpoint capabilities in certain segments. This diversity of focus illustrates a market where differentiation is achieved through product scope, regional emphasis, technology specialization, and system-level integration.
The market is evolving through a combination of consolidation pressure and niche specialization. Larger players with broad portfolios can leverage cross-platform competence and supply chain scale, while specialized vendors can compete on G.fast performance, power efficiency, or regional cost leadership. At the same time, the influence of Chinese domestic alternatives in volume-sensitive ADSL segments and the constrained access of certain vendors in Western markets suggest that competitive outcomes will increasingly depend on geographic strategy, regulatory alignment, and the ability to deliver differentiated value beyond price alone. The trend is not toward a single dominant architecture, but toward a multi-vector landscape where incumbents, specialists, and regional competitors each pursue distinct advantages.
Power Over Ethernet Poe Chipset Market
Future Trends and Commercial Opportunities
Looking ahead, three trends are likely to shape the market over the next three to five years. The first is the continued optimization of copper-based access through higher-performance chipsets and vectoring techniques. G.fast and VDSL2 will remain relevant in dense urban and suburban environments where fiber rollout is gradual, and chipset improvements that deliver higher throughput and better noise resilience will sustain demand. The commercial opportunity lies in enabling service providers to extract more value from existing copper assets while planning for eventual fiber migration, creating a bridge technology that supports revenue and customer retention.
The second trend is the increasing importance of power management and modular architectures. As access equipment becomes more integrated and energy-aware, chipsets that contribute to lower power consumption, simpler thermal management, and flexible platform design will be more attractive to equipment manufacturers. MaxLinear's modular power management approach for broadband SoCs is one example of this direction. The opportunity here is not limited to chipset performance; it extends to system-level cost reduction and design simplification, which can be decisive in competitive CPE and access equipment markets.
Wi-Fi Chipsets Market
The third trend is supply chain resilience and regional diversification. Given the concentration of advanced node production and the influence of geopolitical and trade dynamics, vendors and buyers will place greater weight on sourcing security, domestic capacity, and supplier diversification. The CHIPS Act-driven expansion of U.S. semiconductor processing capacity is one indicator of this shift. For companies that can demonstrate reliable supply, flexible architecture, and alignment with regional regulatory expectations, this trend creates an opportunity to build trust and secure long-term design wins, particularly in markets where supply assurance is a priority.
These trends are not without risk. Fiber migration could accelerate in certain regions, reducing the addressable market for DSL chipsets faster than anticipated. Supply chain concentration may continue to expose advanced node-dependent products to disruption. Pricing pressure could intensify in volume segments, compressing margins for vendors that cannot differentiate effectively. And regulatory or trade shifts could alter the competitive balance in specific geographies. The commercial opportunity is real, but it requires a clear-eyed assessment of where copper-based DSL solutions remain viable, how supply risk is managed, and what value proposition justifies adoption in a changing infrastructure landscape.
Strategic Recommendations for Decision Makers
For manufacturers and chipset vendors, the priority is to align product roadmaps with realistic infrastructure timelines and to invest in differentiation that goes beyond raw speed. Power management, modular architectures, and support for high-density deployments can create value that resonates with equipment makers seeking lower system cost and simpler integration. Securing reliable access to advanced nodes, or designing for process flexibility where possible, should be treated as a strategic capability rather than a sourcing detail. In volume-sensitive segments, cost leadership must be paired with defensible differentiation to avoid margin erosion from competitive domestic alternatives.
For investors, the market offers exposure to a mature but resilient segment with steady growth and clear technology-driven demand drivers. The key is to evaluate vendors based on their ability to manage supply chain concentration, navigate regional competitive dynamics, and deliver differentiated architectures that support multi-standard access equipment. Companies with strong positions in G.fast and VDSL2, effective power management solutions, and diversified sourcing strategies are better positioned to sustain value as the market evolves. Investors should also monitor the pace of fiber migration and the impact of trade policy on regional market access, as these factors can influence demand trajectories and competitive outcomes.
For procurement and network planning teams, chipset selection should be evaluated in the context of total cost of ownership, supply assurance, and alignment with infrastructure roadmaps. Where copper-based solutions are part of a longer-term access strategy, prioritizing chipsets that support higher throughput, efficient power use, and flexible integration can reduce lifecycle cost and improve service quality. Where supply risk is a concern, diversifying sourcing and considering vendors with stronger regional manufacturing alignment may provide additional assurance. Procurement decisions should also account for the competitive and regulatory environment in each geography, as market access and pricing dynamics can vary significantly across regions.
For executives and planners seeking a deeper understanding of segmentation dynamics, regional demand patterns, pricing structures, and vendor-specific positioning, a more detailed research report can provide the granular data and tailored analysis needed to support precise decisions. Comprehensive segmentation breakdowns, competitive benchmarking, and scenario-based forecasts can help translate the strategic themes discussed here into actionable plans for product development, investment, and procurement.
For detailed analysis of this topic, please visit the official page: DSL Chipsets Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


