



5 Forces Reshaping Gunshot Detection Systems Market to $2.25B by 2032

The Acoustic Edge: Strategic Trends and Commercial Opportunities in the Gunshot Detection Systems Market
Urban safety architecture is undergoing a fundamental reassessment. As municipal authorities, critical infrastructure operators, and defense contractors confront escalating security threats, the market for gunshot detection systems has transitioned from a niche public safety tool to a core component of integrated security ecosystems. Valued at approximately USD 1.04 billion in 2025, the sector is projected to expand to USD 2.25 billion by 2032, reflecting a compound annual growth rate of 11.8 percent over the forecast period. This trajectory is not merely a function of rising threat perception; it represents a structural shift in how organizations approach real-time threat identification, response automation, and cross-platform interoperability. For executives navigating capital allocation, technology roadmaps, or procurement strategies, understanding the underlying dynamics of this market is no longer optional.
The growth pattern reveals a market maturing beyond initial adoption cycles. Historical data from 2020 through 2025 shows consistent year-over-year expansion, with the 2025 valuation marking a notable inflection point where commercial and institutional deployments began scaling in parallel with military and homeland security applications. Looking ahead to 2032, the revenue curve suggests sustained momentum rather than a temporary surge. This outlook is underpinned by converging technological advancements, evolving regulatory frameworks, and a clear demand-side pivot toward systems that deliver actionable intelligence rather than passive alerting. Yet growth alone does not guarantee strategic advantage. The market carries structural complexities, technological trade-offs, and competitive pressures that demand careful navigation.
Market Landscape and Core Challenges
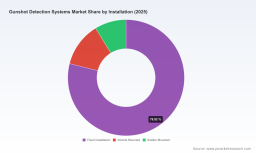
The gunshot detection sector operates at the intersection of acoustic engineering, sensor fusion, and emergency response logistics. Revenue distribution across installation types reflects a clear preference for permanent, infrastructure-integrated deployments, which continue to dominate commercial and municipal contracts. Vehicle-mounted and soldier-mounted configurations maintain a strong presence in defense and tactical mobility applications, while the split between indoor and outdoor use cases highlights a persistent operational reality: outdoor environments account for the majority of deployment volume due to their coverage requirements and public safety mandates, yet indoor installations carry disproportionately high value in critical facilities where response time precision is non-negotiable.
Worldwide Automatic Noise Monitoring System Market
Challenge 1: False Positive Management and Environmental Interference
No metric captures the operational friction of this market more accurately than false positive rates. Acoustic sensors operating in dense urban environments, industrial zones, or high-traffic transit hubs must continuously differentiate between genuine ballistic events and environmental noise—construction equipment, vehicle backfires, fireworks, and even structural resonance. The consequence of misclassification extends beyond alert fatigue; it erodes trust in automated response protocols and can trigger costly emergency mobilization. Recent product iterations have leaned heavily on multi-sensor fusion and machine learning refinement to address this gap, but environmental variability remains a persistent engineering constraint.
Challenge 2: Certification Bottlenecks and Procurement Complexity
Deployment at scale increasingly hinges on regulatory alignment rather than raw sensor performance. In the United States, DHS SAFETY Act certification has become a functional prerequisite for suppliers targeting government agencies and critical infrastructure operators. Without this designation, manufacturers face restricted access to federal contracts and limited eligibility for institutional procurement channels. In the United Kingdom, the National Police Chiefs' Council has reinforced similar expectations through the NPSA Technical Guidance, requiring all deployed systems to appear in the Catalogue of Security Equipment with documented performance metrics. These frameworks elevate accountability but also compress time-to-market for vendors lacking established compliance pathways.
PW Consulting
Challenge 3: Integration Friction Across Legacy Security Stacks
A standalone detection sensor offers limited strategic value if it cannot communicate seamlessly with access control systems, video management platforms, and automated lockdown protocols. Many organizations still operate fragmented security architectures where alert data arrives too late or in incompatible formats to trigger coordinated responses. The market's next growth frontier lies less in improving standalone detection accuracy and more in reducing integration complexity, standardizing data exchange, and ensuring that detection outputs translate directly into executable emergency procedures.
Key Drivers Accelerating Market Evolution
Technological Innovation and Sensor Fusion
The most consequential shift in this market is the move from single-modality acoustic detection to multi-sensor architectures that combine acoustic, infrared, and energy-based inputs. By cross-validating signals across modalities, systems can isolate ballistic signatures with greater confidence and reduce reliance on post-event manual verification. Machine learning layers are now being embedded directly into sensor firmware, enabling continuous adaptation to localized acoustic profiles rather than depending on static threshold settings. This evolution is particularly visible in recent outdoor detection releases, where multi-mode configurations have demonstrated improved discrimination in open environments with higher ambient noise variability.
Military-grade sensing technology is also migrating into civilian and commercial applications at an accelerating pace. Acoustic and energy-based detection platforms originally designed for battlefield situational awareness are being re-engineered for schools, transit hubs, corporate campuses, and industrial sites. This transfer of capability lowers the performance barrier for high-confidence detection while expanding the addressable use-case portfolio. Vendors that can adapt military-proven architectures to civilian installation constraints—without sacrificing durability, calibration stability, or maintenance efficiency—are capturing disproportionate attention from procurement teams.
Policy and Funding Mechanisms as Growth Accelerators
Regulatory and fiscal environments are actively shaping deployment velocity. Federal funding channels, particularly grants administered through the Bureau of Justice Assistance, have made implementation and evaluation resources available for high-crime areas, reducing the financial friction that historically slowed municipal adoption. These programs do not merely subsidize hardware purchases; they incentivize evidence-based deployment models that require measurable outcomes, thereby rewarding vendors that can supply performance data, audit trails, and post-deployment evaluation frameworks.
At the same time, certification regimes are functioning as market filters. DHS SAFETY Act approval and comparable international standards are effectively separating suppliers that can integrate into government and critical infrastructure procurement pipelines from those confined to ad-hoc or private-sector deals. For manufacturers, compliance is no longer a bureaucratic afterthought; it is a strategic capability that determines contract eligibility, pricing leverage, and long-term contract durability.
Worldwide Audio Sensors Market
Demand-Side Shifts Toward Automated Response and Situational Awareness
End-user expectations have evolved beyond immediate alert generation. Security operators now demand systems that classify threat location, estimate trajectory context, and feed structured data into broader emergency management workflows. This shift is driven by the recognition that detection without coordinated response creates operational gaps. Educational institutions, for example, have prioritized indoor detection solutions engineered specifically to minimize false positives in environments where routine noise—sports events, maintenance work, or student activity—can overwhelm conventional acoustic thresholds. The emphasis has moved toward systems that support institutional response plans rather than simply notifying security personnel after an event has occurred.
Supply Chain and Cost Structure Dynamics
Sensor manufacturing, edge processing hardware, and calibration services are experiencing incremental cost optimization as production scales and component standardization improves. At the same time, the cost of deployment is increasingly tied to integration effort, ongoing maintenance, and data management rather than raw hardware expense. Vendors that bundle detection hardware with integration support, remote calibration tools, and performance monitoring dashboards are positioning themselves to capture recurring revenue streams while reducing the total cost of ownership for buyers. This structural change is nudging the market toward service-oriented commercial models rather than one-time equipment transactions.
Competitive Landscape and Strategic Positioning
The market exhibits moderate to high concentration, with a limited group of established players commanding the majority of revenue share. This concentration reflects the capital intensity of sensor development, the importance of certification track records, and the long validation cycles required to earn trust in public safety and defense procurement environments. Yet the competitive field is not static. Differentiation is increasingly defined by architectural approach, integration readiness, and the ability to demonstrate measurable performance in specific deployment contexts.
Company Positioning and Differentiation
- ACOEM Group has anchored its strategy around acoustic threat detection engineered for critical infrastructure and public safety use cases. Its recent system iterations emphasize high-attribute acoustic intelligence engines capable of single-sensor gunshot identification while improving situational awareness. The company's positioning reflects a focus on precision detection with reduced dependency on multi-node sensor arrays, which can lower installation complexity in certain environments.
- EAGL Technology, Inc. differentiates through energy-based detection combined with adaptive response protocols. Its integration capabilities span access control, video systems, and automated emergency workflows, creating a more closed-loop security architecture. DHS SAFETY Act approval further strengthens its eligibility for U.S. government and critical infrastructure contracts, giving it a clear procurement advantage in regulated channels.
- Hyperion Technology Group, Inc. has built its reputation on infrasound-based detection sensors designed for military, homeland security, and industrial applications. Its field-proven deployments and continued R&D emphasis position it as a specialist in environments where conventional acoustic sensing faces physical or operational limitations.
- QinetiQ has extended its EARS family of gunshot localization systems into both soldier-mounted and military police applications. With thousands of portable units shipped and combat-tested validation, the company leans on operational credibility and scalability in tactical mobility contexts. Its SWATS model illustrates how portable localization can complement fixed infrastructure in layered defense strategies.
- Raytheon Company maintains a strong footprint in vehicle-mounted detection, with continued model upgrades targeting faster threat response and improved battlefield situational awareness. Its positioning reflects the broader trend of adapting mobile detection platforms for both defense operations and high-security mobile units.
- Shooter Detection Systems (SDS) has expanded its portfolio across indoor and outdoor environments, combining acoustic and infrared modalities with machine learning refinement. Its recent outdoor system commercialization and institutional indoor deployments highlight a strategy centered on multi-mode accuracy, false-positive reduction, and recognized performance validation through industry awards and safety certifications.
- SoundThinking, Inc. remains a prominent name in acoustic detection for law enforcement, with wide city-level deployments and an expanded AI engine that emphasizes real-time alert processing. Its scale in municipal deployments provides a strong reference base, though the company continues to navigate the broader market shift toward integrated response ecosystems rather than standalone alerting.
- Safety Dynamics, Inc. maintains a focused presence in public safety and law enforcement applications, reinforcing the market's continued reliance on specialized vendors that understand operational policing and emergency response requirements.
Competitive Evolution: Consolidation, Specialization, and New Entrants
The market is exhibiting a dual trajectory. On one side, established players are deepening integration capabilities, expanding certification coverage, and broadening product lines across indoor, outdoor, fixed, and mobile installation types. On the other, specialization is intensifying as vendors carve out defensible positions in infrasound sensing, energy-based detection, portable military localization, or institution-specific false-positive mitigation. New entrants face a high barrier to credibility, particularly when procurement decisions rely on certification status, deployment track records, and interoperability with existing security stacks. Nevertheless, the ongoing migration of military sensing technology into civilian contexts creates openings for companies that can translate advanced sensing capabilities into practical, compliance-ready commercial solutions. Integration partnerships are also reshaping competitive dynamics, as detection suppliers align with video management, access control, and emergency communications providers to offer more complete response architectures.
Future Trends and Commercial Implications
Trend 1: Multi-Modal Detection as the Baseline Standard
The market is moving toward multi-sensor fusion as a default expectation rather than a premium feature. Systems that rely on a single detection modality will increasingly face scrutiny in environments where environmental noise, structural echo, or weather conditions complicate acoustic-only identification. Commercial opportunity lies in architectures that combine acoustic, infrared, and energy-based inputs with on-device machine learning capable of continuous calibration. Vendors that can demonstrate measurable false-positive reduction across varied deployment settings will command pricing leverage and longer contract tenure.
Trend 2: Response Automation and Cross-Platform Interoperability
Detection is becoming only one layer of a broader automated response chain. The next phase of value creation will come from systems that not only identify and locate threats but also trigger access control lockdowns, redirect camera coverage, notify first responders with structured data packets, and log event timelines for post-incident analysis. Procurement teams are likely to prioritize solutions that minimize integration effort and support open data exchange with existing security infrastructure. This creates commercial upside for vendors that invest in API compatibility, standardized alert formats, and pre-built integration modules for common security platforms.
Trend 3: Funding-Linked Deployment Models and Evidence-Based Procurement
Federal and institutional funding mechanisms will continue to influence deployment patterns, particularly in municipal and high-crime area initiatives. Buyers will increasingly require vendors to support grant-aligned implementation models, including performance evaluation, auditability, and documented outcomes. This trend favors suppliers that can provide deployment analytics, maintenance transparency, and post-installation assessment frameworks. At the same time, certification requirements will remain a gating factor for government and critical infrastructure contracts, reinforcing the strategic importance of compliance readiness.
Risks and Uncertainties
Despite the favorable growth trajectory, several uncertainties warrant attention. Environmental and operational variability will continue to challenge detection accuracy in edge cases, particularly in dense urban or industrial settings where ambient noise profiles shift unpredictably. Regulatory frameworks may tighten or diverge across regions, increasing compliance costs and complicating international expansion. Procurement cycles in public safety and defense can be prolonged, with budget approvals and certification timelines creating revenue timing risk. Additionally, as integration becomes more central to system value, vendors that fail to align with prevailing security architectures may face margin pressure or displacement by bundled solution providers.
Strategic Recommendations for Decision-Makers
For Technology Manufacturers and Solution Providers
- Prioritize multi-modal architectures and on-device machine learning that reduce false positives without requiring excessive sensor density. Calibration stability and environmental adaptability should be treated as core product attributes, not secondary engineering tasks.
- Treat certification and compliance as strategic capabilities. Align product development with DHS SAFETY Act requirements and equivalent international standards early in the design cycle to avoid late-stage procurement disqualification.
- Expand integration readiness. Invest in open data interfaces, pre-built connectors for common video and access control platforms, and clear documentation that reduces deployment friction for procurement teams and system integrators.
For Investors and Strategic Capital Allocators
- Evaluate companies based on recurring revenue potential, integration capability, and certification coverage rather than hardware unit sales alone. The market's value migration is tilting toward solutions that support ongoing performance monitoring, maintenance, and automated response workflows.
- Watch for consolidation signals in the integration layer. Vendors that can bundle detection with emergency protocol automation, data analytics, and compliance reporting are positioned to capture higher contract value and longer customer retention.
- Assess exposure to funding-dependent deployment channels. Municipal and grant-aligned contracts can accelerate volume, but they also introduce procurement timing risk and evaluation requirements that may affect cash flow predictability.
For Procurement Leaders and End-User Organizations
- Define operational requirements around response integration before evaluating detection accuracy in isolation. A system that delivers fast, precise alerts but cannot feed structured data into lockdown, video redirection, or first-responder notification workflows will underdeliver relative to total cost.
- Weight certification status and documented performance metrics heavily in vendor selection. Compliance readiness directly affects contract eligibility, especially for government and critical infrastructure deployments.
- Request deployment-specific false-positive data and environmental profiling support. Vendors that can tailor calibration to site conditions and provide ongoing performance transparency will reduce operational risk over the system lifecycle.
The gunshot detection systems market is expanding on the back of technological convergence, regulatory alignment, and a clear demand shift toward actionable response rather than passive alerting. Yet the winners in this environment will be determined less by headline growth figures and more by the ability to deliver accurate detection, seamless integration, and compliance-ready deployment in real-world conditions. Organizations that need granular segment data, regional deployment patterns, pricing architecture breakdowns, or tailored competitive benchmarking will benefit from access to the full research report, which provides the detailed segmentation, company-level financials, and customized strategic recommendations required to convert market awareness into executable decision-making.
For detailed analysis of this topic, please visit the official page: Gunshot Detection Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


