



Cell Culture Market: Why the 11.2% CAGR and Biopharma Shift Redefine Growth Through 2032

Cell Culture Market — Strategic Trends and Commercial Opportunities (2025–2032)
The cell culture market has moved well past its experimental phase. Between 2020 and 2025, revenue expanded from 16.32 billion to 27.58 billion, reflecting sustained adoption across biomanufacturing, diagnostics, and emerging therapeutic platforms. The trajectory is expected to continue at a compound annual growth rate of 11.2 percent through 2032, with the overall market projected to reach 58.02 billion. The forecast period from 2026 to 2032 will be shaped not by a single breakthrough, but by converging pressures on technical performance, regulatory clarity, supply chain resilience, and application-specific customization. For executives and investors, the central question is no longer whether demand will persist, but how to position for the structural shifts that will separate prepared players from the rest.
Primary Cell Culture Market
Market Snapshot and Core Challenges
From Steady Expansion to More Demanding Performance Standards
Growth in the sector has been consistent, but the nature of that growth is changing. Early expansion relied heavily on broad adoption of standardized media, basic consumables, and established equipment platforms. The next phase is being driven by higher-value, more complex applications that demand reproducible performance, defined formulations, and compatibility with scale-up workflows. This shift places new expectations on suppliers and users alike. A product that performs well in a research setting is no longer sufficient if it cannot maintain consistency in a manufacturing environment or meet the documentation and quality expectations associated with therapeutic development.
A second challenge lies in the gap between innovation and operational readiness. Many promising technologies and culture formats are introduced as proof-of-concept or early capability. Translating those advances into reliable, cost-effective, routine use often requires additional process development, qualified materials, and tightly controlled handling practices. That transition creates friction. It also creates opportunity for organizations that can bridge the divide between early-stage promise and practical deployment.
Cell Culture Media Market
Regulatory and Quality Expectations Are Reshaping Supplier and User Behavior
Regulatory and quality expectations are becoming more explicit across cell-based workflows. In cell and gene therapy development, flexibility in chemistry, manufacturing, and control requirements has been emphasized to accelerate development for smaller patient populations. At the same time, broader expectations for microbial purity, contamination control, and GMP-aligned practices continue to influence how reagents, media, and consumables are specified and handled. In sterile cell culture operations, contamination control has moved from a technical detail to a business-critical concern, because deviations can affect timelines, validation, and confidence in the process.
This creates a more demanding operating environment. Users are not only evaluating performance and price; they are also considering documentation quality, consistency, traceability, and the ability to align with evolving expectations in their specific application area. Suppliers that treat compliance and quality systems as integral to the product—rather than as a separate administrative layer—are better positioned to support customers navigating this environment.
Supply Continuity and Raw Material Variability Are No Longer Peripheral Issues
Another structural challenge is the sensitivity of cell culture performance to raw material consistency and supply continuity. Culture media components and related inputs remain exposed to variability in sourcing, manufacturing, and logistics. Even when individual products are technically sound, variability across lots or interruptions in availability can reduce manufacturing efficiency and increase process risk. In an environment where reproducibility and timeline discipline matter more than ever, these issues can have outsized consequences.
The implication is clear: cost and performance can no longer be considered in isolation from resilience. Buyers want predictable performance, and suppliers need credible strategies to manage variability, secure critical inputs, and reduce dependence on fragile supply pathways. This is especially important as applications become more specialized and substitution options become more limited.
Key Drivers of Market Change
Technical Innovation Is Moving From Niche Capability to Operational Necessity
One of the most important drivers is the rising sophistication of cell culture requirements across applications. Cultivation formats, media designs, and process-supporting reagents are being refined to improve consistency, reduce undefined components, and support scale-up. The emphasis is increasingly on reproducibility and control, particularly where cell-based processes are expected to support therapeutic development, biologics production, or advanced tissue-related applications. Innovation is no longer limited to creating a product that works; it is increasingly about creating a product that can work reliably across multiple users, workflows, and operational conditions.
This matters commercially because technical differentiation is becoming harder to replicate quickly. Where a supplier can offer a stable formulation, defined composition, or application-tailored support, it gains more than a product advantage; it gains a reduction in the user’s risk and development burden. In that sense, innovation is becoming a commercial multiplier, especially when it is paired with practical support for scale-up, documentation, and process integration.
Policy and Regulatory Dynamics Are Accelerating Certain Applications While Raising the Compliance Bar
Policy and regulatory developments are shaping both the pace and the structure of demand. Regulatory flexibility for cell and gene therapies has helped reduce some of the earlier friction associated with development timelines and small patient populations. This flexibility can encourage investment in areas where rapid iteration and tailored process design are important. At the same time, broader quality expectations for biological medicinal products and sterile operations continue to influence purchasing decisions, process design, and supplier selection.
The strategic effect is twofold. First, more permissive or flexible approaches to certain requirements can unlock activity in high-value areas that might otherwise face prolonged development cycles. Second, even as flexibility increases in some respects, quality and contamination control expectations remain substantial. Companies that anticipate these dual pressures—moving faster where allowed, but maintaining discipline where it matters—will be better equipped to convert opportunity into reliable output.
Demand-Side Shifts Are Expanding Beyond Traditional Research Use
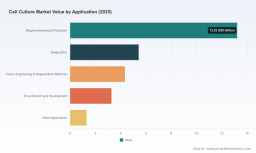
Demand is evolving as end users move from exploratory research toward more applied, production-oriented, and therapy-linked use cases. In biopharmaceutical production, the push toward scalable and reliable manufacturing continues to support demand for consumables and process inputs that can perform consistently at higher volumes. In diagnostics and drug screening, the need for reliable cell-based models contributes to sustained interest in well-characterized reagents and media. In tissue engineering and regenerative medicine, demand is often more specialized, but it is also disproportionately important because it pushes the market toward higher specification products.
This shift in demand is more than a volume story. It changes the value equation. Where use is narrowly research-focused, standardization and price may dominate. Where use moves closer to production or therapeutic application, users increasingly value traceability, defined composition, and support for scale-up and quality expectations. Companies that can align product design and service models with these application-level expectations are more likely to capture and retain demand.
Supply Chain and Cost Structure Pressures Are Reshaping How Products Are Purchased and Managed
Cost structures and supply conditions are increasingly influencing how buyers plan, qualify, and maintain their cell culture inputs. Variability in raw materials and disruption risk in supply chains for culture media components continue to affect manufacturing efficiency. That means procurement decisions are being shaped not only by unit cost, but also by the predictability of supply, the robustness of supplier quality systems, and the ability to manage substitution without compromising process performance.
This environment favors suppliers that can demonstrate breadth of sourcing, controlled manufacturing consistency, and credible continuity planning. It also encourages buyers to think more carefully about qualification lead times, inventory strategy, and multi-supplier risk. In practice, the commercial opportunity lies in reducing uncertainty: for suppliers, by building more resilient and transparent supply propositions; for buyers, by aligning sourcing strategy with process criticality rather than price alone.
Competitive Landscape and Leading Strategies
Window of Differentiation: Specialized Formulations, Application Alignment, and Quality Infrastructure
The market includes a broad set of players spanning media, consumables, equipment, reagents, and specialized application support. Several companies have built strong reputations by emphasizing different parts of the value proposition. Some focus on specialized media formulations, including classical, serum-free, and perfusion-optimized options, alongside custom bioprocessing and cell therapy-related solutions. Others offer broad portfolios that cover mammalian, primary, stem, and three-dimensional culture formats, supported by reagents and transfection tools. A further set of suppliers emphasizes GMP-aligned production sites, animal-component-free options, or custom development of media for specific therapeutic or manufacturing contexts.
The differentiating factor is not simply breadth. Breadth matters, but only when it is connected to a credible technical and quality story in the areas where customers are most sensitive. In this market, the strongest positioning tends to come from combinations of three elements: formulation focus or application specificity, consistency in supply and performance, and the ability to support customers through documentation, customization, or process-aligned service. When those elements are aligned, a supplier can compete on more than price and still retain customers as applications become more demanding.
Recent Activity Reflects the Same Strategic Focus
Recent developments illustrate how companies are trying to strengthen the links between products, applications, and operational reliability. In 2026, one major player launched a commercial platform combining research-use stromal cells with cell culture media, an example of pairing biological material with supporting media to simplify workflow integration. The same company also entered a collaboration focused on advancing adeno-associated virus production enhancers, signaling demand-side interest in process-supporting technologies for viral vector applications. In parallel, a major catalog release in early 2026 highlighted updated cell culture solutions alongside sustainability certifications, pointing to the growing relevance of product updates and externally visible responsibility claims. Another important move came from a company entering GMP-related custom cell culture media services for biomanufacturing, expanding its footprint into more production-oriented, specification-sensitive work.
These moves are not isolated. Together, they suggest a market where companies are investing in combinations of capabilities rather than single-product advantages. The most telling pattern is the increasing emphasis on integration: linking materials, workflows, and service support in ways that reduce friction for users who need consistency, documentation, and application readiness.
Concentration, Consolidation, and the Room for New Entrants
The market remains moderately concentrated, with the top three firms accounting for over half of revenue and the top five approaching nearly seven-tenths. That level of concentration indicates that scale, portfolio breadth, and established customer relationships provide meaningful advantages, especially in higher-volume and more specification-intensive segments. It also suggests that new entrants cannot rely on generic product offerings to break in easily. Differentiation usually needs to be sharper, whether through formulation specialization, target application depth, custom service capability, or quality and compliance readiness.
At the same time, the environment still leaves space for focused players. In areas such as xeno-free, serum-free, chemically defined, or custom media for primary and stem cell cultures, specialized competence can still build durable demand. In biomanufacturing and gene therapy-adjacent workflows, suppliers that can provide GMP-grade options, scalable support, or tailored reagents may find strong positioning even in a concentrated market. The broader trend, therefore, is not simply consolidation. It is selective consolidation, where scale advantages matter in some parts of the market while specialization and application depth continue to matter in others.
PW Consulting Health Care Research Center
Outlook for the Next Three to Five Years
Trend 1: Specification Depth Will Become a Standard Purchasing Criterion, Not a Premium Add-On
Over the next few years, well-defined formulations, documented consistency, and application-relevant performance are likely to become more routine expectations rather than niche differentiators. As cell-based workflows become more production-oriented and more closely connected to therapeutic or quality-sensitive use cases, users will increasingly compare materials on criteria beyond basic performance and price. Suppliers that continue to treat documentation, defined composition, and consistent manufacturing as core features rather than optional support will be better positioned to win and retain business.
The commercial opportunity here lies in making specification depth usable for the buyer. That means not only offering higher-specification products, but also reducing the effort required to qualify them, integrate them into workflows, and justify them internally. In practice, the winning position may combine product quality with practical implementation support.
Trend 2: Process-Adjacent Solutions Will Matter More Than Standalone Products
A second likely trend is the growing importance of solutions that help users move from product selection to process reliability. This includes media and reagent portfolios designed for scale-up, workflow-oriented combinations of materials, and service models that support custom needs in biomanufacturing or specialized cell culture applications. The direction is toward reducing the number of disconnected decisions a buyer must make. Where a supplier can help connect materials with process goals, it can become more embedded in the user’s operation.
For companies, this suggests that the next competitive battles will be fought not only on product specifications, but also on integration, service, and the ability to support higher-stakes use cases. For buyers, the opportunity is to work with suppliers that can reduce process risk rather than merely supply components.
Trend 3: Regional Demand Journeys Will Diverge as Local Ecosystems Mature
Market growth will not unfold uniformly across regions. Some regions will continue to be anchored by established biopharmaceutical and life-science infrastructure, while others will increasingly reflect emerging manufacturing capacity, expanding research activity, and local efforts to build greater self-sufficiency in critical inputs. Over time, this can create different demand rhythms: one region may emphasize advanced applications and premium specification products, while another may prioritize access, cost efficiency, and gradual capability building.
The strategic implication is that regional strategy should be tailored rather than transplanted. A product, service, or quality proposition that works in one market may need adjustment in another to match local maturity, procurement habits, and regulatory context. Companies that recognize these differences early can avoid the common mistake of treating the market as a single homogeneous opportunity.
Risk and Uncertainty to Watch
Several sources of uncertainty remain. Regulatory guidance can continue to evolve, and even flexibility-oriented changes may be accompanied by stricter expectations in specific areas, especially around contamination control and material quality. Supply chain variability and raw material inconsistency can still interrupt manufacturing efficiency, particularly when critical components are concentrated in fragile sourcing pathways. There is also the risk that promising technologies or specialized applications may not scale commercially as quickly as anticipated, which would affect the pace at which high-specification demand converts into broad revenue.
These uncertainties do not negate the growth outlook, but they do argue for scenario-aware planning. Companies that prepare for multiple possible paths—flexible demand patterns, evolving compliance expectations, and intermittent supply disruption—are better placed to respond without overcommitting to a single assumption.
Strategic Actions for Decision Makers
For manufacturing and supplier organizations, the priority is to align product and service strategy with the areas where customers are likely to value consistency, documentation, and application fit most highly. That can mean deepening specialization in defined or animal-component-free formulations, strengthening GMP-aligned production capabilities where relevant, or building clearer support for scale-up and customization. Where a company already has a strong portfolio, the next question is whether its commercial model helps customers reduce process risk or simply adds another product option. The former is more durable than the latter in a market that is becoming more specification-sensitive.
For investors and corporate development teams, the key is to distinguish between market growth and value capture. Revenue expansion is broad, but not every segment or company will capture value equally. Attention should be directed toward suppliers with credible differentiation in high-specification applications, strong quality and continuity capabilities, and a history of moving products into more demanding use cases. Equally important is assessing whether a company’s growth depends on genuinely durable advantages or on temporary pricing and volume conditions.
For procurement and operations leaders, the strategic move is to broaden the evaluation framework. Price and basic performance still matter, but so do lot consistency, documentation quality, qualification effort, and supply continuity. In practice, that means mapping inputs to process criticality, prioritizing resilience where disruption risk is material, and avoiding over-reliance on single sources for components that can affect process reliability. A more deliberate procurement posture can reduce downstream risk and improve long-term operational stability.
The market’s trajectory through 2032 will likely reward organizations that prepare for a more demanding, more application-specific, and more integrated operating environment. The companies and buyers that benefit most will be those that treat cell culture inputs not as interchangeable consumables, but as part of a broader system of performance, quality, and continuity. For readers interested in a more detailed breakdown of segments, regional dynamics, and competitive positioning, the full PW Consulting report provides deeper data and customized guidance for applying these insights to specific strategic decisions.
For detailed analysis of this topic, please visit the official page: Cell Culture Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


