



Capecitabine Market Value Hits $494M in 2025: Decoding the 6.01% CAGR Growth Path to 2032

The Capecitabine Market at an Inflection Point: Strategic Trends and Commercial Opportunities
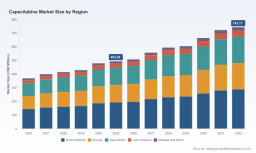
The capecitabine market has matured from a niche oncology therapy into a widely deployed oral chemotherapy option with established clinical pathways, global distribution footprints, and a pricing landscape shaped by generics competition and brand stewardship. Recent market data underscore a steady, compounding growth trajectory: global revenue climbed from roughly 369 million in 2020 to 494 million in 2025, with the market projected to expand from about 508 million in 2026 to more than 743 million by 2032, reflecting a compound annual growth rate near 6.0 percent. This pace signals durable demand, but it also masks structural shifts underway across regulatory requirements, product innovation, supply chain resilience, and competitive positioning. For executives and investors, the challenge is no longer whether capecitabine will grow—it is how each stakeholder can navigate a landscape where volume expansion, risk management, and differentiation increasingly determine commercial outcomes.
Understanding the market today requires looking beyond top-line growth to the forces reshaping how capecitabine is prescribed, manufactured, distributed, and reimbursed. The category sits at the intersection of oncology care delivery, regulatory modernization, and generic supply dynamics. That combination creates both opportunity and fragility. Growth is being driven by broad utilization across multiple tumor types and care settings, yet the same breadth makes the market sensitive to therapy substitutions, formulary decisions, and manufacturing disruptions. In the sections that follow, the focus is on what matters most for strategic planning: the core challenges framing the market, the drivers altering pace and margin, the competitive profiles shaping access, the trends likely to unfold over the next three to five years, and the actions different stakeholders can take now.
Market Context and Core Challenges
The capecitabine market has demonstrated consistent expansion, with annual revenues moving from the high 360-million range in 2020 to just under 500 million by 2025 and continuing upward through the forecast horizon. Growth is broad-based, with significant shares concentrated across major oncology indications and distributed through both hospital and retail/online pharmacy channels. Regionally, North America and Asia Pacific represent substantial portions of total value, alongside meaningful European demand and smaller but notable contributions from Latin America and the Middle East and Africa. The competitive structure remains relatively fragmented, with top three players holding roughly 26 percent of market value and the top five near 29 percent, indicating that no single manufacturer dominates the category outright. This environment supports multiple commercial models—branded stewardship, generic scale, and specialty distribution—but also raises questions about pricing discipline, supply reliability, and how brand differentiation will compete as more players enter the space.
Several challenges define the current inflection point. First, the regulatory baseline is tightening around patient safety and treatment personalization. Updated prescribing information and safety labeling have begun to reshape treatment protocols, placing greater emphasis on pre-treatment screening for enzyme deficiencies that affect drug metabolism. These requirements are clinically rational, but they introduce operational complexity for providers, pharmacy networks, and manufacturers who must ensure adherence across varied care settings. Second, supply chain reliability has emerged as a recurring risk. Even for a well-established oral oncology product, demand spikes and manufacturing or logistics disruptions can lead to shortages, as seen in recent episodes affecting specific branded and generic presentations. In a market where continuity of care is paramount, shortages not only create clinical inconvenience but can also shift purchasing behavior and erode trust in supply commitments. Third, the competitive landscape is evolving through both consolidation and fragmentation. Brand rights and distribution agreements have changed hands, while multiple generic manufacturers continue to build volume across regions. The result is a market where access, pricing, and channel relationships matter as much as product formulation.
Key Drivers Shaping the Capecitabine Market
Innovation and Next-Generation Formulations
Product innovation is one of the more consequential drivers in the mid-term outlook. While capecitabine is a long-established agent, a next-generation formulation has entered clinical evaluation with the aim of improving exposure to the active metabolite and refining the safety profile relative to standard monotherapy. Early-phase data have drawn attention because they suggest the possibility of enhanced efficacy or tolerability without abandoning the core therapy paradigm. If later-stage trials confirm these signals, the impact could extend beyond a single product: improved formulations may influence prescribing preferences in oncology settings, support combination strategies, and create a basis for differentiation that is not solely dependent on price. Even where new formulations do not replace existing options, the clinical conversation around optimization can shift expectations and encourage manufacturers to invest in value-added positioning.
Regulatory Modernization and Testing Requirements
Regulation is increasingly a structuring force rather than a compliance afterthought. Recent regulatory actions have included label updates that revise indications, dosage regimens, and safety information, including considerations around dihydropyrimidine dehydrogenase deficiency. In parallel, guidance has moved toward making genetic testing a prerequisite before treatment initiation in relevant contexts. This shift aligns with broader oncology trends emphasizing precision prescribing and risk mitigation, but it also affects workflows and procurement. Providers must integrate testing into care pathways, pharmacies must manage counseling and documentation, and manufacturers need to ensure that product information and support materials reflect new expectations. Where regulatory updates are clear and consistent, they can reduce uncertainty and support adoption; where they vary by region, they create fragmentation that complicates global planning.
PW Consulting
Demand-Side Shifts in Oncology Care Delivery
Demand is being shaped by how cancer care is delivered and accessed. Capecitabine remains attractive in part because of its oral administration, which supports flexible treatment models and can reduce the burden of frequent clinic visits for eligible patients. As oncology services expand in outpatient and community-based settings, oral therapies with established efficacy profiles continue to find use across colorectal, breast, gastric, pancreatic, and other indications. At the same time, payer and formulary dynamics influence which versions are accessed and at what price. Hospitals and retail/online pharmacies both play substantial roles in distribution, meaning that channel strategy and contracting are as important as clinical fit. The net effect is a demand environment that is resilient but sensitive to reimbursement policy, site-of-care preferences, and the availability of reliable supply at the point of care.
Supply Chain, Cost Structure, and Access Reliability
Cost structure and supply reliability are recurring drivers of commercial performance in generic-heavy oncology categories. Manufacturing scale, quality control, logistics, and regional sourcing decisions all influence margin and availability. Episodes of unexpected demand and interruption have demonstrated that even mature products can face shortage risk when supply planning does not keep pace with utilization or when distribution channels encounter disruption. For buyers, this creates a need to diversify sources, monitor inventory buffers, and assess supplier robustness beyond price alone. For manufacturers, it underscores the value of predictable production, responsive distribution, and clear communication during constraints. In market segments where multiple suppliers compete, the ability to maintain continuity can be a more durable advantage than temporary price positioning.
Competitive Landscape and Leading Strategies
Branded Stewardship and Rights Transitions
A defining feature of the competitive landscape is the interaction between branded product stewardship and the broader generic ecosystem. One originator and marketer continues to anchor the branded position for capecitabine tablets in colorectal and breast cancer treatment, maintaining clinical familiarity and long-standing provider relationships. At the same time, another major pharmaceutical company acquired worldwide rights to the branded product in 2023 and now markets it across key regions, including China and Japan. This transition illustrates how brand ownership can shift while still preserving access to a recognized product identity in important markets. For incumbents and new rights holders alike, the strategic priority is to manage formulation consistency, provider education, and region-specific compliance while defending the clinical value proposition against generic substitution where appropriate.
Generic Scale, Distribution Partnerships, and Regional Reach
On the generic side, several manufacturers have built profiles based on tablet production and channel partnerships. Indian-based producers supply U.S. and international markets through arrangements with distributors and pharmaceutical services companies, extending reach across retail and hospital channels. Another group of manufacturers markets generic tablets through established U.S. pharmaceutical partners, while additional producers distribute through other major service networks. Outside the United States, branded and generic positions coexist, with manufacturers in Australia and other regions producing and marketing their own presentations. The pattern suggests that competitive advantage in generic segments depends on three things: reliable manufacturing capacity, efficient distribution agreements, and the ability to meet regional requirements without sacrificing consistency. Companies that can align supply with channel needs and regulatory expectations are better positioned to capture volume when shortages or demand shifts occur.
Competitive Evolution: Consolidation, Differentiation, and Entry Dynamics
The market structure is not static. The concentration metrics indicate a moderately fragmented landscape, leaving room for both consolidation and new entry. Rights acquisitions have already altered the branded side, and similar moves could continue as companies seek to strengthen oncology franchises or acquire established product identities. On the generic side, entry is facilitated by manufacturing capability and distribution relationships, but sustainable positioning increasingly depends on more than low price. Differentiation can come from continuity of supply, consistent quality, responsive customer support, and alignment with testing and safety requirements. Over time, the competitive field is likely to separate into tiers: players with strong regional relationships and dependable supply, and those that remain more vulnerable to channel and regulatory shocks. For decision-makers, the implication is to look beyond brand names and short-term pricing to assess whether a supplier can be relied upon across cycles of demand and disruption.
Forward Outlook: Three to Five-Year Trends
Tighter Integration of Safety, Testing, and Prescribing Workflows
As regulatory expectations around genetic screening and safety information become more embedded, the market is likely to move toward greater integration of testing and prescribing workflows. This trend will affect hospitals, pharmacies, and manufacturers in different ways. Providers will need streamlined processes to confirm eligibility and manage exceptions. Manufacturers and service partners may invest in educational materials, decision support, and communication that reduce friction in implementation. For commercial strategies, the opportunity is not simply compliance; it is the chance to position products and services as easier to use safely and consistently. Suppliers that help institutions manage the operational burden of testing and counseling can strengthen relationships and reduce the likelihood of adoption barriers. The risk is that uneven implementation across regions or institutions creates confusion or slows utilization, particularly where guidance is not fully harmonized.
Formulation and Clinical Optimization as a Differentiator
Clinical optimization is set to become a more visible battleground. If next-generation formulations continue to demonstrate improved exposure and safety signals in later trials, they could influence prescribing in gastrointestinal and other advanced cancers, especially where clinicians are balancing efficacy with tolerability. Even before any new formulation achieves broad adoption, the direction of travel matters: the category is increasingly framed by the question of how to deliver the therapeutic benefit of capecitabine with a better patient experience or a more favorable risk profile. For manufacturers, this opens a pathway to differentiation based on clinical value rather than price alone. For investors, it suggests that early-stage programs with clear mechanistic rationale and well-designed trials may carry strategic optionality, though development risk remains substantial and outcomes are uncertain until pivotal data are available.
Oxaliplatin Market
Supply Resilience as a Commercial Moat
Supply resilience is expected to play a larger role in competitive advantage. Repeated interruptions in specific branded and generic presentations have highlighted that availability can be as decisive as price in oncology procurement. The practical consequence is that procurement teams and hospital networks will increasingly evaluate suppliers on continuity, lead-time reliability, and the ability to manage regional demand fluctuations. For manufacturers, this means that robust production planning, quality systems, and logistics responsiveness will be central to commercial performance. Markets in which demand grows steadily but supply remains vulnerable will reward suppliers that can demonstrate dependable access. The downside risk is that shortage events or quality concerns in specific lots or regions can quickly shift purchasing and reputation, making resilience a strategic necessity rather than an operational detail.
Strategic Actions for Decision-Makers
For Manufacturers and Brand Holders
Manufacturers should treat supply continuity and regulatory readiness as core commercial assets, not back-office functions. That means investing in production reliability, clear lot traceability, and proactive communication during constraints, as well as ensuring that labeling, safety information, and support materials reflect current guidance. Where branded products are involved, stewardship should emphasize clinical consistency, provider education, and region-specific compliance, especially in markets where rights have changed hands. Where generic positions are the focus, competitive advantage will likely come from dependable access, efficient distribution partnerships, and the ability to meet local requirements without sacrificing quality. Companies should also monitor formulation innovation closely, since even partial clinical gains can reshape expectations in the category and create new positioning opportunities.
For Investors and Strategic Planners
Investors should evaluate capecitabine exposure with an emphasis on resilience, channel strength, and regulatory alignment rather than volume growth alone. Growth is likely to continue at a steady pace, but the composition of value will increasingly favor participants that can manage safety requirements, maintain availability, and navigate regional differences. In due diligence, it is worth examining supplier robustness, distribution relationships, and exposure to shortage or quality risk, as well as any pipeline programs that could affect long-term positioning. Close attention to label updates, testing requirements, and regional regulatory variation will help anticipate shifts in demand patterns and procurement behavior. The commercial upside is real, but it is best captured by those who can distinguish durable structural advantages from short-term pricing dynamics.
Worldwide Azacitidine Market
For Procurement, Hospitals, and Pharmacy Networks
Procurement and clinical operations teams should prioritize diversified sourcing and contingency planning for oral oncology products, even where the category is mature. This includes maintaining visibility into multiple suppliers, understanding buffer strategies, and ensuring that testing and safety workflows are aligned with current prescribing expectations. Contracts and service-level expectations should reflect the importance of continuity, with attention to lead times, substitution rules, and communication protocols in the event of disruption. Where possible, institutions can benefit from working with partners that offer clear quality systems, responsive support, and consistent availability. As regulatory and clinical expectations evolve, procurement strategies that incorporate both clinical reliability and supply resilience will be better positioned to sustain patient access without unnecessary cost or interruption.
The capecitabine market is moving through a phase where growth and complexity are advancing together. Demand remains broad, the category spans multiple care settings and indications, and the competitive field includes both established branded stewardship and a vigorous generic ecosystem. At the same time, regulatory modernization, supply fragility, and clinical innovation are reshaping how value is created and captured. For executives, investors, and procurement leaders, the most useful question is not whether the market will expand, but which capabilities will determine who gains share, who protects margins, and who maintains uninterrupted access. Detailed segmentation, regional patterns, supplier profiles, and scenario analysis are available in the full PW Consulting research report, which provides the deeper data and customized guidance needed to translate these trends into specific commercial decisions.
For detailed analysis of this topic, please visit the official page: Capecitabine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


