



Dairy Packaging Market 2026: Why 4.89% CAGR and Plastic Dominance Reshape the Industry

Dairy Packaging Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
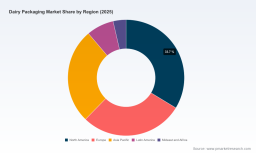
The global dairy packaging market has demonstrated steady expansion over the past half-decade, moving from approximately USD 18.48 billion in 2020 to an estimated USD 23.68 billion in 2025. This growth trajectory reflects a compound annual growth rate of 4.89 percent across the historical period, with the market projected to reach USD 33.17 billion by 2032. The expansion is not uniform across geographies or material categories, but rather reflects a complex interplay of regional demand patterns, material preferences, and packaging format adoption. North America and Europe continue to represent the largest revenue pools, while Asia Pacific has emerged as a highly dynamic growth region, driven by rising dairy consumption, developing cold-chain infrastructure, and shifting retail formats.
Despite the positive top-line momentum, the sector is confronting several structural challenges that are reshaping competitive dynamics. First, regulatory pressure around recycled content and packaging waste is accelerating across multiple jurisdictions, forcing manufacturers to redesign portfolios ahead of compliance deadlines. Second, input cost volatility and raw material availability are compressing margins, particularly for plastic-based solutions where resin pricing and circular feedstock access remain uneven. Third, the market is experiencing a functional divergence between traditional aseptic and ambient-stable formats versus fresh and chilled dairy packaging, each requiring distinct material performance, barrier properties, and supply chain capabilities. These overlapping pressures mean that scale alone is no longer a sufficient competitive moat; packaging suppliers must simultaneously manage sustainability compliance, line-speed compatibility, and regional demand nuances.
A further complication lies in market concentration. The top three participants account for roughly 28.5 percent of total market value, while the top five hold approximately 35.2 percent. This fragmentation suggests that while leading suppliers command meaningful share, a substantial portion of revenue is distributed across regional specialists, material providers, and niche format manufacturers. For procurement leaders and investors, this concentration profile signals both competitive optionality and the need for careful supplier evaluation, as performance differences in barrier technology, recyclability, and regional compliance readiness can materially affect total cost of ownership.
Key Demand Drivers
Technology Innovation and Barrier Performance
Material and format innovation remains one of the most consequential drivers of market evolution. Suppliers are increasingly engineering cartons, films, and rigid containers that reduce or eliminate aluminum barriers, integrate higher recycled content, and maintain aseptic or high-barrier performance for sensitive dairy products. Recent commercial deployments illustrate this direction: SIG Combibloc introduced an alu-free aseptic carton system for milk in Slovenia, combining a full-barrier design with reduced material complexity. In parallel, paper-based barrier cartons have been extended to high-speed production lines, with early deployment in Asia for soy milk applications. These developments reflect a broader industry shift toward formats that balance shelf-life requirements with recyclability and material simplification. For dairy processors, the practical implication is a widening set of packaging options that can align with sustainability targets without sacrificing operational efficiency, provided that line compatibility and sealing performance are validated early in the qualification process.
Innovation is also visible in flexible and rigid plastic solutions. High-performance butter wraps and specialized film structures have expanded the functional envelope for dairy subsegments that require moisture, oxygen, and aroma barriers under chilled or ambient conditions. At the resin level, polymer suppliers are increasingly emphasizing recycled and bio-attributed grades for dairy cups, trays, and films, responding to both regulatory mandates and brand-owner commitments. The strategic takeaway is that packaging performance is no longer defined solely by barrier integrity or fill-speed compatibility; it now encompasses material provenance, end-of-life pathways, and compliance with emerging recycled-content thresholds.
Policy and Regulatory Environment
Regulatory momentum is a defining driver of packaging decisions in the dairy sector. In the United States, Washington State has established a stepped recycled-content requirement for plastic dairy milk containers, beginning at 15 percent post-consumer recycled content in 2028, rising to 25 percent by 2031, and reaching 50 percent by 2036. California's SB 54, which entered into force in May 2026, imposes minimum recycled content requirements on single-use dairy packaging and reinforces producer responsibility obligations. At the same time, seven U.S. states have implemented Extended Producer Responsibility programs that include specific mandates tied to dairy containers, adding operational complexity for multi-state processors and packagers.
In Europe, the Packaging and Packaging Waste Regulation entered into force in February 2025, with general application beginning in August 2026, and sets minimum recycled content targets for plastic packaging from 2030 onward. These regulatory layers are not isolated administrative requirements; they are reshaping sourcing strategies, material selection, and supplier qualification criteria. Dairy brands operating across regions must now navigate a patchwork of deadlines, recycled-content thresholds, and reporting obligations. For packaging suppliers, the opportunity lies in offering materials and formats that are pre-aligned with these requirements, reducing the compliance burden for dairy customers while creating defensible differentiation in regulated markets.
Consumer and Buyer Behavior
Demand-side changes are reinforcing the sustainability and functionality agenda. Retailers and foodservice operators are increasingly specifying packaging that supports recycled-content claims, reduces material complexity, and aligns with broader corporate sustainability commitments. Consumers, in turn, are responding favorably to packaging that communicates responsible sourcing and recyclability, particularly in categories such as fluid milk, yogurt, and plant-based dairy alternatives where brand positioning often hinges on health and environmental attributes. This behavior does not automatically translate into premium pricing, but it does influence shelf allocation, private-label specifications, and tender criteria, especially among large retail chains and regional distributors.
Worldwide Dairy Logistics Market
At the same time, dairy consumption patterns are diversifying. Fresh and chilled categories continue to grow in many markets, while ambient and shelf-stable formats remain important for distribution efficiency and export reach. Plant-based dairy alternatives are also expanding the addressable market for cartons, pouches, and bottles designed for liquid foods with varying viscosity and acidity profiles. The combined effect is a more segmented demand environment in which packaging suppliers must demonstrate flexibility across formats, line speeds, and application requirements rather than relying on a single standardized solution.
Supply Chain and Cost Structure
Cost structure and supply chain resilience are increasingly central to packaging strategy. Resin availability, recycled feedstock supply, and energy inputs all influence the economics of dairy packaging, and regional disparities in circular infrastructure can create uneven access to compliant materials. Suppliers with integrated film extrusion, resin production, or regional conversion capacity are better positioned to manage these variables, but even they must contend with line-speed requirements, changeover efficiency, and qualification timelines when introducing new materials or barrier designs. For dairy processors, the cost conversation is shifting from unit price toward total cost of ownership, including compliance risk, line performance, spoilage reduction, and downstream recyclability. This reframing favors suppliers that can provide documented material provenance, consistent quality across batches, and clear roadmaps for meeting future recycled-content thresholds.
PW Consulting
Competitive Landscape and Leading Strategies
The competitive field is anchored by a mix of global packaging systems providers, flexible and rigid material specialists, and resin suppliers that enable downstream packaging performance. Tetra Pak and SIG Combibloc remain prominent in aseptic carton and pouch systems for liquid dairy, with positioning that emphasizes barrier performance, line compatibility, and increasingly, material reduction and recycled-content roadmaps. Elopak focuses on gable-top cartons for dairy, juice, and plant-based beverages, with recent expansion into U.S. production capacity for sustainable carton formats. Amcor and Berry Global bring broad flexible-film and rigid-plastic capabilities, respectively, with product portfolios that span dairy films, bottles, tubs, and closures. Huhtamaki contributes paperboard cartons and plastic trays for dairy applications, while Winpak and ProAmpac emphasize flexible pouches, films, and high-performance wraps for fluid dairy and cheese products. Alfipa specializes in PET bottles and closures for dairy and yogurt, and INEOS Styrolution supplies recycled and bio-attributed polystyrene for dairy cups and trays, including recent sour cream cup launches with recycled content for German retail.
The strategic differentiation among these players is less about presence in every category and more about depth in specific performance niches. Leading carton and aseptic system providers are investing in aluminum-free and paper-based barrier options that can be deployed on high-speed lines, reducing material complexity while preserving shelf-life performance. Flexible packaging specialists are expanding high-barrier film structures and butter wraps that address moisture, oxygen, and aroma challenges with narrower material footprints. Resin suppliers are positioning recycled and bio-attributed grades as enablers for compliance and brand claims, effectively embedding themselves earlier in the value chain. This pattern suggests a market in which value is increasingly captured by suppliers that can combine technical reliability, documented sustainability attributes, and regional compliance readiness.
Luxury Packaging Market
Market evolution is likely to feature both consolidation and differentiation. Larger multi-material suppliers may pursue bolt-on capabilities that broaden their format coverage or strengthen regional production footprints, while regional specialists can thrive by serving localized compliance requirements, specific dairy subsegments, or niche format needs. New entrants and niche players may find opportunity in recycled-content resins, mono-material designs, and format simplification, particularly where regulatory deadlines create near-term demand for compliant alternatives. For procurement teams, the practical implication is to evaluate suppliers not only on current pricing and capacity, but also on their ability to meet upcoming recycled-content mandates, support line-speed requirements, and provide transparent material documentation across regions.
Future Trends and Commercial Opportunities
Over the next three to five years, one of the most consequential trends will be the mainstreaming of reduced-material and aluminum-free barrier formats for dairy packaging. As high-speed line compatibility improves and commercial deployments expand beyond early adopters, these formats can become viable options for a broader set of fluid milk and liquid dairy applications. The commercial opportunity lies in offering processors a path to simplify material streams, improve recyclability perception, and align with retailer and regulatory expectations without sacrificing operational performance. Suppliers that can demonstrate reliable sealing, barrier durability, and compatibility with existing or upgraded filling lines will be well positioned to capture demand during this transition.
A second trend is the accelerating alignment of packaging portfolios with recycled-content mandates and Extended Producer Responsibility obligations. As deadlines approach in the United States and Europe, dairy brands and packagers will increasingly prioritize materials with documented recycled content, traceable sourcing, and clear compliance roadmaps. This creates opportunities for resin producers, film extruders, and converters that can supply consistent recycled or bio-attributed grades at scale, as well as for packaging systems providers that can integrate these materials into certified formats. The related risk is supply concentration: recycled feedstocks and compliant resins may remain constrained in certain regions, leading to price volatility or qualification bottlenecks if demand surges ahead of infrastructure build-out.
A third trend is the continued segmentation of dairy packaging by consumption channel and product type. Fresh and chilled categories will place greater emphasis on cold-chain compatibility, moisture resistance, and convenience features, while ambient and export-oriented products will continue to value aseptic stability, light protection, and extended shelf life. Plant-based dairy and hybrid beverages will further expand demand for cartons, pouches, and bottles designed for varied rheology and acidity. The commercial opportunity here is format specialization: suppliers that can tailor barrier properties, opening systems, and fill-speed performance to specific subcategories can command stronger positioning than those offering generic solutions. The uncertainty is that channel growth may diverge by region, and regulatory or retail specifications may shift faster than packaging qualification cycles, requiring suppliers and processors to maintain agile development pipelines.
Underlying these trends is the persistent challenge of balancing performance, cost, and compliance. Innovations that reduce material complexity or increase recycled content must still meet barrier, hygiene, and line-speed requirements. Regulatory progress may accelerate demand for compliant materials, but uneven regional infrastructure can create short-term constraints. Consumer and retailer preferences may favor sustainability claims, yet price sensitivity in private-label and commodity dairy segments can limit willingness to pay. Navigating this environment will require disciplined portfolio planning, early supplier engagement, and a clear understanding of which packaging attributes truly influence commercial outcomes in each market.
Strategic Recommendations for Decision Makers
For dairy manufacturers and brand owners, the priority is to align packaging strategy with near-term regulatory deadlines and long-term material goals without disrupting line performance. This means qualifying reduced-barrier, aluminum-free, and higher-recycled-content options early, validating compatibility with existing filling lines, and mapping compliance requirements across the regions where products are sold. Procurement teams should request documented material provenance, recycled-content consistency, and clear roadmaps for meeting future thresholds, treating these attributes as part of total cost of ownership rather than optional enhancements. Where possible, companies should prioritize suppliers that can support multiple formats or provide transitional solutions that bridge current performance needs and future compliance targets.
For packaging manufacturers and material suppliers, the strategic opportunity lies in building defensible differentiation through technical reliability and compliance readiness. Investing in high-speed line compatibility for sustainable formats, expanding recycled and bio-attributed material options, and strengthening regional production or qualification capabilities can create meaningful advantage in a fragmented market. Suppliers should also consider how to communicate performance and compliance clearly to dairy customers, since documentation, repeatability, and transition support are increasingly decisive in tender evaluations. In a market where the top five participants account for just over a third of total value, focused strength in a specific format, material, or region can be a durable positioning strategy.
For investors and strategic planners, the market presents a profile of steady growth with selective pockets of faster value creation. Revenue is expanding at a mid-single-digit pace, but the most attractive opportunities are concentrated in sustainable barrier innovation, recycled-content supply chains, and format specialization aligned with regulatory and retail demand. Due diligence should therefore focus on a supplier's ability to meet upcoming mandates, its exposure to regional compliance risk, its line-speed and barrier performance track record, and its access to compliant feedstocks. Portfolio exposure should be evaluated not only by current revenue share, but by the company's positioning relative to the regulatory and technology shifts that will shape purchase decisions through 2032. For decision makers seeking deeper segmentation data, regional breakdowns, and tailored scenario planning, the full PW Consulting dairy packaging research report provides the detailed granularity needed to translate these trends into precise commercial actions.
For detailed analysis of this topic, please visit the official page: Dairy Packaging Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


