



Daylight Fluorescent Pigments Market: Why 8.2% CAGR Through 2032 Changes Everything

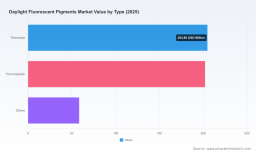
Daylight Fluorescent Pigments Market: Strategic Trends and Commercial Opportunities (2026–2032)
The daylight fluorescent pigments sector has evolved from a specialized color additive into a strategic material class influencing product visibility, brand differentiation, and functional performance across multiple end-use industries. With the total market revenue projected to expand from approximately $465.4 million in 2025 toward $787.5 million by 2032, the segment is on track for a compound annual growth rate of 8.2% over the forecast window. This trajectory reflects more than a simple recovery from prior volatility. It signals a structural shift in how manufacturers, formulators, and product designers approach color engineering, safety signaling, and sustainable material selection.
The market’s recent expansion has been robust but uneven. Revenue moved from $356.11 million in 2020 to $388.01 million in 2022, then accelerated to $422.73 million in 2023 and $429.05 million in 2024. The step-up to $465.4 million in 2025 marks a continued inflection rather than a one-time rebound, with forward estimates reaching $515.12 million in 2026 and $580.19 million in 2028. By 2030, the market is expected to cross the $679.74 million threshold, and the pace of growth suggests sustained upward momentum through 2032. This pattern underlines a market that is gaining commercial relevance in parallel with tighter regulatory expectations and rising performance demands from end customers.
A defining feature of the current landscape is the balance between established scale and technical specialization. Market concentration metrics show that the top three participants command roughly 52% of revenue, while the top five account for about 58%. This indicates a moderately consolidated structure with meaningful room for differentiated mid-tier players, regional specialists, and application-focused innovators. The segment is not yet dominated by a single technology pathway or formulation philosophy. Instead, it is being shaped by competing priorities: color intensity, durability, regulatory compliance, carrier chemistry, and total cost of ownership.
Understanding this market now requires more than tracking shipment volumes or color trends. It requires reading the intersection of chemistry, regulation, application engineering, and procurement behavior. The companies that succeed in the next cycle will be those that can convert performance requirements and compliance pressures into defensible product platforms, not just incremental color variations.
Market Status and Core Challenges
The daylight fluorescent pigments market is moving through a period in which growth is increasingly tied to formulation quality and regulatory readiness rather than raw capacity expansion. Historically, many buyers treated fluorescent pigments as a relatively interchangeable aesthetic input. That assumption is eroding. Buyers in coatings, plastics, inks, and specialty applications are asking for stronger colorfastness, better dispersion behavior, improved stability under heat and light exposure, and formulation compatibility with waterborne or low-emission systems. These expectations are changing the commercial value proposition across the supply chain.
One core challenge is the pressure to reformulate legacy chemistries. Regulatory scrutiny around certain azo-based structures and volatile organic compound profiles is narrowing the acceptable formulation space, particularly in European and North American markets. The result is not simply a compliance exercise. It is a broader redesign effort that touches raw material selection, resin carriers, pigment surface treatment, and downstream application performance. Suppliers that depend heavily on older chemistry pathways face the dual burden of technical redevelopment and customer qualification cycles.
A second challenge is cost volatility embedded in petrochemical-linked inputs. Rising prices for key precursors such as melamine and toluene have increased production costs and squeezed margin flexibility for manufacturers that cannot pass through price adjustments quickly. In a market where performance differentiation is becoming more important, cost pressure is especially disruptive for producers competing primarily on price. It also raises the strategic importance of input hedging, process efficiency, and formulation optimization.
A third challenge is the shifting trade and classification environment. Recent tariff classification rulings for fluorescent pigments from China, effective in mid-2025, add a new layer of complexity to sourcing and pricing strategies. For global formulators and end-product manufacturers, this means that supply continuity, landed cost, and regulatory classification must be evaluated together rather than as separate procurement decisions. The practical consequence is a market in which regional sourcing flexibility and multi-supplier qualification are becoming more valuable than in the past.
These challenges do not suggest stagnation. They point to a market that is being reshaped by technical standards, compliance thresholds, and cost discipline. That reshaping creates winners among companies that treat performance, sustainability, and supply resilience as integrated design goals.
Key Drivers Analysis
Several forces are converging to drive the market’s expansion and change its competitive logic. The most important are technological reformulation, regulatory acceleration, demand-side performance expectations, and supply chain cost dynamics. Each one interacts with the others, so their combined effect is greater than the sum of individual trends.
Technological innovation is moving the market beyond bright color alone. Recent product activity illustrates how formulation science is becoming a strategic differentiator. In March 2025, DayGlo Color Corp introduced an eco-friendly daylight fluorescent pigment series using bio-based raw materials for sustainable applications in packaging and textiles. That launch is significant because it connects sustainability claims with a traditionally performance-driven category. In April 2025, Wanlong Chemical Co., Ltd. showcased its AX Series at a major plastics trade event, emphasizing brilliance and performance for plastics and rubber applications. This points to continued demand for high-impact color in durable and processed substrates. Separately, in September 2025, SINLOIHI launched new pigment formulations for LED-based decorative paints with enhanced colorfastness, addressing a fast-emerging use case where color stability under specialized lighting conditions matters. Radiant Color N.V. also expanded its Resin Centre of Excellence in Belgium in 2025 to increase specialized resin production and R&D for sustainable fluorescent pigments. Taken together, these developments show that innovation is spreading across sustainability, durability, resin technology, and application-specific performance rather than concentrating in a single area.
Fluorescent Lighting Market
Policy and regulatory dynamics are acting as both a constraint and an acceleration mechanism. The European Union’s REACH framework and related environmental regulations are systematically restricting legacy azo-based chemistries and increasingly shaping allowable VOC and resin carrier profiles in synthetic fluorescent pigments. These requirements are not confined to Europe. Regulatory pressure across North America and parts of Asia is also tightening around chemical composition, emissions, and end-use safety. The commercial impact is twofold. First, reformulation cycles are becoming a normal cost of doing business in advanced markets. Second, compliance- ready products are gaining preferential access in applications where customer specifications, brand standards, and export requirements demand lower-risk material profiles. As a result, regulatory readiness is becoming a market-access advantage rather than a purely defensive investment.
Demand-side behavior is changing because end markets are asking for more from color. Fluorescent pigments are increasingly used not only for visual impact but also for safety signaling, brand visibility, product authentication cues, and functional differentiation. In plastics and coatings, there is rising interest in pigments that can survive processing conditions, maintain appearance over time, and remain compatible with more environmentally oriented carrier systems. In inks and decorative applications, performance requirements are tightening around brightness retention and resistance to fading under varied exposure conditions. Even in textiles and sportswear, buyers are looking for brighter, longer-lasting color options that can support both aesthetics and durability. This shift means that value is increasingly determined by how well the pigment functions within the final system, not simply how it looks in isolation.
Supply chain and cost structure changes are reinforcing the need for strategic sourcing. The combination of rising petrochemical-based input costs, evolving trade classifications, and more demanding qualification processes is making supply reliability and formulation consistency more valuable. Manufacturers that can stabilize input risk, improve process efficiency, and offer predictable performance across applications are gaining leverage. At the same time, customers are increasingly willing to pay for outcomes such as reduced rework, better dispersion, lower emissions, and stronger compliance documentation. In this environment, the cost conversation is shifting from unit price alone to total cost across the application lifecycle.
Competitive Landscape and Leading Strategies
The competitive environment is shaped by a mix of established global specialists and application-oriented regional manufacturers. DayGlo Color Corp, headquartered in Cleveland, Ohio, remains the original and largest manufacturer of daylight fluorescent pigments, serving plastics, coatings, automotive, safety equipment, and consumer products with high-performance pigments, dispersions, inks, toners, and dyes. Its scale and application breadth give it a strong platform for cross-industry reach, and its recent eco-friendly product launch indicates a push toward more sustainable raw material foundations.
Radiant Color N.V., based in Houthalen, Belgium, specializes in high-performance and special-effect fluorescent pigments, dispersions, dyes, and resin technology for industrial, cosmetic, and food-contact applications. Its Belgium resin center expansion reflects a strategy centered on specialized resin development and sustainable pigment engineering, which positions the company as a formulation-focused player rather than a purely volume-driven supplier.
Wanlong Chemical Co., Ltd., located in Ruian, Zhejiang, China, manufactures daylight fluorescent pigments for plastics, rubber, coatings, inks, and textiles, with AX Series and eco-friendly formulations. Its trade presence and product emphasis show a strong commitment to performance-led positioning in plastics and rubber applications, aligning with demand in durable goods and processed materials.
Sinloihi Co., Ltd. in Japan produces ultra-bright durable fluorescent pigments for coatings, inks, and textiles, and has recently moved into LED-based decorative paint formulations with enhanced colorfastness. Its direction suggests an increasing focus on lighting-conditioned decorative applications and long-term appearance retention. Other players such as Aron Universal Ltd. in India and LuminoChem Ltd. illustrate the growing importance of specialized roles, including sportswear and fashion applications, aqueous system compatibility, and high-temperature industrial use. Huangshan Jiajia Fluorescent Material Co., Ltd. further reflects ongoing capacity expansion for packaging and textile colorants in China. These companies do not all compete on the same axis. Some differentiate through application depth, some through resin and carrier technology, and others through regional manufacturing agility.
PW Consulting
The market structure is evolving in ways that favor both consolidation and targeted differentiation. Concentration at the top suggests that scale, brand recognition, and application breadth remain important, but the moderate level of concentration also leaves space for specialists that can deliver unique performance profiles or sustainable formulations. The more probable trajectory is not a simple shakeout but a layered market in which global leaders occupy broad application space while regional and specialty players capture niche demand through technology, compliance readiness, or local manufacturing advantage.
A key strategic question for leading firms is how to balance scale, innovation, and regional exposure. The most effective positioning appears to combine three elements: durable performance claims that survive real application conditions; compliance-forward formulations that reduce customer friction in regulated markets; and supply flexibility that helps customers manage cost and classification risk. Companies that rely on a single strength, such as brightness alone or low price alone, face greater exposure as purchase criteria widen. Companies that can offer integrated value across chemistry, performance, and sustainability are better placed to influence specification decisions.
Future Trends Forecast
Looking across the 2026 to 2032 window, three trends are likely to shape the market’s next phase.
The first trend is the mainstreaming of sustainable reformulation. As regulatory expectations continue to tighten and customer sustainability programs become more operational, bio-based inputs, lower-impact carriers, and reformulated pigment systems will move from early-adopter status toward broader commercial expectations. This does not mean every application will switch at the same pace. It does mean that sustainability will increasingly function as a qualification criterion in coatings, packaging, textiles, and industrial applications. Suppliers that build credible sustainable platforms early will have an easier path into specification lists, particularly in brands and industries with public material goals.
The second trend is performance-led specialization by application. Demand will continue to fragment by use case requirements: color stability in LED environments, heat resistance in processing-intensive plastics, dispersion quality in coatings, and durability in textiles and safety gear. This favors companies that can tailor pigment systems to specific processing and exposure conditions rather than sell a generic color additive. Over time, application-specific performance will become a more efficient way to compete than broad claims of brightness alone.
The third trend is supply chain reconfiguration. Trade classifications, input cost variability, and regulatory divergence across regions will push buyers toward more diversified sourcing strategies, stronger supplier qualification, and greater attention to landed cost and compliance documentation. For manufacturers, this means regional capability, responsive technical support, and predictable batch consistency will matter more than before. For buyers, it means that dual sourcing and prequalified alternative formulations will become standard risk management tools.
These trends create commercial opportunities, but they are not risk-free. One uncertainty is the speed and uniformity of regulatory adoption across regions. If compliance expectations diverge sharply, suppliers may need to maintain multiple formulation pathways, increasing complexity and cost. Another risk is raw material cost volatility, which can compress margins if pricing power is limited. A third risk is the possibility that sustainability claims outpace verifiable technical performance, creating credibility gaps with demanding end users. The market will reward companies that can align sustainability, performance, and cost discipline rather than treat them as separate priorities.
Actionable Recommendations for Decision-Makers
For manufacturers and formulators, the most valuable move is to treat reformulation and performance optimization as market-access investments rather than cost centers. Building compliance-ready and application-validated pigment platforms now can shorten customer qualification cycles later. It is also prudent to strengthen technical service capability around dispersion, processing stability, and LED or lighting-specific performance, since these are increasingly part of the purchasing conversation. Where possible, manufacturers should diversify input sourcing and evaluate carrier alternatives that reduce exposure to petrochemical-linked cost volatility while maintaining performance consistency.
Phosphorescent Pigments Market
For investors and corporate development teams, the strategic signal is that value creation is shifting toward companies with defensible formulation assets, strong application reach, and credible sustainability narratives. Scale still matters, but it is no longer sufficient by itself. Due diligence should focus on whether a company’s technology pipeline can support next-generation regulatory expectations, whether its product portfolio aligns with high-growth application segments, and whether its cost structure can withstand input price fluctuations. Capacity expansion alone is a weaker signal than the ability to bring differentiated, compliant, and stable products to market repeatedly.
For procurement and sourcing leaders, the priority is to move beyond unit price comparisons and evaluate total application risk. That includes assessing formulation compatibility, regulatory status in target markets, colorfastness and durability performance, and supplier resilience under changing trade classifications. Pre-qualifying alternative suppliers and maintaining a short list of compliant formulations can reduce exposure to tariff, cost, and supply disruption risks. Buyers should also consider how pigment performance affects downstream outcomes such as rework, appearance retention, and compliance documentation, since these can materially change total cost over the product lifecycle.
In a market expanding at a steady pace toward 2032, the most important differentiator will be how well companies convert technical, regulatory, and cost pressures into practical advantage.
Download the Full Strategic Report
For a deeper view of market sizing, segmentation breakdowns, regional context, and company-level dynamics, the complete PW Consulting report provides additional detail and customized analysis for specific strategic decisions. The full study can be used to support specification planning, sourcing strategy, investment evaluation, and competitive positioning with more granular data than the overview above.
For detailed analysis of this topic, please visit the official page: Daylight Fluorescent Pigments Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


