



Bacterial Vaginosis Drug Market: Why 8.92% CAGR Through 2032 Changes Everything

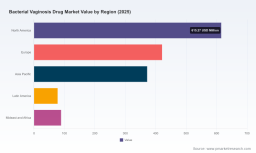
Strategic Horizons in the Bacterial Vaginosis Drug Market: Trends and Commercial Opportunities
Bacterial vaginosis represents one of the most prevalent vaginal conditions globally, creating a persistent demand for effective therapeutic solutions. The drug market serving this indication has evolved from a landscape dominated by generic antimicrobials to one increasingly shaped by differentiated formulations, extended intellectual property strategies, and geographic expansion. Understanding the strategic undercurrents in this space requires looking beyond headline revenue figures to examine the interplay of clinical innovation, regulatory pathways, reimbursement dynamics, and competitive positioning.
Worldwide Vaginal Antifungal Market
Market valuations over the historical window from 2020 through 2025 reflect steady expansion, with the sector reaching a baseline size in 2025 that sets the stage for continued growth through the forecast horizon ending in 2032. The trajectory implies a compound annual growth rate of approximately 8.92 percent across the projection period, signaling durable demand rather than a temporary surge. This growth is not uniformly distributed across therapeutic categories or indications; instead, it reflects concentrated activity around specific treatment modalities, prioritized patient populations, and regions with evolving healthcare access frameworks. The market remains moderately concentrated, with the top three participants accounting for more than half of total revenue and the top five approaching seventy percent, indicating that scale, brand recognition, and regulatory moats continue to confer meaningful advantages.
1. Market Status and Core Challenges
The current market environment is defined by a tension between established therapeutic standards and the push for more convenient, better-tolerated options. Metronidazole and clindamycin formulations have long served as the backbone of bacterial vaginosis treatment, supported by extensive clinical experience and broad availability. Yet their dominance coexists with persistent challenges around recurrence rates, patient adherence to multi-day regimens, and the need for alternatives that reduce systemic exposure or improve convenience. These clinical friction points create openings for single-dose or simplified delivery approaches, but they also raise the bar for demonstrating differentiated value in a crowded field.
A second pivotal challenge lies in the balance between innovation and generic competition. Branded products with extended exclusivity windows can capture premium positioning and drive short-term revenue momentum, but the underlying therapeutic classes remain susceptible to cost pressure once patent protections recede or when generic equivalents gain regulatory clearance. This dynamic forces companies to weigh the timing of lifecycle investments, the scope of patent coverage, and the durability of their commercial infrastructure against the risk of rapid price erosion.
A third inflection point involves the fragmentation of care pathways and payer expectations. Treatment decisions are influenced not only by clinical efficacy but also by ease of administration, tolerability profiles, and how consistently therapies are covered under pharmacy benefit designs. Manufacturers seeking to expand adoption must navigate varying reimbursement landscapes, provider education gaps, and patient awareness levels that differ substantially across care settings. The result is a market where commercial success depends as much on ecosystem engagement as on the intrinsic merits of a molecule or formulation.
2. Key Drivers of Market Change
Several interlocking forces are reshaping the competitive and commercial landscape. Understanding these drivers provides a clearer view of where investment and strategic focus are likely to generate the strongest returns.
Technological Innovation and Formulation Breakthroughs
Innovation in this market is increasingly centered on delivery optimization and regimen simplification rather than entirely new molecular entities. Single-dose oral and vaginal options address a core patient need: reducing the burden of multi-day treatment while maintaining efficacy. These approaches can improve adherence, lower the risk of incomplete therapy, and potentially reduce recurrence driven by suboptimal compliance. At the same time, formulation science is advancing around tolerability and local versus systemic exposure, enabling products to differentiate on convenience and side-effect profiles even within established drug classes.
The strategic significance of these innovations is amplified when they are paired with robust intellectual property positioning. Extended exclusivity through method-of-use, composition, and formulation patents can create a multi-year window during which a product can establish prescribing habits, secure payer coverage, and build brand loyalty before broader competition emerges. This combination of clinical differentiation and legal protection has become a defining feature of value creation in the segment.
Policy and Regulatory Environment
Regulatory dynamics play a central role in shaping both the pace of innovation and the defensibility of commercial positions. Approvals that recognize specific patient populations, age thresholds, or indication expansions can open new addressable groups and extend the commercial life of a therapy. The regulatory process also functions as a gatekeeper for generic entry and therapeutic equivalence determinations, meaning that timing differences in filings, labeling, and bioequivalence data can materially affect market share trajectories.
In parallel, the regulatory framework influences how long a company can sustain premium pricing and brand preference. Patent listings that cover core formulations and labeled indications contribute to barriers against rapid substitution, particularly when combined with limited numbers of directly equivalent alternatives in the near term. These protections do not eliminate competition, but they alter the timeline and intensity of competitive entry, giving innovators room to invest in commercialization and real-world evidence generation.
Demand-Side Shifts in Patient and Provider Behavior
On the demand side, there is growing emphasis on treatments that reduce recurrence risk and improve the patient experience. Clinicians and patients alike are increasingly attuned to the limitations of regimens that are difficult to complete or that produce nuisance side effects, and this awareness is shifting preference toward options that are simpler to administer and easier to tolerate. This is especially relevant in populations where adherence barriers are pronounced or where repeated episodes create cumulative burden.
Provider adoption is also being shaped by the availability of clear differentiation. When multiple products exist within the same class, clinicians look for tangible distinctions in dosing frequency, application method, or safety profile to guide prescribing. Educational outreach, guideline inclusion, and real-world performance data therefore become critical complements to regulatory approval, influencing how quickly a new or repositioned product can gain traction in routine practice.
Supply Chain and Cost Structure Considerations
Cost structures across this market are influenced by the interplay of branded exclusivity, generic manufacturing scale, and distribution complexity. Generic producers benefit from established manufacturing pathways and broad distribution networks, enabling competitive pricing and wide geographic reach. Branded players, by contrast, must justify premium positioning through differentiated attributes, patient support programs, or specialized distribution arrangements that add value beyond the molecule itself.
Geographic expansion adds another layer of complexity. Entering regions with varied regulatory requirements, procurement models, and healthcare infrastructure demands flexible commercial strategies. Partnerships that combine local market knowledge with product supply can accelerate adoption, but they also require careful coordination around pricing, access, and quality assurance. As companies pursue growth beyond mature markets, the ability to tailor supply and commercialization models to local conditions becomes a decisive factor in realizing opportunity.
3. Competitive Landscape and Leading Strategies
The competitive field blends large multinational manufacturers with targeted innovators and established generic suppliers. Each group brings a distinct strategic posture, and the interactions among them define the market's evolution.
Strategic Positioning of Leading Participants
Specialized innovators have focused on building defensible niches through single-dose offerings and long-duration exclusivity. One company has leveraged a single-dose oral granule product as the only oral treatment of its kind approved for bacterial vaginosis in patients twelve years and older, supported by multiple Orange Book patent listings that extend protection into the 2040s. This approach combines clinical differentiation with a durable intellectual property foundation, allowing the company to position the product as a streamlined alternative within a market otherwise dominated by multi-day regimens.
Worldwide Postmenopausal Vaginal Atrophy Drugs Market
Another innovator has pursued a parallel path with a single-dose vaginal gel, differentiating on delivery method and convenience while securing global rights through licensing arrangements. By aligning product development with distribution partnerships, this strategy seeks to extend geographic reach and commercial scale without bearing the full burden of in-region infrastructure. Such licensing models can accelerate penetration in new markets while preserving capital for further development and lifecycle management.
Larger diversified manufacturers maintain presence through branded and generic versions of established therapies, using scale, multi-Region supply, and broad formulary relationships to sustain share. These players often compete on availability, cost, and integration with existing procurement channels, while also exploring lifecycle extensions where feasible. Generic specialists contribute additional price competition and regional breadth, reinforcing the market's baseline accessibility and placing pressure on premium-priced alternatives to demonstrate clear differentiation.
Differentiation and Moat-Building Strategies
Across these participants, several strategic themes recur. First, regimen simplification is used not only as a clinical advantage but also as a commercial anchor, helping products stand out in prescribing decisions and patient conversations. Second, patent strategy is deployed to protect not just the molecule but also the method, composition, and specific labeled uses, extending the effective commercial horizon beyond the core compound patent. Third, partnership structures are increasingly important for scaling internationally, with licensing and exclusive distribution agreements enabling faster market entry and shared execution risk.
These strategies are not mutually exclusive. A company can combine a differentiated formulation with robust IP, then extend reach through regional collaborations, creating layers of defensibility that are more durable than any single element alone. The most resilient positions tend to integrate clinical convenience, legal protection, and commercial access in a way that makes substitution less attractive to prescribers and payers alike.
Evolution of the Competitive Structure
The market is moving along a path that blends concentration at the top with ongoing segmentation below. The leading branded innovators capture disproportionate attention and revenue in the near term, especially when exclusivity and differentiation align. At the same time, the broader field remains active with generic alternatives and regional manufacturers that sustain access and price competition. This structure suggests continued differentiation rather than rapid consolidation, with companies competing on convenience, tolerability, coverage, and distribution depth rather than price alone.
New entrants and license-driven expansions are likely to keep pressure on the boundaries of existing franchises. Opportunities will arise for players that can bring credible single-dose or improved-tolerance options into underserved regions, or that can create value through partnership models that combine product assets with local commercialization capability. The market's evolution will therefore be shaped by a mix of lifecycle extension by incumbents and targeted entry by specialists, each leveraging distinct assets and go-to-market strengths.
4. Future Trends and Commercial Opportunities
Projecting the next three to five years requires connecting clinical, regulatory, and commercial signals into coherent trajectories. Several trends are likely to define where value is created and where risk accumulates.
-
Continued emphasis on regimen simplification and adherence-friendly designs. Therapies that reduce dosing frequency or streamline administration are expected to gain further attention as prescribers and patients prioritize convenience and completion. Products that can demonstrate reliable efficacy alongside a simpler regimen will be well positioned to capture share, particularly if supported by favorable tolerability and clear clinical guidance. The commercial opportunity lies in pairing regulatory approval with provider education and patient support to convert structural advantage into habitual use.
-
Geographic expansion into underpenetrated regions. Growth in the forecast period is likely to be supported by increasing access in regions where awareness, diagnostic capacity, and treatment infrastructure are improving. Companies that establish localized distribution, appropriate pricing tiers, and partner ecosystems can convert demographic and epidemiological demand into sustainable revenue. The key risk is execution complexity: varying regulatory requirements, procurement practices, and reimbursement models can slow adoption if not addressed early and with local insight.
-
Lifecycle management through intellectual property and indication breadth. As some products benefit from extended exclusivity, the market will see sustained periods where branded differentiation holds premium positioning. This creates opportunities for companies to invest in real-world evidence, expand labeled uses where scientifically justified, and reinforce prescriber familiarity. The countervailing risk is that overreliance on exclusivity without clinical or commercial differentiation can leave a product vulnerable when competition eventually arrives, especially if generic or alternative branded options gain traction on price or convenience.
These trends point to a market where advantage is constructed rather than simply inherited. The most attractive commercial opportunities will sit at the intersection of clinical convenience, durable protection, and capable execution in target geographies. Conversely, players that depend on a single attribute without supporting evidence, coverage, or distribution may find their position eroded more quickly than anticipated.
5. Actionable Guidance for Decision-Makers
The strategic implications vary by role, but several priorities apply across the board. Clear positioning, disciplined execution, and timely intelligence will separate opportunities that scale from those that stall.
PW Consulting
For Manufacturers and Product Owners
Prioritize differentiation that is clinically meaningful and commercially tangible. A simpler regimen, improved tolerability, or a clearly defined patient population can provide a persuasive basis for preference, but only if it is reinforced through provider education, patient support, and payer engagement. Simultaneously, protect the commercial horizon with a deliberate IP strategy that covers formulation, method, and use where feasible, and evaluate partnership structures that can extend reach without overextending internal resources. Build supply and access models that are adaptable to regional conditions, especially when pursuing growth in markets with distinct procurement and reimbursement dynamics.
For Investors and Capital Allocators
Assess durability of advantage, not just near-term revenue momentum. Exclusivity timelines, the breadth of patent coverage, and the presence of credible alternatives all influence how long a product can sustain premium positioning. Favor opportunities where clinical convenience is paired with execution capability in target regions, and where licensing or distribution agreements create scalable pathways without disproportionate capital risk. Be attentive to the timing of generic entry and to the extent to which a product's differentiation is likely to withstand substitution pressure once protections recede or competing options mature.
For Procurement and Access Stakeholders
Balance cost considerations against total value, including adherence, recurrence risk, and ease of administration. Where multiple options exist within the same class, evaluate not only unit price but also the practical impact of regimen complexity and tolerability on completion and outcomes. Engage early with suppliers on supply reliability, market-specific access terms, and evidence packages that support formulary decisions. A disciplined evaluation framework that incorporates clinical usability and patient experience can improve both cost efficiency and treatment success over time.
The bacterial vaginosis drug market is entering a phase where differentiation, protection, and execution intersect more tightly than in the past. Companies and investors that understand these dynamics in detail, and that align strategy with the realities of prescribing behavior, payer expectations, and regional access, will be better positioned to capture sustainable value. For decision-makers seeking deeper segmentation, region-specific demand patterns, and tailored scenario analysis, a comprehensive research report can provide the granularity needed to translate these strategic insights into concrete planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Bacterial Vaginosis Drug Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


