



Radiator Hose Market: Why the 3.5% CAGR and Asia Pacific's 89.84M Lead Through 2032

Strategic Trends and Commercial Opportunities in the Radiator Hose Market
Market Snapshot and Structural Challenges
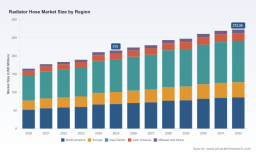
The global radiator hose market has demonstrated steady, predictable growth over the past five years, expanding from approximately $165.0 million in 2020 to $215.0 million in 2025. This trajectory reflects a compound annual growth rate of 3.5 percent through the 2026-2032 forecast horizon. While the growth profile appears conventional for an established automotive component sector, the underlying dynamics reveal a market at a structural inflection point. Revenue expansion is no longer solely a function of vehicle production volumes; it is increasingly shaped by material substitution, regulatory tightening, and shifting channel economics.
Understanding the current market size requires acknowledging that the headline figure masks divergent performance across vehicle platforms, material technologies, and geographies. Silicon-based hoses continue to command the largest revenue share among material categories, driven by their compatibility with high-temperature engine architectures and synthetic coolants. Rubber formulations maintain significant traction in cost-sensitive applications, while emerging material blends are gaining ground as manufacturers respond to durability mandates and environmental specifications. Passenger cars remain the dominant vehicle segment by revenue, though commercial vehicle applications are growing at a faster pace as fleet operators prioritize extended maintenance intervals and thermal reliability.
Hydraulic Hose Market
Beneath these structural patterns, the market confronts three interconnected challenges that will define competitive outcomes over the next several years.
First, the regulatory environment is compounding performance requirements in ways that strain traditional hose design paradigms. Emission standards in major markets now cascade indirectly into thermal management specifications, as tighter engine tuning and advanced combustion strategies demand coolant hoses with tighter temperature tolerances and improved chemical resistance. The effect is not merely incremental; it forces redesign cycles, validation costs, and supply chain re-qualification that compress margins for manufacturers unable to absorb engineering overhead.
Second, trade policy disruption has altered procurement economics. Tariff escalations introduced in 2025 have raised effective import costs on certain hose categories, prompting OEMs and tier suppliers to reconsider geographic sourcing footprints. This has accelerated supply chain diversification efforts but also introduced short-term cost volatility and qualification complexity for alternative supplier bases. Companies that previously optimized for lean inventory and single-source efficiency are now re-evaluating risk-adjusted sourcing models.
Third, the aftermarket channel continues to gain relative importance as global vehicle fleets age and compliance-driven repairs extend service life. While OEM volumes remain the dominant commercial pathway, aftermarket demand is becoming a more meaningful growth lever, particularly for heavy-duty and commercial applications where replacement cycles are lengthening. This shift changes the competitive calculus: aftermarket success depends less on production scale and more on distribution reach, fitment precision, and brand trust in repair ecosystems.
PW Consulting Automotive & Machinery Research Center
Critical Drivers Reshaping the Market
The market’s evolution is being propelled by a combination of technological, regulatory, demand-side, and supply chain forces. Each driver interacts with the others, creating compounding effects that reward companies able to align engineering, sourcing, and commercial strategy.
Technological Innovation and Material Science Advances
Material innovation is the most consequential technical driver in the radiator hose market. Manufacturers are increasingly adopting advanced composites, reinforced silicone constructions, and hybrid rubber-thermoplastic formulations to meet stricter thermal and pressure requirements. The shift is not simply about durability; it is about enabling engine architectures that run hotter, use synthetic coolants, and require hoses capable of maintaining sealing integrity across wider temperature ranges.
Adoption of advanced manufacturing technologies has accelerated this transition by lowering cost barriers. In 2025, the market for eco-friendly automotive radiator hoses grew by more than 15 percent, while advanced manufacturing processes increased adoption by 20 percent to reduce production costs. This combination of performance improvement and cost optimization is significant because it expands the addressable market for higher-specification hoses beyond premium platforms into broader passenger and commercial applications. Companies that can demonstrate equivalent reliability at lower lifecycle cost are positioning themselves to capture share from conventional rubber designs.
Policy and Regulatory Environment
Regulation is reshaping product specifications and channel behavior simultaneously. In China, the GB 18352.6-2024 standard requires improved particulate matter and nitrogen oxide limits, which in turn mandates radiator hose upgrades for ISO 3384 performance and synthetic coolant compatibility. European regulations under Euro 6d-TEMP impose coolant hose materials with precise temperature tolerance of plus or minus 2 degrees Celsius for advanced combustion engines. These requirements raise the technical bar for suppliers and reward those with established material science capabilities and qualified validation infrastructures.
Beyond product specifications, regulatory pressure is also influencing channel mix. OEM and aftermarket channels accounted for 62.4 percent and 37.6 percent of market value respectively in 2025, driven by vehicle fleet aging and emission compliance. Compliance-related service interventions are sustaining aftermarket demand even as new vehicle production cycles fluctuate. For manufacturers, this means regulatory momentum is not only a product engineering challenge but also a commercial opportunity in the service and replacement segment.
Demand-Side Shifts in Consumer and Fleet Behavior
Demand patterns are being shaped by two parallel trends: the expansion of high-performance passenger vehicles and the increasing emphasis on durability in commercial fleets. Passenger car buyers and manufacturers are prioritizing thermal efficiency as engine downsizing and turbocharging become more common, creating demand for hoses that can handle elevated operating conditions without compromising longevity. In parallel, fleet operators are seeking components that reduce downtime and extend service intervals, which favors more robust hose designs and higher-grade materials.
These demand shifts are also influencing purchasing behavior in the aftermarket. As vehicles remain in service longer, repair and replacement decisions are increasingly guided by parts that offer improved reliability and compatibility with modern coolant chemistries. This creates a market environment where product differentiation in the aftermarket is becoming more valuable, especially for suppliers that can provide engineered fitment solutions and clear performance credentials.
Supply Chain and Cost Structure Evolution
Cost structures are being redefined by raw material dynamics, tariff impacts, and manufacturing process improvements. The increased tariff burden on certain imports has forced procurement teams to weigh the trade-offs between cost, risk, and qualification lead times. Some manufacturers are regionalizing supply arrangements, while others are pursuing multi-source strategies to mitigate exposure. These decisions are not purely cost-driven; they reflect a broader shift toward resilience as a strategic priority.
At the same time, efficiency gains from advanced manufacturing are partially offsetting input cost pressures. Companies that can integrate material innovation with process optimization are achieving better margin defense than those relying solely on volume scale. This is particularly relevant for market participants that compete in both OEM and aftermarket channels, where cost discipline and product performance must be balanced across different commercial models.
Competitive Landscape and Leading Strategies
The radiator hose market is characterized by moderate concentration, with the top three players accounting for 28.5 percent of market share and the top five reaching 32.0 percent. This structure suggests a market where scale advantages exist but are not insurmountable, and where specialized capabilities can still generate competitive differentiation. The presence of multiple global manufacturers alongside regionally focused suppliers indicates that both global reach and localized technical service remain valuable.
Several companies illustrate distinct strategic positioning within this landscape. Gates Corporation has built a comprehensive presence across fluid power and engine hose applications, leveraging molded, flexible, and braided constructions to serve both OEM and aftermarket thermal management needs. Its breadth across hose architectures provides flexibility in addressing diverse vehicle requirements. Continental AG, through its ContiTech division, emphasizes advanced materials and integrated sensor technologies, positioning its hose solutions as part of broader vehicle systems rather than standalone components. This systems-oriented approach aligns well with the trend toward tighter performance tolerances and smarter thermal management.
Dayco Products LLC focuses on molded radiator hoses for passenger vehicles and light-duty applications, with an emphasis on durability and OE fitment. This specialization supports strong positioning in segments where precision and reliability are primary purchase criteria. Parker Hannifin Corporation extends its fluid management expertise across industrial, marine, and automotive applications, allowing it to transfer high-pressure and thermal management capabilities across markets. Hutchinson SA stands out for its vertically integrated manufacturing model and strong OEM partnerships in Europe, enabling customized thermal management solutions with close engineering collaboration.
In Asia, Toyoda Gosei and Sumitomo Riko maintain strong ties to regional OEM production, with Toyoda Gosei benefiting from integrated high-volume passenger car applications and Sumitomo Riko supplying Asian manufacturers with precision rubber compounds. Tokyo Rubber Co., Ltd. also plays a significant role as a key Asian OEM supplier focused on precision thermal management components. Goodyear continues to leverage its global supplier reputation with an emphasis on sustainability and multi-year supply agreements, as illustrated by its September 2025 supply agreement with Ford for advanced radiator hoses on global vehicle platforms. Fairchild Industries provides an example of a custom manufacturer that supports engineering design services and direct-to-OEM production, highlighting the value of flexible, design-led engagement in specialized applications.
Recent market activity further underscores the strategic directions shaping competition. In January 2025, Crown Automotive launched a new aftermarket radiator hose line for heavy-duty trucks, signaling continued investment in the commercial aftermarket segment. In February 2025, ACDelco introduced an eco-friendly radiator hose made from recycled rubber and thermoplastics, reflecting the growing importance of sustainable material narratives and regulatory-aligned product claims. These moves illustrate how companies are using product launches and supply agreements not only to secure volume but also to reinforce technological and commercial positioning.
The competitive landscape is evolving along several axes. Integration is visible among manufacturers seeking to control material formulation, production, and qualification within a single value chain, particularly where regulatory compliance and performance validation are becoming more complex. At the same time, there is room for differentiation through application specialization, as companies target specific vehicle segments, regions, or channel models with tailored engineering and service capabilities. New entrants and smaller suppliers may find opportunity in niche applications, custom design services, or sustainable material formulations, especially where larger incumbents are constrained by scale-driven process architectures. The overall trend is toward a market in which competitive advantage will increasingly depend on the ability to combine material expertise, regulatory readiness, sourcing flexibility, and channel-specific commercial execution.
Forward Outlook: Trends and Commercial Implications
Looking ahead to the next three to five years, three trends are likely to shape the radiator hose market’s trajectory and associated commercial opportunities.
The first trend is the continued migration toward higher-specification materials as baseline performance requirements rise. As emission and thermal management standards tighten globally, conventional hose designs will face growing pressure to demonstrate compatibility with synthetic coolants, tighter temperature tolerances, and extended service life. This creates a commercial opportunity for suppliers that can offer validated advanced formulations with cost-efficient manufacturing pathways. Companies that treat material upgrades as a premium feature alone may miss the broader shift toward mainstream adoption of higher-performance hoses in mid-tier vehicle segments.
The second trend is the reconfiguration of supply chains in response to trade policy and risk management priorities. Tariff-driven cost changes and procurement realignment are likely to persist as strategic considerations rather than temporary disruptions. This favors manufacturers with diversified sourcing options, regional production flexibility, and the ability to qualify alternative supplier bases without protracted validation cycles. For buyers, this trend increases the importance of supplier selection criteria that weigh resilience and compliance readiness alongside unit cost. For investors, it suggests that operational agility and supply chain transparency will become more relevant valuation factors than scale alone.
The third trend is the growing commercial significance of the aftermarket as fleets age and compliance-related service needs expand. Replacement demand is increasingly influenced by part reliability, fitment accuracy, and sustainability credentials. Suppliers that can build strong aftermarket distribution, provide clear technical differentiation, and align product claims with environmental expectations are likely to capture disproportionate value in this channel. At the same time, the aftermarket presents risk for participants that depend primarily on OEM volume without a credible service-channel strategy, since channel diversification can buffer demand volatility and improve long-term revenue resilience.
These trends carry potential uncertainties. Regulatory timelines and technical thresholds may shift as standards evolve, altering product development priorities. Material supply constraints or cost volatility could affect margin trajectories, particularly for newer sustainable formulations that depend on specific input streams. Vehicle production cycles, especially in commercial segments, may fluctuate with macroeconomic conditions and infrastructure spending patterns. Competitive responses from incumbents and new entrants could also compress returns in segments where differentiation is difficult to sustain.
Worldwide Oil Hose Market
Strategic Guidance for Decision Makers
For manufacturers, the priority is to align product roadmaps with the intersection of regulatory requirements, material innovation, and channel demand. Engineering investments should focus on hose designs that can meet tighter temperature and chemical compatibility specifications while remaining cost-competitive through advanced manufacturing processes. At the same time, supply chain strategies should incorporate flexibility to respond to tariff-driven cost changes and sourcing diversification needs. Companies that can demonstrate validated performance, sustainable material options, and reliable qualification capability will be better positioned to secure both OEM partnerships and aftermarket credibility.
For investors, the market offers a profile of steady growth with differentiated value creation depending on operational and technological positioning. Interest should be directed toward companies that combine material science capability with process efficiency, strong OEM relationships, and a credible aftermarket presence. The moderate market concentration suggests that specialized players can still generate meaningful returns if they occupy defensible segments or possess unique engineering and service capabilities. However, valuation assumptions should account for regulatory adaptation costs, sourcing realignment risk, and the possibility that material transitions could reshape competitive hierarchies over time.
For procurement and supply chain leaders, the environment calls for a more balanced evaluation of supplier selection criteria. Unit price remains important, but resilience, compliance readiness, and the ability to support evolving material and performance specifications should receive greater weight. Multi-source strategies, regional sourcing options, and suppliers with demonstrated advanced manufacturing efficiency can reduce exposure to tariff volatility and qualification delays. Procurement teams should also monitor aftermarket availability and fitment reliability, particularly for heavy-duty and commercial applications where downtime costs can exceed component price differences.
For stakeholders seeking a more detailed understanding of segment-level dynamics, regional variation, and forward-looking scenario analysis, a comprehensive market research report can provide the granularity needed to translate these strategic themes into execution plans. Deep-dive segmentation data, competitive benchmarking, and customized procurement or investment scenarios can help decision makers move from directional insight to targeted action.
For detailed analysis of this topic, please visit the official page: Radiator Hose Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


