



Wireless Router Market 2026-2032: 8.9% CAGR vs. 74% Dual-Band Dominance

Strategic Shifts in the Wireless Router Market: Navigating Growth, Competition, and Emerging Opportunities (2025–2032)
The global wireless router market has entered a new phase of expansion, characterized by steady revenue growth, accelerating technological transitions, and shifting regulatory frameworks. From 2020 through 2025, industry revenue climbed from approximately USD 108 million to USD 150 million, reflecting sustained demand for reliable, high-performance connectivity. Looking ahead to 2032, the market is projected to reach USD 271.95 million, supported by a compound annual growth rate of 8.9 percent. This trajectory signals more than incremental expansion; it points to a structural realignment in how networks are designed, deployed, and monetized. For executives and investors, the question is no longer whether the market will grow, but which segments, capabilities, and strategic positions will capture disproportionate value as the landscape matures.
Routers Market
1. Market Landscape and Core Challenges
The revenue curve from 2020 to 2025 shows a market recovering from supply-constrained years and then moving into a demand-led growth phase. Growth in 2021 and 2022 was followed by continued expansion through 2023 and 2024, with 2025 closing at USD 150 million. The forecast period from 2026 to 2032 indicates accelerating annual increments, with revenue expected to cross USD 163 million in 2026 and approach USD 228 million by 2030 before reaching the 2032 target. This pattern reflects a market that is transitioning from hardware replacement cycles toward higher-value networking solutions that support denser device ecosystems, cloud-managed deployments, and increasingly distributed enterprise environments.
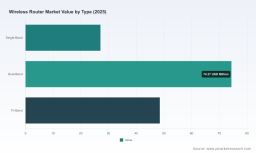
Market concentration remains moderate. The top three players account for roughly 25.5 percent of revenue, while the top five reach approximately 35.2 percent. This level of concentration suggests a competitive field where scale matters but does not dictate outcomes. Regional dynamics are uneven, with some geographies showing stronger residential adoption and others leaning toward enterprise and service-provider deployments. Across application segments, residential use continues to anchor total demand, while enterprise and other specialized deployments contribute meaningful incremental revenue as organizations upgrade legacy connectivity infrastructure. By product type, the market is moving away from basic single-band offerings toward dual-band architectures as the volume baseline, with tri-band solutions gaining traction in performance-sensitive environments.
Key Challenges and Inflection Points
- Spectrum and regulatory fragmentation : Wireless routers operate within an evolving spectrum management environment. Recent regulatory actions point toward more flexible sharing models, but uneven coordination across jurisdictions can create deployment complexity, compliance overhead, and product adaptation costs.
- Performance expectations outpacing baseline hardware : Consumer and enterprise users increasingly expect consistent throughput, low latency, and seamless device handling. As device density rises, routers that cannot manage interference, prioritize traffic, or maintain stability under load face rapid obsolescence.
- Margin pressure from commoditization at the entry level : Basic router segments remain vulnerable to price competition, while value creation shifts toward differentiated features, service attach, and software-driven management. Companies relying on volume without clear performance or ecosystem advantages risk seeing gross margins erode.
2. Key Drivers of Market Change
Technology Innovation and Breakthroughs
The most visible driver is the steady progression of Wi-Fi standards and the associated hardware capabilities required to exploit them. The introduction of Wi-Fi 7–class routers, such as TP-Link’s ARCHER BE9700 launched in November 2025 with enhanced 6 GHz band support, illustrates how product roadmaps are shifting toward higher throughput and improved performance in congested environments. The practical impact is not merely faster theoretical speeds; it is better handling of simultaneous workloads, more reliable connectivity for dense device households and offices, and stronger positioning for applications that demand predictable performance. As these capabilities filter from flagship models into broader portfolios, they raise the baseline for competitive products and push the market toward higher ARPU through feature-rich devices.
Equally important is the growing role of intelligent network management. Regulatory attention to artificial intelligence and machine learning for spectrum sharing, including the FCC’s August 2025 report recommending an internal working group to improve spectrum utilization efficiency, signals a longer-term expectation that network equipment will need to operate more adaptively. For wireless routers, this trend supports features such as dynamic channel selection, traffic prioritization, interference mitigation, and remote diagnostics. Hardware is increasingly only one part of the value proposition; the ability to manage the radio environment intelligently is becoming a differentiator.
Policy and Regulatory Environment
Regulatory developments are reshaping both market access and product strategy. The FCC’s January 2026 order modernizing spectrum sharing for satellite broadband reflects a broader push to expand wireless connectivity through less restrictive rules, which can stimulate demand for complementary ground-side equipment and improve overall connectivity ecosystems. At the same time, the European Commission’s proposed Digital Networks Act, published in January 2026, strengthens coordination of radio spectrum management and promotes spectrum sharing as a default under a “use it or share it” principle. This addresses fragmentation across Member States but also introduces a compliance environment where spectrum efficiency and interoperability become strategic priorities rather than optional enhancements.
Another regulatory dimension is the FCC’s 2025 reclassification of broadband internet access service as an information service, which limits regulatory authority over net neutrality rules for wireless router and ISP deployments. While this does not directly dictate router design, it influences the commercial environment in which ISPs, OEMs, and channel partners operate. Reduced regulatory constraints on certain service practices can alter bundling strategies, managed-service models, and the balance of features prioritized by service providers versus retail customers.
Demand-Side Shifts in Consumer and Enterprise Behavior
Demand is being shaped by two parallel forces: higher connectivity expectations at home and more distributed, performance-sensitive enterprise environments. Residential users increasingly treat Wi-Fi as essential infrastructure supporting working from home, gaming, streaming, smart home devices, and multi-device households. This elevates the importance of reliability, coverage, and ease of management. In enterprise settings, organizations are expanding hybrid work, branch connectivity, and IoT-enabled operations, which increases demand for routers and gateways that can support secure, stable, and manageable networks without requiring excessive on-site IT intervention.
A related demand-side shift is the growing preference for solutions that reduce total cost of ownership through remote management, automated troubleshooting, and firmware agility. Buyers are more willing to pay for operational simplicity and predictable performance than for raw specifications alone. This shifts competitive advantage toward vendors that can combine hardware quality with software experience and serviceable support models.
PW Consulting
Supply Chain and Cost Structure Dynamics
Cost structures in the wireless router market are influenced by component availability, manufacturing scale, and the balance between retail and channel-led distribution. As product complexity increases with newer Wi-Fi generations and additional radio bands, bill-of-materials pressure can rise. At the same time, mature manufacturing ecosystems and competitive sourcing can help offset some of that pressure, particularly for high-volume segments. Companies that can manage component planning, align product cycles with demand, and avoid excess inventory exposure are better positioned to protect margins during transitional periods.
There is also a structural shift in how value is captured across the supply chain. Where legacy router markets often competed on unit price, current dynamics reward vendors that can integrate performance, manageability, and ecosystem compatibility. This favors players that can coordinate silicon selection, antenna design, firmware development, and user experience into a coherent offering rather than treating the router as a standalone commodity device.
3. Competitive Landscape and Leading Strategies
Strategic Positioning and Differentiation
The competitive field includes established consumer-focused players, enterprise and service-provider specialists, and emerging niche brands. NETGEAR, based in San Jose, California, continues to compete on a broad consumer and prosumer portfolio, with an emphasis on performance-oriented home networking and connected device management. ASUS, headquartered in Taipei, has built a strong reputation around feature-rich router platforms that blend performance with software differentiation, appealing to users who prioritize customization, gaming, and advanced networking controls. TP-Link, based in Shenzhen, competes at scale with a wide range of price-performance options and has expanded its presence in higher-end categories, including Wi-Fi 7–enabled devices, aiming to cover both volume and premium demand. ASUSTeK, also in Taipei, contributes enterprise and broader hardware capabilities that can intersect with networking infrastructure needs beyond consumer routers.
On the service-provider and enterprise side, Calix and Arris bring a different strategic focus. Calix, also based in San Jose, emphasizes platforms and services that support broadband service operators, aligning router and gateway offerings with managed service requirements. Arris, headquartered in Suwanee, Georgia, has historically participated in broadband access and connectivity ecosystems where router and network equipment intersect with carrier deployment models. These players differentiate less on retail branding and more on integration, deployment support, and compatibility with operator infrastructures. Other participants such as Arcadyan Technology, Sagemcom, Inseego, and GL.iNet occupy distinct positions, ranging from telecom-oriented manufacturing to specialized secure or travel-friendly router solutions, each targeting narrower customer needs that larger broadline vendors may not fully address.
Differentiation in this market increasingly depends on three elements: radio and throughput performance, software and management experience, and channel or ecosystem alignment. Vendors that combine strong hardware execution with intuitive setup, remote management, security posture, and reliable firmware support tend to earn higher retention and stronger word-of-mouth in residential markets. In enterprise and carrier-adjacent segments, differentiation shifts toward interoperability, serviceability, and scalability.
Evolution of the Market Structure
The market is moving along two concurrent paths: gradual consolidation at the top and continued differentiation at the edges. Moderate concentration indicates that scale leaders exist, but there is still room for specialized players to compete by focusing on specific customer segments, use cases, or feature priorities. Over the next several years, the structure is likely to remain pluralistic rather than becoming dominated by a small number of winners, because demand is diversified across retail, enterprise, and service-provider channels.
At the same time, pressure is building for portfolio rationalization. As higher-performance standards become mainstream, vendors that cannot move up the value curve may find themselves confined to low-margin segments. New entrants and niche brands can still succeed by addressing underserved needs, such as secure travel routers, privacy-oriented configurations, or connectivity solutions tailored to specific professional environments. The broader trend is therefore not pure consolidation but a layered market in which broadline vendors compete on reach and portfolio breadth, while specialized players compete on precision and differentiation.
WiFi Home Router Market
4. Future Trends and Commercial Opportunities
Trend 1: Wi-Fi 7 Adoption as a Growth Catalyst, Not a Niche Upgrade
Wi-Fi 7–class features, including enhanced use of the 6 GHz band and improved handling of high-throughput workloads, are likely to move from flagship introductions into broader commercial relevance over the next few years. This matters because adoption is not simply about marketing a new standard; it reshapes purchasing criteria across residential upgrades and performance-sensitive enterprise deployments. As more environments deploy dense device sets and demanding applications, routers that can manage congestion and deliver consistent performance will gain share. The commercial opportunity lies in tiered portfolios that allow customers to migrate at different pace and price points, while preserving upgrade paths that protect longer-term relevance.
Trend 2: Spectrum Efficiency and Smarter Network Management as Competitive Requirements
The regulatory direction toward spectrum sharing and improved utilization, supported by initiatives such as the FCC’s AI and machine learning recommendations and the European Digital Networks Act, suggests that routers will increasingly be evaluated on how well they operate within shared and dynamic spectrum environments. Devices that can adapt to interference, optimize channel use, and support remote management will be better positioned in both retail and service-provider channels. The opportunity here extends beyond hardware sales to managed services, software subscriptions, and support models that monetize ongoing network performance rather than one-time device purchases.
Trend 3: Hybrid Demand Between Retail, Enterprise, and Service Provider Channels
The market is likely to see continued overlap between consumer-style retail routers, enterprise-grade managed gateways, and carrier-provisioned equipment. This hybrid demand creates opportunities for vendors that can serve multiple channels with shared platforms but distinct configurations, branding, and support models. Companies that design for flexibility can capture value across segments without fully duplicating development effort. However, channel conflict, certification requirements, and differing customer expectations create execution risk, especially for organizations that attempt to serve all segments without clear positioning.
Risks and Uncertainties
- Regulatory divergence : Spectrum rules, device certification, and service regulations may evolve at different speeds across regions, raising product adaptation costs and slowing launch timing.
- Adoption asymmetry : Premium features may penetrate certain markets faster than others, creating uneven product cycles and inventory risk if demand forecasts misread regional maturity.
- Competitive escalation in performance claims : As higher standards become common, differentiation may narrow at the hardware level, pushing competition toward software, brand trust, and service quality, where execution barriers can be high.
5. Strategic Actions for Decision Makers
For Manufacturers and Product Leaders
- Prioritize performance and manageability over specification stacking : Buyers increasingly value stable throughput, practical coverage, and easy administration. Roadmaps should balance radio upgrades with firmware, diagnostics, and user experience improvements that deliver perceived reliability.
- Build tiered portfolios with clear upgrade paths : Instead of treating new standards as a single premium product moment, create migration ladders that allow customers to enter at different price points while preserving future relevance.
- Prepare for spectrum efficiency as a design requirement : Product teams should anticipate regulatory pressure for better spectrum utilization and incorporate adaptive management capabilities that reduce interference and improve operational efficiency.
For Investors and Corporate Strategists
- Focus on value capture beyond unit sales : Companies that can attach managed services, software features, or support relationships are better positioned to defend margins than those competing primarily on hardware volume.
- Assess channel alignment carefully : Retail, enterprise, and service-provider paths reward different capabilities. Investment theses should consider whether a company’s distribution, certification footprint, and support model match its target segment.
- Monitor regulatory catalysts : Spectrum sharing reforms and broadband policy shifts can influence demand speed, product requirements, and competitive dynamics. These are not background issues; they can change the pace and shape of adoption.
For Procurement and Enterprise Buyers
- Evaluate total cost of ownership rather than sticker price : In denser environments, the cost of poor performance, manual troubleshooting, and premature replacement can exceed the savings from lower upfront pricing.
- Require evidence of real-world stability and manageability : Benchmarking should include device density, reload and recovery behavior, firmware update processes, and remote management capabilities, not only peak throughput claims.
- Plan for upgrade cycles aligned to usage growth : As device counts and application demands increase, procurement strategies should anticipate transition points rather than reacting after performance bottlenecks appear.
The wireless router market is entering a period in which growth is supported by clear demand tailwinds, but competitive advantage will depend on execution quality across hardware, software, and channel strategy. The most successful players will be those that treat performance, spectrum efficiency, and manageability as interconnected requirements rather than isolated product features. For organizations seeking a deeper view of segment-level sizing, regional dynamics, company positioning, and scenario-based forecasts, the full PW Consulting market research report offers more granular data and customized strategic recommendations to support planning across manufacturing, investment, and procurement decisions.
For detailed analysis of this topic, please visit the official page: Wireless Router Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


