



Mobile Patient Lifts Market Hits $557M by 2032: Decoding the 8.55% CAGR Story

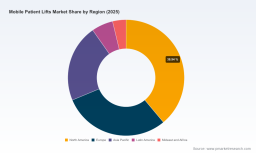
Mobile Patient Lifts Market: Strategic Trends and Commercial Opportunities (2026–2032)
The global mobile patient lift sector has entered a phase of sustained, structurally supported growth. Valued at approximately 315 million USD in 2025, the market is projected to expand at a compound annual growth rate of 8.55 percent, reaching 557 million USD by 2032. This trajectory reflects more than incremental demand; it signals a fundamental shift in how care environments manage patient mobility, caregiver safety, and asset utilization. Over the 2020–2025 historical period, revenue climbed from 210 million USD to 315 million USD, a pattern that underscores steady adoption across acute, long-term, and residential care settings. The forward-looking window through 2032 points to continued expansion, though the composition of growth and the competitive rules of engagement are evolving rapidly. For decision-makers, the central question is no longer whether demand will persist, but how to position operations, portfolios, and capital to capture disproportionate value in a market that is simultaneously diffusing and consolidating.
Market Structure and Inherent Tensions
The revenue base remains concentrated among a limited group of established players, with the top three firms collectively accounting for roughly 28.5 percent of total market value and the top five reaching approximately 36.2 percent. This concentration indicates that scale, brand credibility, and service infrastructure still confer meaningful advantages, particularly in institutional procurement cycles where risk aversion and compliance documentation carry heavy weight. At the same time, the remaining share is distributed across a broad field of regional suppliers, niche manufacturers, and service-led distributors, which keeps price competition lively and accelerates feature differentiation at the periphery.
Several structural tensions define the current operating environment. First, adoption is bifurcated between high-acuity institutional settings and decentralized home-based care. Hospitals and nursing facilities continue to drive substantial volume, but home care represents a faster-growing, more fragmented endpoint that demands portability, simplified setup, and stronger caregiver training support. Second, procurement cycles are lengthening in publicly funded systems, even as overall spending on mobility and safety equipment trends upward. Buyers are evaluating total cost of ownership more rigorously, weighing initial equipment cost against staff injury reduction, sling replacement frequency, and maintenance overhead. Third, the market sits at the intersection of clinical safety mandates and operational efficiency pressures. Manufacturers must satisfy rigorous safety expectations while delivering equipment that minimizes caregiver strain and fits within constrained facility footprints. These tensions create both friction and opportunity: companies that navigate them with clear product architecture, service design, and commercial models are better positioned to command premium positioning and repeat business.
Core Drivers Reshaping the Market
Technological innovation is moving beyond basic lifting mechanics into integrated mobility support. Next-generation mobile floor lifts are being engineered for enhanced maneuverability, quicker patient attachment, and smoother floor-to-transfer transitions. Recent product introductions highlight this shift: in April 2025, a major European supplier launched an upgraded mobile patient floor lift designed to improve responsiveness in tight care environments; in July 2025, a U.S.-based producer announced a new line of eco-friendly patient lift slings, signaling that consumables and accessories are becoming strategic differentiators rather than commodity afterthoughts. These developments matter because they directly affect caregiver workflow, sling turnover costs, and user acceptance. Equipment that reduces setup time, supports single-caregiver operation, and integrates compatible sling systems can alter purchasing logic by lowering hidden operational burdens.
Policy and regulatory conditions continue to shape both market access and product design. Patient lifts are recognized under durable medical equipment benefit frameworks, with associated billing codes that influence reimbursement pathways in public and private payer systems. This reimbursement architecture creates a baseline of demand in covered care environments, but it also ties adoption to documentation, coding accuracy, and procurement compliance. On the safety side, manufacturers are expected to maintain sling compatibility, provide operator training, and address adverse event reporting where applicable. Regulatory attention to field safety corrective actions and post-market surveillance increases the cost of quality systems but also raises the barrier to entry for under-resourced competitors. For commercial teams, regulatory fluency is no longer a back-office function; it is a market-facing capability that affects product messaging, service contracts, and international expansion feasibility.
Demand-side behavior is shifting as care delivery moves closer to patients’ homes and as staffing constraints persist across healthcare environments. Facilities are seeking equipment that enables safer transfers with fewer personnel, while families and home-care providers prioritize ease of use, portability, and caregiver ergonomics. The result is a widening preference for mobile and portable solutions that can transition across rooms, care sites, and ownership models without major infrastructure changes. This preference favors manufacturers that can offer compact designs, intuitive controls, and support ecosystems that extend beyond the point of sale into training and sling management.
Supply chain and cost structures are also in flux. Aluminum and steel remain the dominant structural materials, and some frames incorporate antimicrobial coatings to support hygiene protocols in high-turnover settings. Material selection affects weight, durability, transport costs, and end-user perception, especially where infection control is a procurement requirement. At the same time, labor cost dynamics are influencing product specifications: features that enable single-caregiver operation, such as dynamic positioning assistance and quick-connect spreader bars, are increasingly valued because they reduce reliance on multiple staff members for routine transfers. In practical terms, equipment that lowers caregiver physical load can justify higher upfront cost when evaluated against injury risk, turnover, and workflow continuity.
Competitive Landscape and Differentiation Paths
The competitive field blends global incumbents, regional specialists, and broad-line medical equipment distributors. Leading firms typically compete on a combination of product breadth, safety documentation, service coverage, and channel relationships. Some emphasize modular lift families that span hospital, nursing home, and home care use cases, allowing procurement teams to standardize equipment across departments or sites. Others differentiate through portability, bariatric capacity, or sling ecosystems designed to simplify compatibility and replacement. A few players focus on ceiling-mounted and hybrid transfer systems, while mobile patient lifts remain the core battleground for companies targeting environments where permanent installation is impractical or cost-prohibitive.
PW Consulting Health Care Research Center
Strategic positioning varies in ways that matter for both incumbents and entrants. One common approach is to build integrated portfolios that pair the lift with slings, training, and maintenance services, thereby shifting the value proposition from unit price to operational reliability. Another is to pursue geographic expansion through distribution partnerships that accelerate market access without requiring full local manufacturing footprints. A third is to target specific care scenarios, such as bariatric transfers or home-based mobility support, where specialized features can command stronger margins and deeper customer loyalty. These paths are not mutually exclusive, and the most resilient players often combine a credible core product line with selective specialization and a service layer that reduces total cost of ownership for the buyer.
Stairlift Market
Market structure is evolving through a mix of consolidation and fragmentation. On one side, larger organizations benefit from broader portfolios, stronger compliance systems, and the ability to amortize service and training investments across larger installed bases. On the other side, smaller manufacturers continue to enter or expand in targeted segments by offering competitive pricing, faster feature iteration, or region-specific support. Trade exposure, new product showcases, and regional medical exhibitions indicate that visibility and channel presence remain important, especially in markets where procurement decisions are influenced by hands-on demonstration and local service responsiveness. The likely outcome over the next several years is not a single dominant architecture, but a layered competitive environment in which scale players defend institutional share, specialized players capture high-value niches, and distribution networks mediate access across regions.
Forward Outlook: Three Trends Shaping the Next 3–5 Years
The first trend is the widening prioritization of single-caregiver, ergonomically optimized transfer equipment. As staffing constraints continue and safety expectations rise, buyers will increasingly favor lifts that reduce the number of personnel required for routine transfers while maintaining patient comfort and stability. This trend favors designs that integrate intuitive controls, quick patient attachment, and compatible sling systems. Commercial opportunity lies in packaging these capabilities with training and replacement-part support, because the operational payoff often depends as much on correct use as on hardware specifications. The associated uncertainty is regulatory and clinical: safety documentation, adverse-event monitoring, and sling compatibility must remain robust, or the efficiency gains can be eroded by compliance friction or user error.
Lift Chair Market
The second trend is the growth of decentralized care and the corresponding demand for portable, multi-environment lifts. Hospitals, nursing facilities, and home-care providers are all seeking equipment that can move easily between rooms, wards, and settings without major infrastructure investment. This creates opportunity for manufacturers that can deliver lightweight yet durable frames, reliable maneuverability, and accessories that adapt to varied care contexts. It also suggests a longer-tail revenue stream through consumables and service contracts, since portable equipment tends to generate more frequent sling turnover and maintenance interactions. The risk side of this trend involves price sensitivity in non-institutional segments and the challenge of maintaining consistent quality across broad distribution networks.
The third trend is the increasing role of product ecosystems rather than isolated units. Reimbursement structures, safety expectations, and total-cost-of-ownership evaluations are nudging buyers toward solutions that include compatible slings, training, and service guarantees. Companies that treat consumables, operator education, and post-sale support as core elements of the offering can differentiate more effectively than those competing strictly on hardware price. The opportunity is to build recurring value through sling programs, preventive maintenance, and training packages that reduce injury risk and improve equipment utilization. The uncertainty is that ecosystem value must be demonstrable; if training and service are perceived as optional add-ons, they may not earn the pricing power or loyalty that strategic positioning requires.
Strategic Implications by Decision-Maker Type
For manufacturers, the priority is to align product architecture with the way buyers now evaluate mobility equipment. That means designing for single-caregiver usability, sling compatibility, and portability while reinforcing safety documentation and field-support capabilities. Product roadmaps should treat consumables and accessories as strategic levers, not peripheral SKUs, because sling compatibility and replacement logistics influence both satisfaction and long-term cost perception. It is equally important to strengthen service and training offerings in ways that can be quantified by customers, since total cost of ownership arguments will increasingly decide competitive outcomes in institutional and multi-site procurement. Companies expanding internationally should assess regulatory readiness, distribution density, and the ability to provide consistent post-sale support, as these factors often determine whether a product gains traction beyond a pilot adoption.
For investors, the market presents a multi-layered opportunity set rather than a uniform growth story. The most durable value creation is likely to come from firms that combine defensible safety and compliance capabilities with service-led revenue, sling and accessory ecosystems, and distribution that reaches both institutional and home-care endpoints. Due diligence should focus on installed-base economics, sling replacement cycles, training and service attachment rates, and exposure to reimbursement or procurement shifts in key regions. Valuation narratives that rely solely on unit volume growth risk overlooking the operational and regulatory variables that shape margin durability. In practice, the strongest candidates are those that can demonstrate a clear path to recurring revenue, differentiated use-case coverage, and credible responses to safety-related scrutiny.
For procurement leaders and care operators, the practical mandate is to evaluate mobile patient lifts through a broader operational lens. Selection criteria should incorporate caregiver workflow impact, sling compatibility across product lines, training requirements, maintenance availability, and the true cost of consumables over the equipment’s service life. Standardization can deliver procurement efficiencies, but it should not come at the expense of application fit; facilities with mixed care environments may need a small set of well-chosen lift types rather than a single universal solution. Service contracts and user training should be treated as core purchasing considerations, because improper use or delayed support can negate the safety and efficiency benefits that justify the investment. Where home-care or cross-site mobility is part of the strategy, portability, setup simplicity, and field support become especially decisive.
Closing Perspective
The mobile patient lift market is entering a period in which growth is increasingly tied to how well companies address safety, workflow, and total cost of ownership rather than to volume expansion alone. The combination of regulatory expectations, reimbursement pathways, staffing constraints, and decentralization of care is reshaping demand patterns and rewarding firms that can deliver integrated, usable, and supportable solutions. Over the 2026–2032 window, the strategic advantage will likely accrue to organizations that treat product design, consumables, training, and service as a coherent system, while maintaining the compliance rigor and field responsiveness required in safety-sensitive environments. Decision-makers who align their portfolios, investment theses, and procurement criteria with these dynamics will be better positioned to capture value as the market moves toward 557 million USD and beyond. For teams that require granular segmentation, region-specific procurement patterns, pricing architecture, and customized scenario planning, the full research report provides the deeper dataset and structured analysis needed to translate these directional trends into precise operating decisions.
For detailed analysis of this topic, please visit the official page: Mobile Patient Lifts Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


