



Benzaldehyde Market: Why Asia Pacific Growth Surpasses the 5% CAGR

Benzaldehyde Market: Navigating Strategic Shifts and Commercial Opportunities in a Concentrated Landscape
The global benzaldehyde market has demonstrated steady expansion over the past five years, moving from approximately 250 million USD in 2020 to 325 million USD in 2025. With a projected compound annual growth rate of 5.0 percent across the 2026-2032 forecast window, the sector is expected to reach 457 million USD by 2032. This trajectory reflects a market that is not merely growing but structurally evolving under the influence of regional capacity shifts, grade differentiation, and end-use diversification. For executives and investors, the numbers tell only part of the story. The real strategic value lies in understanding how supply chains are reorganizing, where regulatory pressure is reshaping procurement behavior, and which segments will capture disproportionate margin improvements.
Market Snapshot and Structural Realities
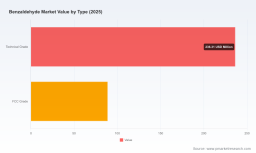
Benzaldehyde operates within a tightly concentrated competitive environment. The top three players control roughly 65 percent of market share, while the top five account for 80 percent. This concentration is not accidental; it reflects the technical barriers associated with producing consistent high-purity grades, the capital intensity of oxidation-based manufacturing routes, and the long qualification cycles required by pharmaceutical and flavor-and-fragrance buyers. At the same time, the market spans multiple grade categories and application domains, creating a layered competitive dynamic where volume leadership and specialty positioning often follow different logic paths.
Paraformaldehyde Market
Regional revenue distribution highlights the continued weight of Asia Pacific, supported by expanding chemical manufacturing infrastructure and export-oriented production. North America and Europe maintain substantial demand bases, particularly for higher-purity and specialty grades tied to regulated applications. Latin America and the Middle East/Africa region represent smaller but growing pools of demand, often linked to localized agrochemical and industrial consumption. The structural takeaway is that geography matters less as a simple volume divider and more as a lens into differing procurement standards, logistics costs, and regulatory exposure.
Key Challenges and Inflection Points
- Raw material price volatility and margin compression. Toluene feedstock fluctuations have repeatedly influenced benzaldehyde production economics, with downward movements in select quarters failing to fully offset broader cost uncertainty. When feedstock ranges remain wide and regional pricing diverges, manufacturers face difficult choices between absorbing cost pressure and renegotiating customer terms.
- Regulatory scrutiny on safety and exposure. Benzaldehyde has entered evaluation frameworks for suspected mutagenic effects under wide dispersive use and consumer exposure scenarios. As regulatory agencies increase their focus on substance evaluation, companies will need to invest in documentation, exposure assessment, and possibly reformulation or handling controls for certain downstream markets.
- Grade qualification and supply chain complexity. The market is not homogeneous. Different applications demand different purity profiles, contaminant limits, and traceability standards. Qualification barriers can slow new supplier entry, but they also create vulnerability for buyers who rely on narrow supplier bases or single-site capacity.
Key Drivers Shaping Market Direction
Feedstock Dynamics and Cost Structure Realities
Benzaldehyde production economics remain closely tied to toluene pricing and the efficiency of oxidation or related conversion routes. In 2025 and into 2026, toluene spot prices for industrial-grade material have moved within a broad band, with regional variations that complicate cross-border cost comparisons. For producers operating integrated sites, this environment can create relative stability if feedstock sourcing is secured under favorable terms. For traders and smaller-scale suppliers, however, volatility can erode competitiveness and widen the gap between in-house production economics and imported material pricing.
The strategic implication is that cost leadership is increasingly a function of site selection, feedstock contracting, and conversion efficiency rather than sheer scale alone. Companies that can smooth input variability through long-term supply arrangements, alternate feedstock strategies, or process optimization are better positioned to protect margins during periods of price dislocation.
Regulatory and Compliance Environment as a Market Filter
The regulatory landscape is adding both friction and differentiation. Substance evaluation activities under broad European frameworks have placed benzaldehyde on review agendas related to potential mutagenic effects and consumer exposure. While classification outcomes and mitigation requirements can take time to materialize, the mere presence of such reviews influences buyer risk calculations. Procurement teams in flavor, fragrance, and pharmaceutical applications often respond by tightening documentation requirements, requesting additional quality assurance, or diversifying suppliers to reduce exposure to any single regulatory outcome.
Worldwide Natural Cinnamic Aldehyde Market
At the same time, tariff and trade classification stability in some markets can provide a measure of predictability. With certain Harmonized Tariff Schedules maintaining existing treatment for benzaldehyde in recent updates, cross-border trade has not faced new duty shocks in those channels. This matters because stable trade classification helps preserve the economics of specialized exports and supports multi-site supply strategies that rely on predictable landed-cost assumptions.
Demand-Side Evolution Across End-Use Categories
Demand for benzaldehyde is being shaped by application-level trends rather than uniform growth. In flavor and fragrance, aromatic aldehydes continue to occupy important roles in fragrance building and specialty aroma chemistry, where purity and consistency are paramount. In pharmaceuticals, benzaldehyde serves as a valuable intermediate, with demand influenced by downstream synthesis requirements, quality expectations, and the pace of new drug development pipelines. In agrochemicals, end-use growth reflects broader crop protection and formulation activity, where specification requirements can differ significantly from personal care or food-related applications.
Food and beverage usage, along with dyes and coatings, adds further diversification. What connects these segments is not identical growth speed, but the increasing preference for suppliers who can demonstrate reliable grade control, batch-to-batch consistency, and transparent documentation. Buyers are less interested in generic availability alone; they are looking for partners who reduce technical and compliance risk across the value chain.
Capacity Realignment and Competitive Expansion
Recent capacity actions illustrate how supply-side players are responding to structural demand. In mid-2025, one major producer flagged off the first consignments from a newly commissioned chlorotoluene oxidation plant with dedicated capacity intended for pharmaceutical, fragrance, and agrochemical applications. This type of expansion signals a clear strategic intent: to secure dedicated volume for regulated and higher-margin segments rather than compete solely on commodity throughput.
Such moves matter because they alter regional supply flexibility and can shift the balance between self-production and imports for certain buyers. When new capacity enters the market with a clear application focus, it can tighten supply for specialty grades in the near term while also creating opportunities for customers seeking qualified alternatives. Over time, these expansions contribute to a market where competitive advantage is increasingly defined by application alignment and reliability, not only by price.
Competitive Landscape and Strategic Positioning
Differentiation by Grade, Application, and Footprint
The competitive field includes established producers with broad intermediate portfolios, specialty suppliers centered on high-purity aroma and pharmaceutical grades, and export-oriented manufacturers building supply chains for international buyers. Some companies have built their positioning around specific oxidation routes and dedicated capacity, particularly in India, where multiple manufacturers serve pharmaceutical, flavor, fragrance, and agrochemical sectors with export-focused logistics. Others operate with multi-site manufacturing across Europe and North America, using scale and regional proximity to support intermediate supply and specialty chemical demand.
A distinct segment of the market is defined by brand-oriented or purity-focused supply for aroma chemicals and high-specification applications. Suppliers in this category often compete on consistency, documentation, and technical support rather than on volume pricing alone. This segmentation creates a dual competitive structure: one lane where capacity and feedstock economics dominate, and another where qualification, traceability, and application expertise drive preference.
Strategic Advantages of the Leaders
- Application-aligned capacity. Companies that dedicate production to specific downstream markets reduce cross-contamination risk and simplify qualification processes for buyers with strict requirements.
- Multi-region manufacturing. A broad manufacturing footprint can help balance regional feedstock conditions, shorten delivery lead times, and mitigate logistics risk for key customers.
- Grade specialization. Suppliers focused on high-purity fragrance and pharmaceutical grades can command stronger customer stickiness when they consistently meet tight specification and documentation standards.
- Export-oriented supply chain design. Manufacturers built around international distribution can serve buyers seeking alternative sourcing options, particularly when qualified capacity is added in regions with growing export infrastructure.
Market Evolution: Consolidation, Diversification, and Entry Dynamics
The market appears to be moving along two parallel paths. On one hand, concentration among leading suppliers suggests ongoing advantages for established players with qualified capacity, strong regulatory documentation, and long-standing customer relationships. On the other hand, the presence of multiple regional producers and export-focused suppliers indicates continued potential for fragmentation in commodity-grade channels and in applications where qualification cycles are shorter or specification demands are less stringent.
New entry remains challenging but not impossible. The barrier is not simply capital; it is the time required to win customer trust in regulated segments, establish reliable quality systems, and navigate regional compliance expectations. As a result, the most likely competitive shifts are not dramatic disruption events but incremental realignments: capacity additions that favor certain grades, regional sourcing changes that alter logistics economics, and supplier diversification by buyers seeking resilience in qualification and continuity.
Outlook and Emerging Opportunities for 2026-2032
Trend 1: Specialty and High-Purity Grades Will Capture Disproportionate Value
As regulatory attention and application requirements intensify, the market’s value distribution is likely to tilt further toward specialized grades. Pharmaceutical, flavor, and fragrance buyers typically prioritize consistency and documentation over price alone, making high-purity supply a structurally defensible position. Producers that can combine dedicated capacity with robust quality systems and clear traceability will be best placed to benefit from this shift. The commercial opportunity lies not only in selling material, but in becoming a lower-risk link in the buyer’s supply chain.
Trend 2: Regional Supply Rebalancing Will Create Sourcing Opportunities and Risks
Capacity expansion in key production regions, combined with ongoing feedstock variability, will continue to reshape regional supply dynamics. For buyers, this creates opportunities to negotiate alternative sourcing routes, reduce dependence on single suppliers, and align procurement with logistics and tariff stability. For producers, it creates opportunities to capture demand from customers seeking qualified regional alternatives or export-grade reliability. The risk is that rapid capacity changes can temporarily distort availability, particularly for specific grades, making scenario planning essential for procurement and production planning.
PW Consulting
Trend 3: Compliance and Documentation Will Become Competitive Differentiators
Substance evaluation activity and broader regulatory focus are likely to increase the importance of compliance readiness. Companies that proactively strengthen documentation, exposure-related data, handling guidance, and quality assurance will be better positioned to retain customers who are managing regulatory uncertainty. This trend converts compliance from a cost center into a market-access tool. The uncertainty lies in the pace and outcome of regulatory reviews, which can vary by region and use case, making flexibility and transparency more valuable than rigid long-term assumptions.
Strategic Recommendations for Decision-Makers
For Manufacturers and Producers
- Invest in grade-specific capacity and quality systems that match the documentation and consistency needs of pharmaceutical, flavor, and fragrance customers. Application-aligned production can reduce qualification friction and improve retention in higher-value segments.
- Strengthen feedstock and cost resilience through contracting, process efficiency, and site-level optimization. In a volatile input environment, margin protection often depends on operating discipline as much as on pricing strategy.
- Prepare compliance and technical documentation as a market-facing asset. Clear safety data, traceability, and usage guidance can reduce buyer concern and support expansion into markets with higher regulatory scrutiny.
For Investors and Strategic Buyers
- Evaluate exposure to both volume-driven and specialty-driven business models. Scale advantages matter, but grade differentiation and customer qualification often determine margin durability.
- Assess regional supply dependency and logistics risk. A supplier’s geographic footprint, export capability, and feedstock sourcing approach can materially affect continuity and landed cost stability.
- Monitor regulatory developments as part of valuation and sourcing decisions. Changes in evaluation status, regional handling expectations, or documentation requirements can influence demand patterns and supplier preference over time.
For Procurement and Supply Chain Leaders
- Diversify qualified suppliers where application requirements permit, especially for critical fragrance, pharmaceutical, and agrochemical uses. Qualification lead times mean that supplier flexibility should be built before disruption occurs.
- Align grade selection with actual end-use risk and specification needs. Over-specifying can add unnecessary cost, while under-specifying can create compliance or performance exposure.
- Use feedstock and tariff stability as part of sourcing decisions. Where trade classification remains unchanged and regional pricing is predictable, it can support more efficient cross-border sourcing strategies.
The benzaldehyde market is entering a phase where growth is increasingly tied to differentiation, compliance readiness, and regional supply architecture rather than to broad volume expansion alone. For companies operating in this space, the most valuable moves will be those that reduce buyer risk, improve grade reliability, and align production with the applications that reward consistency and documentation. For organizations seeking a deeper look at segment-level sizing, regional dynamics, competitive benchmarks, and tailored procurement or expansion scenarios, PW Consulting’s full research report provides the detailed breakdowns and structured scenario analysis needed to support specific strategic decisions.
For detailed analysis of this topic, please visit the official page: Benzaldehyde Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


