



ACSR Cable Market 2026-2032: Why 3.8% CAGR Masks Regional Shifts

ACSR Cable Market: Strategic Trends and Commercial Opportunities in Overhead Power Transmission
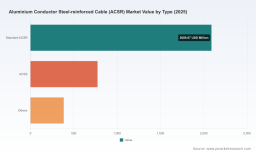
The global market for Aluminium Conductor Steel-reinforced Cable (ACSR) is entering a phase of measured expansion shaped by infrastructure renewal, technological modernization, and evolving procurement dynamics. After navigating volatility in the early 2020s, the segment has stabilized and is projected to grow at a compound annual rate of 3.8% through 2032, rising from an estimated 2025 valuation of USD 3.25 billion to over USD 4.19 billion by the end of the forecast period. This trajectory reflects a steady alignment between grid investment cycles, conductor material innovation, and regulatory frameworks that increasingly prioritize system resilience and thermal performance. For executives navigating transmission and distribution planning, the ACSR market no longer functions as a commodity-driven space; it operates as a strategic input layer where material selection, supply continuity, and project execution timelines directly influence balance sheet outcomes.
Medium Voltage Cable Market
Historical revenue patterns reveal a market that absorbed pandemic-era disruptions, reacted to raw material price swings, and gradually recovered as transmission planning gained momentum. The 2022 dip was followed by a sustained uptrend as utilities and transmission developers resumed backlog work, replaced aging infrastructure, and expanded interregional connections. Current pricing environments and project pipelines reinforce the expectation that demand will continue appreciating, though the path upward will be uneven and highly sensitive to permitting velocity, steel and aluminum cost cycles, and regional capacity constraints. The overarching narrative is one of consolidation around higher-performance specifications, longer lead times for large utility procurements, and a growing premium on suppliers that can deliver both material consistency and project-ready logistics.
Market Snapshot and Structural Pressure Points
At a macro level, the ACSR market demonstrates mature but resilient characteristics. Growth is not propelled by explosive volume expansion; rather, it is driven by replacement programs, incremental transmission build-outs, and a gradual shift toward conductors that balance ampacity, sag, and tensile requirements under changing climate and load conditions. In this environment, the market’s direction is defined less by unit price competition and more by the ability of participants to align manufacturing throughput with utility project schedules, mitigate input cost variability, and meet increasingly stringent technical standards.
Aluminum Wire Rod Market
Several structural pressure points are reshaping decision-making across the value chain. First, the tension between legacy conductor specifications and advanced high-temperature low-sag alternatives is intensifying. Utilities are evaluating whether to continue deploying conventional ACSR in routine rebuilds or to integrate higher-temperature conductors where thermal limits and load growth create near-term constraints. Second, raw material fluctuation remains a persistent variable. Conductor pricing has moved within a wide band over recent years, creating margin pressure for manufacturers and budget uncertainty for project developers, particularly when contract structures lag behind input-cost movements. Third, lead-time reliability is becoming a competitive differentiator. Transmission construction is capital-intensive and schedule-sensitive, and any disruption in conductor supply can cascade into broader project delays and cost escalation. These dynamics are not isolated risks; they are structural realities that determine which organizations capture margin stability and which are exposed to volatility.
PW Consulting
Key Demand Drivers Redefining the ACSR Landscape
Technological evolution is one of the most consequential drivers in the ACSR market. While core conductor architecture has remained broadly consistent, incremental improvements in metallurgical control, corrosion resistance, and strand configuration are influencing specification preferences. At the same time, the broader conversation around advanced conductors is shifting procurement criteria. Regulatory guidance increasingly expects utilities to consider upgraded conductor technologies during interconnection and system planning evaluations, which expands the competitive perimeter beyond standard ACSR and raises the strategic importance of conductor performance data, testing documentation, and application engineering support. For manufacturers, this creates an opportunity to move from transactional supply relationships toward solutions-oriented engagement, where technical advisory capabilities and compatibility with higher-temperature operating regimes become differentiators.
Policy and regulatory environments further accelerate change. Standards governing conductor specifications continue to anchor interoperability and quality expectations, ensuring that products meet consistent mechanical and electrical requirements across jurisdictions. Simultaneously, market rules in several regions are nudging utilities toward more disciplined evaluation of transmission alternatives, including conductor upgrades as part of interconnection and capacity planning. Permitting and interconnection processes remain complex, but where regulatory clarity improves, project pipelines tend to stabilize, which benefits suppliers that can forecast demand and maintain production alignment. In practical terms, policy dynamics are reducing some of the ambiguity that historically delayed capital deployment, while also raising the bar for technical documentation and compliance readiness.
Demand-side behavior is changing on both the utility and industrial fronts. Transmission and distribution operators are prioritizing asset renewal and reliability improvement as legacy lines face increased loading, weather stress, and aging infrastructure. At the same time, industrial and utility customers are pushing for supply continuity and specification consistency, not merely lowest-cost availability. Procurement teams are increasingly evaluating total installed cost, lead-time assurance, and the ability to support project-specific conductor requirements. This is particularly visible in regional transmission rebuilds and line replacements, where conductor choice must align with span conditions, terrain, and expected load growth. The shift toward outcome-based evaluation favors suppliers that can combine manufacturing scale with application expertise.
Supply chain and cost structure dynamics remain central to market performance. Conductor pricing volatility has introduced a need for more flexible commercial structures and stronger input hedging strategies. Production continuity also depends on access to consistent aluminum and steel inputs, operational discipline in drawing and stranding processes, and logistics capacity that can move large conductor reels to project sites without delay. Organizations that have invested in integrated supply planning, inventory buffers for critical programs, and transparent cost communication are better positioned to manage margin exposure. Conversely, companies reliant on reactive sourcing or fragmented logistics face greater sensitivity to disruptions. The broader implication is that cost management in the ACSR market is increasingly a function of operational resilience and commercial design, not just manufacturing efficiency.
Competitive Positioning and Evolving Market Structure
The competitive landscape spans established North American and European manufacturers, significant Indian production capacity, and growing Chinese participation. This geographic diversity shapes both pricing dynamics and supply resilience. Large incumbent manufacturers typically compete on production scale, specification breadth, utility relationships, and the ability to support transmission and distribution programs across multiple voltage classes and conductor variants. Their strategic advantage often lies in consistent product quality, documentation rigor, and the capacity to manage large-volume commitments for utility rebuilds and new transmission projects. In practice, this means incumbents are not only selling conductor material; they are selling schedule certainty, technical compatibility, and reduced execution risk.
Mid-tier and regional suppliers play a complementary role by offering responsiveness, localized service, and flexibility for specialized or smaller-scale procurements. In several markets, these players have built advantage through closer proximity to project sites, shorter delivery cycles, and the ability to accommodate bespoke specification requests. Their growth trajectory often depends on maintaining technical credibility while managing cost structures efficiently, especially when input prices fluctuate and competitive pressure on price intensifies. Across the board, the market is not consolidating into a single dominant model; instead, it is stratifying into segments where scale, service proximity, and technical support each create distinct value propositions.
Recent project activity illustrates how ACSR continues to anchor practical transmission execution. Completed installations and line rebuilds involving selected ACSR conductor sizes demonstrate that conventional conductors remain central to utility work, particularly where span geometry, mechanical requirements, and cost considerations support their use. At the same time, these projects highlight the operational importance of product availability and installation readiness. When conductor supply aligns well with construction schedules, project teams reduce rework, limit idle crew time, and maintain cost control. When supply is disrupted or specifications are inconsistent, the downstream consequences become visible quickly in both timeline and budget. This operational reality reinforces why procurement and engineering teams are paying closer attention to supplier reliability and quality assurance.
Market evolution is also being influenced by standards adherence and the broader push for interoperability. Specifications that define conductor performance characteristics continue to serve as a baseline for product acceptance and cross-border procurement. Companies that maintain tight alignment with recognized standards, and that can demonstrate consistent conformance, tend to earn stronger positioning in utility and industrial purchasing decisions. Over time, this dynamic favors organizations that treat compliance and testing as part of the core offering rather than as a post-production requirement. It also suggests that future competitive advantage will increasingly come from the combination of manufacturing capability, specification credibility, and the ability to support utility engineering teams throughout the project lifecycle.
Forward-Looking Trends and What They Mean for Commercial Strategy
One of the clearest near-term trends is the continued coexistence of standard ACSR with higher-temperature conductor options in utility planning. Rather than a wholesale replacement cycle, the market is moving toward application-specific selection, where project conditions, thermal limits, and economic trade-offs determine the appropriate conductor class. This creates a commercial opportunity for manufacturers and service providers that can offer clear comparative guidance, application data, and procurement flexibility across conductor types. It also means that product portfolios need to be structured around real operating scenarios, not simply catalog breadth. Organizations that can help utilities match conductor choice to load growth, terrain, and system constraints will be better positioned to capture specification share and long-term procurement relationships.
A second trend is the growing premium on supply continuity and execution reliability. As transmission construction intensifies in select regions, the cost of delay becomes more visible and more expensive. Utilities and contractors are likely to place increasing weight on supplier track records, logistics capability, and the ability to honor delivery commitments under volatile input conditions. For manufacturers, this reinforces the value of production planning discipline, strategic inventory postures for high-demand programs, and commercial terms that balance risk between buyer and supplier. For investors and strategic partners, it highlights the importance of evaluating operational resilience alongside revenue potential, because margin stability in this market is closely tied to schedule reliability and cost control.
A third trend is the gradual elevation of technical and regulatory sophistication in purchasing decisions. With standards continuing to anchor product specifications and regulatory expectations increasingly encouraging broader consideration of conductor performance in system planning, suppliers will be judged not only on price but also on documentation quality, testing support, and compatibility with evolving evaluation frameworks. This trend favors organizations that invest in technical service capacity and can translate product characteristics into project-level value. It also suggests that future growth may be disproportionately captured by participants who can position ACSR as part of a broader reliability and capacity strategy, rather than as a standalone commodity line item.
These trends carry both opportunity and uncertainty. On the opportunity side, the market rewards suppliers that can combine consistent quality, predictable lead times, and credible technical support. There is also room for differentiation through commercial flexibility, particularly where utilities seek to manage budget exposure amid fluctuating input costs. On the uncertainty side, raw material price volatility, permitting delays, and shifting project pipelines can alter demand timing and margin expectations. Companies that assume linear growth without accounting for input-cycle sensitivity or regional execution risk may find their forecasts misaligned with operational reality. The practical response is to build planning models that incorporate cost variability, lead-time buffers, and application-specific demand rather than relying solely on aggregate market projections.
Strategic Actions for Manufacturers, Investors, and Procurement Leaders
For manufacturers, the priority is to strengthen the link between production reliability and commercial value. This means aligning capacity planning with realistic project pipelines, maintaining specification consistency across high-volume programs, and developing the technical support needed to engage utility engineering teams early in project design. It also means structuring commercial terms that reflect input-cost variability while preserving customer confidence in delivery timing. Suppliers that can demonstrate predictable execution, clear conformance to standards, and application-focused advisory capability will be better placed to defend margins and expand share in a market where price alone is increasingly insufficient as a differentiator.
For investors and strategic partners, the most relevant question is whether a participant’s operating model can convert market growth into stable returns. Due diligence should focus on production discipline, input sourcing resilience, logistics capability, and the quality of customer relationships in utility and industrial segments. Growth potential should be evaluated alongside execution risk, especially in contexts where project timing depends on permitting, crew availability, and conductor delivery coordination. The market’s expansion outlook is favorable, but value creation will likely accrue to organizations that can manage cost volatility, sustain delivery reliability, and support the technical requirements that modern procurement teams increasingly expect.
For procurement and planning leaders, the strategic imperative is to move beyond short-term price comparison and evaluate total project impact. Conductor selection should account for thermal performance, mechanical suitability, delivery reliability, and the consequences of schedule disruption. Procurement structures that incorporate clear specification requirements, quality documentation, and realistic lead-time planning can reduce downstream execution risk and improve cost predictability. Where feasible, early engagement with suppliers during project design can improve alignment between conductor choice and operational conditions, helping teams avoid late-stage redesigns and delivery mismatches. In this context, precise market intelligence and segment-level data become valuable tools for negotiating commercial terms, validating supply assumptions, and planning for input-cost variability.
The ACSR market is not defined by sudden disruption; it is defined by the cumulative effect of infrastructure needs, technical evaluation, and supply-chain execution. That makes it a market where preparation, specification discipline, and operational reliability translate directly into commercial advantage. For organizations seeking to navigate this environment with confidence, detailed segment data, competitive benchmarking, and application-specific procurement guidance can materially improve decision quality. The next step is to align internal planning with the realities of conductor selection, input-cost variability, and project execution timelines, and to use disciplined market intelligence as the foundation for that alignment.
For detailed analysis of this topic, please visit the official page: Aluminium Conductor Steel-reinforced Cable (ACSR) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


