



Die Casting Machine Market 2026: Cracking the Real Drivers Behind 6.09% CAGR Growth

Die Casting Machine Market: Strategic Trends and Commercial Opportunities in a High-Growth Industry
The die casting machine market has entered a phase of structural acceleration. From a baseline of 2,884.21 million in 2020, the sector expanded to 3,863.83 million by 2025, reflecting sustained demand across automotive, consumer electronics, and industrial applications. Looking ahead, the market is projected to reach 5,826.99 million by 2032, with a compound annual growth rate of 6.09 percent. This trajectory is not merely a reflection of cyclical demand recovery; it signals a deeper reconfiguration of manufacturing priorities, technological maturity, and regional capacity allocation. For executives, investors, and procurement leaders, the market offers meaningful expansion potential, but also demands sharper strategic positioning to navigate intensifying competition and shifting operational expectations.
Aluminum Casting Market
Market Context: Scale, Momentum, and Emerging Friction Points
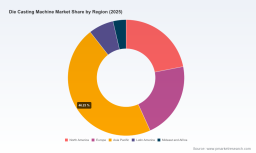
The current market environment is characterized by steady volume growth, increasingly sophisticated equipment requirements, and a gradual shift from commoditized machinery to integrated, intelligence-enabled production systems. Revenue expansion over the past five years has been broad-based, but the pace of growth is beginning to diverge across segments and geographies. While the Asia Pacific region continues to account for the largest share of overall market value, mature markets in North America and Europe are investing in modernization, automation, and higher-precision capacity. This dual dynamic—volume growth in emerging industrial hubs and value-upgrade in established markets—creates a more complex operating landscape than in previous decades.
Despite favorable growth fundamentals, the industry faces several structural challenges that are reshaping decision-making:
- Precision and consistency pressure: End customers increasingly demand tighter tolerances, improved surface quality, and repeatable performance across high-volume production runs. Machines that cannot deliver closed-loop control, stable clamping forces, or integrated quality inspection are losing competitiveness.
- Energy and sustainability expectations: Operators and OEMs are under growing pressure to reduce energy intensity per casting cycle, optimize material yield, and align equipment choices with broader decarbonization goals. This is changing procurement criteria and encouraging electro-mechanical and servo-driven architectures.
- Supply chain fragmentation and lead-time volatility: The complexity of die casting systems—spanning hydraulics, automation, control software, and mold integration—makes equipment delivery sensitive to component availability, engineering bottlenecks, and regional service capacity.
These friction points do not halt growth, but they redefine where value is created. Companies that treat die casting machines as standalone capital equipment are increasingly finding themselves outmatched by suppliers offering integrated process control, faster ramp-up, and lower total cost of ownership.
Core Drivers Reshaping the Market
Technological Innovation and Process Integration
Technology advancement remains the most powerful force in the market. Recent developments illustrate how equipment functionality is expanding beyond basic casting capability. Bühler Group’s Carat series, for example, incorporates nano-coating die technology that enhances aluminum alloy fluidity by 40 percent, enabling more reliable filling and improved lightweight component production. This type of innovation directly addresses one of the persistent constraints in aluminum die casting: balancing fluidity, cycle time, and part quality.
At the same time, intelligent control and automation are becoming baseline expectations rather than premium add-ons. Closed-loop pressure and position control, real-time diagnostic systems, and AI-assisted inspection are increasingly integrated into production lines. Shibaura Machinery’s Hyper Series, equipped with AI vision inspection and a shortened production beat, demonstrates how cycle efficiency and quality verification can be combined within a single ecosystem. Similarly, LK Technology’s large-scale units above 2,800 tons, with real-time closed-loop control accuracy of ±0.01 mm, reflect the industry’s push toward high-tonnage machines that maintain precision at scale.
PW Consulting Automotive & Machinery Research Center
Policy, Standards, and Regulatory Influence
Regulatory and standards frameworks are shaping procurement and engineering decisions in subtle but important ways. Safety and operational standards such as NADCA B152.1-2019 continue to influence machine design, maintenance protocols, and ancillary equipment specifications for high-pressure die casting systems. In parallel, OEM-specific material and heat treatment specifications, including GM Die Material Specifications DC-9999-1 and Ford standard AMTD-DC2010, affect how external casting suppliers design and qualify components. These requirements create a more demanding compliance environment, but they also raise barriers to entry for lower-tier equipment providers and reward manufacturers that can demonstrate repeatable conformance.
Sustainability-oriented expectations are also becoming embedded in purchasing decisions. Equipment that reduces energy consumption, supports scrap reduction, or enables more efficient material usage is gaining preference in tenders and internal capital allocation models. This regulatory and standards-driven pressure is accelerating the shift toward machines that offer measurable efficiency gains rather than incremental capacity increases.
Demand-Side Shifts in End Markets
Demand patterns are changing as downstream industries pursue lighter, more integrated, and more cost-efficient components. Rising demand for lightweight aluminum components is a clear macro trend supporting market growth, particularly in vehicle structures and high-performance consumer products. The automotive sector remains the largest application segment, and its focus on structural part integration is pushing die casting machines toward larger clamping forces and higher throughput stability. At the same time, the 3C industry continues to drive volume demand for precision components, reinforcing the need for machines that can deliver repeatability across complex geometries and shorter production cycles.
Another important shift is the growing interest in large integrated castings, including body and chassis structures that reduce part count and assembly complexity. This trend favors manufacturers with proven capability in ultra-large machines and process control at high tonnage. Ube Industries’ 8,500-ton-class units, which mass-produce 1.8-meter integrated body chassis, illustrate how equipment scale and part integration are converging in practical production environments.
Supply Chain and Cost Structure Dynamics
Cost structures are being reshaped by electrification of machine actuation, digital service models, and the broader push for yield improvement. Electric and servo-driven systems can reduce energy use and improve positioning repeatability, but they also require different maintenance competencies and component supply chains. Companies such as Haitian Plastic Machinery are pursuing direct-drive servo technology with repetitive positioning accuracy of ±0.005 mm, reflecting a wider industry movement toward precision and efficiency in machine architecture.
At the same time, supply chain resilience is becoming a competitive differentiator. Integrated manufacturing capability is increasingly valued because it reduces coordination risk across casting, tooling, and downstream processing. Recent consolidation activity, such as Dynacast’s acquisition of Platinadora Baja to expand integrated manufacturing capabilities, highlights how operators are seeking broader in-house control over the value chain. For machine builders, this means that equipment sales are increasingly evaluated alongside service networks, automation integration, and lifecycle support.
Metal Casting Market
Competitive Landscape and Strategic Positioning
Leaders and Differentiation Themes
The competitive field is defined by a mix of global technology leaders, regional scale players, and specialists focused on specific materials, process types, or application needs. Several distinct strategic positions are visible across the market:
- Scale and high-tonnage leadership: Some manufacturers compete by mastering very large machine architectures and integrated control systems. Ube Industries’ ultra-large two-plate die-casting machines and LK Technology’s large-scale units above 2,800 tons are examples of positioning around high-force capability, precision control, and structural part production.
- Process innovation and material specialization: Other players differentiate through advanced material handling, coating technology, or specialized alloy expertise. Bühler Group’s nano-coating die technology and Frech Group’s pioneering work in magnesium alloy vacuum die-casting show how material-centric innovation can create durable differentiation.
- Digital integration and intelligent operation: A growing group of competitors emphasizes remote diagnostics, IoT-enabled maintenance, and automated quality control. Frech Group’s IoT diagnostic system for 24-hour remote operation and Shibaura Machinery’s AI vision inspection system reflect a shift toward equipment that is managed as part of an intelligent production environment.
- Yield and application-focused engineering: Some manufacturers concentrate on improving output quality for specific end markets. Yizumi’s H-series heavy-duty machines, which achieve 98.7 percent yield for new energy vehicle structural parts, illustrate a focus on outcome-level performance rather than machine specifications alone.
Market Evolution: Consolidation, Integration, and New Entrants
The market is moving toward greater integration at multiple levels. Equipment suppliers are increasingly expected to support automation, inspection, and service workflows, while casting operators are seeking broader capability across molding, robotics, and downstream processing. This is encouraging both vertical integration and selective consolidation. The acquisition landscape, combined with partnerships such as the development of 20,000-ton-class die-casting equipment by Neta and LK Technology, suggests that scale, technology access, and application-specific capability are becoming more tightly linked.
At the same time, the market is not consolidating uniformly. Regional dynamics remain important, and differentiated niches—such as bio-based material die-casting, electric machine architectures, or ultra-large structural casting—continue to attract focused investment. Toyo Machinery & Metal Co., Ltd.’s development of a die-casting machine dedicated to bio-based materials, supported by an Eco-Mode system that reduces energy consumption, shows how specialized innovation can create room for new positioning even in a mature equipment category.
Concentration levels indicate a moderately consolidated market, with leading players holding a meaningful share of revenue. This creates both stability and pressure: established players benefit from brand trust, service networks, and proven large-scale deployments, while challengers must offer clear advantages in precision, efficiency, cost structure, or application fit to gain traction.
Future Trends and Commercial Implications
Trend 1: Precision and Intelligence as Baseline Requirements
Over the next three to five years, precision control, digital monitoring, and integrated quality systems are likely to become standard expectations rather than differentiated extras. Machines that lack real-time control accuracy, repeatable positioning, or connected diagnostics will face increasing resistance in tenders and capital planning. For suppliers, this means investing in control architecture, software, and service integration. For buyers, it means evaluating total performance over the equipment lifecycle rather than focusing solely on initial purchase price.
Trend 2: Larger, More Integrated Casting Solutions
Demand for large integrated components and high-efficiency structural parts is expected to sustain interest in high-tonnage machines and advanced process control. The commercial opportunity lies not only in selling larger machines, but in enabling faster stabilization, fewer defects, and lower assembly complexity for end manufacturers. Companies that can demonstrate reliable large-part production, supported by strong process engineering and service capacity, are well positioned to capture premium demand.
Trend 3: Efficiency, Sustainability, and Material Innovation
Energy efficiency, yield optimization, and material flexibility will become increasingly central to purchasing decisions. Innovations such as nano-coating die technology, electric servo architectures, vacuum die-casting, and eco-mode energy management point toward a market where sustainability and productivity are pursued together. This creates opportunities for equipment that reduces per-part energy use, improves material utilization, or supports new material streams. The main uncertainty lies in the pace of adoption: some operators may prioritize proven reliability over newer efficiency technologies, especially in cost-sensitive environments.
Strategic Recommendations for Decision-Makers
For Machine Manufacturers and Equipment Suppliers
- Prioritize closed-loop precision, digital service capability, and integration with automation and inspection systems. These attributes are increasingly tied to adoption decisions and long-term customer retention.
- Build clear application-facing value propositions. Machine specifications alone are less persuasive than demonstrated yield, throughput stability, and part-quality outcomes in target end markets.
- Strengthen service, training, and parts availability in key regions. Lead-time reliability and local support are becoming important differentiators as equipment complexity increases.
For Investors and Strategic Partners
- Evaluate opportunities based on technology integration and application fit rather than headline capacity alone. Companies that combine scale with precision, efficiency, or specialized material capability are more likely to sustain margin and growth.
- Monitor consolidation signals and partnership activity. Mergers, acquisitions, and joint development agreements can reshape competitive access, especially in large-tonnage and integrated manufacturing segments.
- Pay attention to standards, OEM specifications, and sustainability requirements. These factors influence procurement eligibility and can accelerate demand for higher-compliance equipment.
For Procurement Leaders and Casting Operators
- Assess total cost of ownership, including energy use, yield performance, maintenance requirements, and downtime risk. Precision and efficiency features may justify higher upfront investment if they reduce operating cost and quality variability.
- Align equipment selection with downstream production needs. Integration with robotics, inspection, and molding ecosystems can improve line stability and reduce coordination friction.
- Verify service coverage and training support before committing to large-scale deployments. Complex machines require capable local support to maintain performance over time.
Conclusion
The die casting machine market is advancing on multiple fronts at once: higher precision expectations, larger integrated part production, efficiency-driven machine design, and deeper digital integration. Growth to 5,826.99 million by 2032 at a 6.09 percent CAGR reflects strong underlying demand, but the real strategic question is no longer whether the market will expand. It is which manufacturers, investors, and operators can capture value by aligning equipment capability with application needs, process reliability, and long-term operating efficiency. Companies that treat die casting as a systems challenge—combining machine performance, automation, service, and compliance—will be best positioned to convert market growth into durable competitive advantage.
For decision-makers seeking a more detailed view of segment dynamics, regional value distribution, and company-level positioning, the full market research report provides expanded data and customized analysis. Readers interested in deeper segmentation, competitive benchmarking, and scenario-based planning can access the complete study here .
For detailed analysis of this topic, please visit the official page: Die Casting Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


