



Electrical Steels Market: Decoding What Beyond 5.82 Percent CAGR Means for 2032

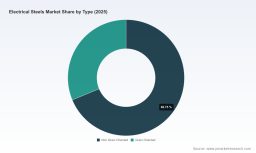
Electrical Steels Market: Strategic Trends and Commercial Opportunities Through 2032
The global electrical steels market has entered a phase of structural expansion, driven by the simultaneous acceleration of electrification, grid modernization, and industrial automation. Valued at approximately $26.5 billion in 2025, the market is projected to reach $39.65 billion by 2032, reflecting a compound annual growth rate of 5.82 percent. This trajectory is not merely a function of cyclical industrial demand; it reflects a fundamental recalibration of how energy is converted, transmitted, and utilized across the global economy. Magnetic steel grades are now embedded in the core architectures of electric mobility, renewable integration, and high-efficiency power systems, making their availability, quality, and cost structure strategic considerations for industrial and infrastructure leaders alike.
Yet growth alone does not capture the complexity of the operating environment. The market is navigating a transition where technological performance requirements, regulatory frameworks, and supply chain geography are converging to reshape competitive dynamics. Companies that treat electrical steels as a commoditized input risk overlooking the material's role as a critical enabler of efficiency gains and regulatory compliance.
Market Landscape and Core Challenges
The market's current size and growth profile mask underlying regional and application-level divergences that are becoming increasingly pronounced. Demand is being pulled by a combination of motor-driven electrification and transformer-led grid upgrades, but the pace and composition of that demand vary significantly across geographies and end-use segments. Asia Pacific continues to command the largest revenue share, reflecting concentrated industrial activity, infrastructure investment, and a rapidly expanding electric vehicle ecosystem. Europe and North America, while smaller in absolute terms, are exhibiting high-growth momentum tied to decarbonization mandates, supply chain localization efforts, and energy security considerations.
On a macroeconomic level, the market is characterized by a moderate degree of concentration. The top three players account for roughly 28 percent of global revenue, while the top five capture approximately 38 percent. This structure suggests that scale, technology access, and geographic footprint remain meaningful differentiators, but it also indicates sufficient fragmentation to allow specialized or regional players to compete on performance, service, or nimble capacity adjustments.
Several intersecting challenges are defining the inflection points that market participants must navigate:
-
Performance-cost trade-offs are intensifying. Higher-efficiency grades, thinner gauges, and lower-loss specifications are increasingly demanded by motor and transformer OEMs, but producing these grades often requires more sophisticated processing, tighter process control, and higher alloying inputs. Suppliers face pressure to deliver premium products without eroding margins in a competitive procurement environment.
-
Regulatory divergence is complicating sourcing strategies. Policies aimed at carbon intensity, import competition, and domestic production are creating asymmetric cost structures across regions. What is a compliant, cost-competitive sourcing decision in one market may become a liability in another, forcing buyers and producers to manage a more fragmented regulatory landscape.
-
Raw material volatility and capital intensity are reshaping margins and lead times. Inputs critical to electrical steel production have experienced price fluctuations that complicate cost planning, while large-scale capacity projects require multi-year commitments. Companies must balance the urgency of meeting demand growth with the financial and execution risk of capacity expansion.
Key Drivers Reshaping the Market
The structural growth of electrical steels is being propelled by four interlocking forces: technical innovation, evolving regulation, demand-side transformation, and supply-side restructuring. Each factor is amplifying the others, creating a market environment where advantage increasingly accrues to organizations that can align product strategy with end-use trajectories and regulatory timelines.
Innovation in Material Performance and Processing
Advances in grain-oriented and non-grain-oriented electrical steel grades are central to meeting the efficiency expectations of next-generation applications. In transformer and grid infrastructure, lower-core-loss grades support reduced energy losses and enable designers to optimize footprint, weight, and thermal performance. In motor applications, particularly traction motors for electric vehicles, thinner non-grain-oriented grades with controlled magnetic properties are helping improve power density and drive efficiency. These gains are not purely material science achievements; they are also enabled by process improvements in rolling, annealing, and coil handling, which influence consistency, yield, and the ability to produce thinner or more specialized products at scale.
Innovation is also shifting the value proposition from volume to specification. Buyers are increasingly selecting grades based on application-specific performance rather than generic material availability. This trend rewards producers that can offer a breadth of grades, consistent quality across thinner gauges, and technical support that helps downstream manufacturers integrate materials more effectively into their designs.
Policy and Regulatory Architecture as a Demand and Cost Catalyst
Regulation is no longer a peripheral consideration; it is becoming a direct driver of both demand and competitive cost positioning. In Europe, carbon-related trade measures and emissions trading frameworks are reshaping the economics of steel imports and incentivizing lower-carbon production pathways. The EU Carbon Border Adjustment Mechanism is expected to impose costs on higher-carbon steel imports beginning in 2026, while updated emissions trading benchmarks are designed to provide more favorable allowance allocation for certain production routes, including pellet-based and direct reduced iron processes. These mechanisms create a dual effect: they raise the relative cost of carbon-intensive imports while also signaling which production technologies may enjoy a more favorable regulatory trajectory.
At the same time, trade remedy actions are influencing regional supply dynamics. In the United States, findings on non-oriented electrical steel imports from China and Taiwan have been part of an ongoing trade enforcement environment, affecting import costs and encouraging sourcing from domestic or alternative supply bases. These actions matter because they alter the price competitiveness of different origin markets and can accelerate efforts to localize production for strategically important grades.
PW Consulting
Demand-Side Transformation Across Mobility, Grid, and Industrial Use
Demand is being reshaped by three broad shifts. First, electrification of transport continues to expand the need for high-performance non-grain-oriented steel in motor applications, where efficiency, weight, and thermal constraints are all critical. Second, grid expansion and modernization are increasing requirements for transformers and associated magnetic components, particularly as renewable generation, storage integration, and distribution network upgrades place new demands on power infrastructure. Third, industrial efficiency programs and equipment replacement cycles are supporting demand for lower-loss steels in motors and inductors, where operational cost savings and regulatory compliance increasingly favor higher-efficiency materials.
These demand shifts are not uniform. They vary by region, by infrastructure spending cycles, and by the pace of adoption in downstream industries. However, the overall direction is clear: electrical steels are moving from being one input among many to a performance-critical material that can determine whether a motor, transformer, or industrial component meets its efficiency and regulatory targets.
Supply Chain Restructuring and Cost Dynamics
Supply chain geography and cost structure are evolving in response to demand growth, trade policy, and the capital requirements of modern steelmaking. Producers are expanding capacity in regions where end-demand is concentrated or where localization offers strategic advantages. For example, capacity expansion initiatives tied to India reflect efforts to serve growing domestic demand more closely, while investments in the United States are intended to strengthen domestic supply for non-grain-oriented grades used in electric vehicle motors and to reduce import exposure. These moves illustrate a broader pattern: capacity is being realigned not only around cost efficiency, but also around market access, supply security, and application-specific demand clusters.
At the same time, raw material volatility remains a practical constraint. Alloying inputs such as ferrosilicon have experienced price swings that can affect production economics and complicate short-term cost forecasting. Combined with the long lead times and high capital commitments of new electrical steel capacity, this volatility emphasizes the importance of flexible procurement strategies, supplier diversification, and scenario planning for both producers and buyers.
Competitive Landscape and Leading Strategies
The competitive arena is shaped by a mix of global integrated steelmakers, regional specialists, and application-focused suppliers. Their strategies differ in emphasis, but several common themes are emerging around grade breadth, capacity positioning, technical differentiation, and geographic alignment with demand.
Global producers with integrated capabilities are leveraging scale and multi-grade portfolios to serve broad customer bases across motors, transformers, and industrial applications. In this group, ArcelorMittal has emphasized non-grain-oriented production for electric vehicle motors and grid applications, including significant investment in a new U.S. facility intended to reach annual capacity of up to 150,000 metric tons beginning in 2027. The move reflects a strategic interest in supporting EV motor supply chains while reducing reliance on imports for a grade that is strategically important in North America.
Non Grain-oriented Electrical Steel (Non-Grain Oriented Electrical Steel) Market
Producers with strong orientation toward grain-oriented electrical steel are concentrating on low-loss grades for power transformers and renewable energy infrastructure. Nippon Steel & Sumitomo Metal Corporation and JFE Steel Corporation illustrate this orientation through advanced grain-oriented grades and capacity strategies that target high-value transformer and infrastructure demand. JFE's joint venture expansion with JSW Steel in India, reaching a combined capacity of 350,000 tonnes per year across two sites with phased scaling through 2027 to 2030, highlights a strategy of pairing technology strength with localized capacity to capture regional demand growth.
Regional and specialty players are pursuing differentiation through grade focus, application expertise, and service-intensive relationships. POSCO has emphasized both grain-oriented and non-grain-oriented offerings, including hyper-thin non-grain-oriented products aimed at electric vehicle traction motors, reflecting the industry's move toward thinner gauges and higher performance in mobility applications. Baosteel remains central to China's large domestic demand base, supplying high-grade electrical steel across electric vehicle motors, smart grid transformers, and industrial applications, while thyssenkrupp Steel and voestalpine serve European demand with portfolios spanning energy transition and industrial motor and transformer applications. Stalprodukt and Cleveland-Cliffs further illustrate the diversity of positioning, from European specialization in transformer and motor grades to U.S. supply of grain-oriented steel for transformers and electric vehicle applications. AK Steel's role as the sole domestic non-oriented electrical steel producer in the United States also underscores how market structure can create distinctive strategic positions tied to national supply considerations.
Several competitive trends are becoming apparent:
-
Capacity is being repositioned around demand clusters. Investments are increasingly tied to specific applications and regions, particularly EV motors and transformer-intensive grid upgrades, rather than to broad undifferentiated expansion.
-
Grade specialization is a growing source of advantage. Producers that can reliably supply higher-efficiency, thinner, or application-specific grades are better positioned to capture value in a market where performance requirements are rising.
-
Localization and supply security are influencing sourcing decisions. Trade measures, carbon-related costs, and regional demand growth are encouraging buyers and producers to consider geographic proximity, domestic availability, and regulatory alignment as part of their sourcing calculus.
The market is not moving toward complete consolidation, but it is evolving toward a landscape where scale, technology, and regional relevance interact more tightly. New entry remains challenging due to capital intensity and technical barriers, but localized capacity, joint ventures, and targeted grade expansion can create meaningful competitive positions, especially where demand growth is strong and supply gaps exist.
Forward Outlook: Three Trends Shaping the Next Three to Five Years
The next several years are likely to be defined by tighter coupling between material performance, regulatory cost structures, and application-driven demand. Three trends are especially important for strategic planning.
Trend One: Efficiency-Critical Grades Will Become the Center of Value Creation
As downstream industries face stronger efficiency expectations and stricter regulatory requirements, the value in electrical steels will increasingly concentrate in grades that deliver measurable performance benefits in motors, transformers, and industrial equipment. Thin-gauge non-grain-oriented products for traction motors and low-loss grain-oriented products for transformers are likely to command renewed attention because they enable design optimization and operational savings. The commercial implication is that competitive advantage will depend not only on volume availability, but on the ability to produce consistent, application-specific grades at the required specifications and scales.
Trend Two: Regional Supply Realignment Will Intensify
Trade remedies, carbon-related import costs, and localized demand growth are likely to continue encouraging regional supply responses. In markets where domestic availability is strategically important, capacity investments and partnerships will be used to reduce exposure to import volatility and to align supply with local application demand. This realignment does not mean globalization disappears; rather, it means that supply chains will become more layered, with different sourcing strategies for different grades, regions, and regulatory contexts. Buyers that rely on a single origin or single grade family may face growing complexity in managing cost, compliance, and continuity.
Trend Three: Carbon and Input Cost Dynamics Will Shape Margin Structures
Carbon-related policy mechanisms and raw material price volatility are likely to remain important variables in cost planning. For producers, the trajectory of emissions-related costs and the relative economics of different production routes will influence investment decisions and product pricing. For buyers, understanding the carbon intensity and origin profile of supply will increasingly intersect with total cost of ownership, especially where imported materials face additional charges or where procurement standards require lower-carbon inputs. The practical risk is that organizations which do not anticipate these cost shifts may encounter margin pressure or sourcing constraints sooner than expected.
These trends create commercial opportunities for organizations that can align product development, sourcing, and investment with the direction of demand and regulation. They also introduce uncertainty: policy implementation details, raw material price paths, and the pace of downstream technology adoption can all alter the timing and distribution of value. Scenario-based planning is therefore essential, particularly when making multi-year capacity or procurement commitments.
Strategic Implications for Decision-Makers
The market's direction suggests that electrical steels should be treated as a strategic materials category rather than a transactional input. The following implications are most relevant for different stakeholder groups.
For Manufacturers and Material Users
-
Design with material performance in mind. Efficiency targets, thermal constraints, and regulatory requirements should be integrated into material selection early in the design process. Where higher-efficiency or thinner-gauge grades offer measurable downstream benefits, the additional material cost may be offset by system-level savings or compliance advantages.
-
Diversify supply by grade and origin. Given regulatory divergence and raw material volatility, multi-source strategies can reduce exposure to price shocks, trade actions, and supply interruptions. This is particularly important for grades that are strategically important but available from a limited number of suppliers in a given region.
-
Invest in technical collaboration with suppliers. Closer engagement with producers can improve grade selection, reduce integration risk, and support consistent quality, especially when working with specialized or thinner-gauge products.
For Investors and Capacity Planners
-
Target application-aligned capacity rather than undifferentiated expansion. The strongest opportunities are likely to be in grades and regions where demand growth is sustained by electrification, grid modernization, and industrial efficiency. Capacity decisions should reflect application trajectories, not just aggregate market growth figures.
-
Factor regulatory cost into investment models. Carbon-related mechanisms, trade actions, and emissions trading dynamics can influence both operating costs and competitive positioning. Investment cases should model a range of regulatory scenarios, especially for supply chains that cross carbon-border or trade-remedy jurisdictions.
For Procurement and Supply Chain Leaders
-
Move beyond unit price to total cost and continuity. In a market where regulatory charges, raw material volatility, and grade specificity matter, procurement decisions should account for tariff exposure, carbon-related costs, reliability of supply, and the strategic importance of the grade to end-product performance.
-
Monitor policy and trade developments as part of routine sourcing risk management. Because trade remedy outcomes and carbon-import costs can change the relative attractiveness of different origin markets, ongoing monitoring is necessary to avoid reactive sourcing decisions.
Conclusion: Where to Focus Now
The electrical steels market is expanding in a context where performance, regulation, and geography are converging to redefine competitive advantage. Growth to the mid-$30 billion range by the end of the decade is supported by strong underlying demand, but the more decisive question for business leaders is not how large the market will become; it is how value will be distributed among those who can deliver the right grades, in the right regions, at a cost structure that accounts for regulatory and input-cost realities.
Companies that act early on grade strategy, supply diversification, and scenario-aware investment are better positioned to benefit from the market's structural shift. For those seeking a deeper look at segment-level demand patterns, regional supply dynamics, and company-specific positioning, a more detailed research briefing can provide the granularity needed to translate these strategic trends into operational decisions. The broader direction is already visible; the next layer of advantage lies in the specifics.
Grain Oriented Electrical Steel Market
For detailed analysis of this topic, please visit the official page: Electrical Steels Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


