



Electric Utility Vehicles Market: Why 6.85% CAGR and Lithium-Ion Shift Change Everything

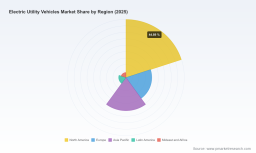
Electric Utility Vehicles Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview and Core Challenges
The electric utility vehicle segment has matured from a niche alternative into a structurally significant market. Total revenue expanded from approximately $13.52 billion in 2020 to $23.86 billion in 2025, reflecting consistent annual growth and deepening commercial adoption across multiple verticals. Forward projections place the market at roughly $25.4 billion in 2026 and climbing toward $38.24 billion by 2032, sustained by a compound annual growth rate of 6.85 percent. This trajectory is not merely a reflection of broader electrification sentiment; it signals a tangible shift in how fleets, facilities, and recreational operators approach mobility economics, maintenance overhead, and regulatory compliance.
Despite the upward momentum, the market faces structural friction that will shape competitive outcomes over the next several years. The first challenge lies in battery chemistry economics and operational range expectations. Lithium-ion platforms, particularly lithium iron phosphate variants, are becoming the default choice for commercial deployments because they lower upfront procurement costs while supporting range extensions beyond forty-five miles. Yet the same chemistry decisions create tension between purchase price, charge cycle longevity, and thermal management requirements. Operators evaluating total cost of ownership must reconcile lower initial expenditures with lifecycle degradation patterns, especially for heavy-duty use cases where duty cycles strain pack durability. The result is a market in which specification choices carry long-term financial consequences, and misjudging application requirements can erode the economic case for electrification.
The second challenge stems from infrastructure readiness and municipal procurement complexity. Electrified roadway pilots, including multi-million-dollar testing corridors with wireless charging installations and extended charging segments, are underway in locations such as Germany and Michigan to validate operational feasibility for heavy utility vehicles. These initiatives demonstrate technical possibility, but they also expose the gap between pilot-scale validation and fleet-wide deployment. Operators must contend with charging access, grid capacity, and route planning constraints that vary significantly by site. Simultaneously, government procurement notices increasingly specify four-wheel-drive electric utility vehicles that meet EPA Tier 4 and CARB standards for municipal and utility fleet deployment. Compliance with these specifications raises the technical bar for suppliers and forces buyers to align vehicle selection with evolving regulatory checklists rather than legacy performance benchmarks alone.
A third challenge is market concentration and the strategic risk it creates for late entrants. The segment remains highly consolidated, with the top three firms capturing roughly 62.4 percent of revenue and the top five reaching approximately 71.2 percent. This concentration rewards scale, established distribution channels, and the ability to meet demanding commercial specifications. It also raises the difficulty of differentiation for new manufacturers unless they bring distinct advantages in platform modularity, retrofit conversion capabilities, or application-specific engineering. Companies that attempt to enter with broadly generic offerings face an uphill battle, while those that target underserved application niches or conversion pathways can find more viable positioning.
Key Drivers of Market Evolution
Technical Innovation and Powertrain Maturation
Powertrain engineering continues to be the primary force reshaping the market’s value proposition. Manufacturers are moving beyond basic electrification toward integrated platform strategies that combine higher-efficiency motors, improved thermal management, and battery architectures tuned to specific duty cycles. Recent updates from John Deere, which refreshed its electric utility vehicle lineup with increased battery runtime and enhanced features showcased at the 2025 GCSAA Conference, illustrate how incremental platform improvements directly address fleet runtime concerns. These enhancements matter because they reduce route interruption, improve uptime predictability, and strengthen the operational argument for electric platforms in demanding environments.
Battery technology is similarly advancing the commercial equation. Lithium-ion batteries and LFP chemistries dominate electric utility vehicle powertrains, with range upgrades to forty-five-plus miles enabling lower upfront costs for commercial users. This combination of extended usable range and reduced entry cost is especially important for fleets that previously hesitated because of range anxiety or high initial expenditure. As range thresholds rise and costs moderate, electric utility vehicles become more competitive against internal combustion alternatives on a total cost basis rather than solely on environmental grounds.
Policy, Regulation, and Incentive Architecture
Regulatory and incentive frameworks are accelerating adoption by reshaping procurement economics and compliance requirements. Government contracts and bids are specifying electric utility vehicles that satisfy EPA Tier 4 and CARB standards, which channels municipal and utility demand toward compliant models and away from legacy platforms. At the same time, incentive programs such as Vermont’s Electrify Your Fleet initiative provide direct support for electric utility vehicle replacements in municipal and business fleets, explicitly tying funding to greenhouse gas emission reduction goals. These mechanisms do more than subsidize purchases; they create procurement pathways that prefer electric options and lower the financial risk for fleet managers making the transition.
Policy momentum also influences design priorities. Because municipal and utility specifications increasingly emphasize environmental compliance, noise reduction, and operational efficiency, manufacturers are tailoring platforms to meet those criteria rather than pursuing generic electrification. This alignment between regulation and product development increases the likelihood that compliance-driven demand will continue to underpin growth, particularly in North America where procurement structures are highly standardized.
Demand-Side Shifts in Commercial and Recreational Use
Buyers are redefining what they expect from utility vehicles as electrification becomes normalized. Commercial operators are prioritizing lower long-term labor and maintenance costs, reduced fuel exposure, and improved site-level air quality. Fleet electrification of municipal and utility vehicles shifts operational maintenance demands, with incentives targeting replacement of internal combustion models to lower long-term labor and fuel expenses. This shift is particularly meaningful for organizations that operate high-utilization fleets, where maintenance downtime and fuel price volatility can significantly affect operating budgets.
Electric Vehicles for Construction, Agriculture and Mining Market
At the same time, recreational and hospitality-adjacent demand is expanding the addressable market beyond traditional industrial applications. Golf courses, resorts, and leisure operators are adopting electric vehicles to improve guest experience, reduce noise, and align with sustainability expectations. This broadening demand base diversifies growth sources and reduces reliance on a single vertical, though it also requires manufacturers to balance differing performance, range, and charging needs across use cases.
Supply Chain Dynamics and Cost Structure Realignment
Cost structure changes are reshaping competitive positioning. As battery supply chains mature and chemistry choices stabilize around proven lithium-ion and LFP options, manufacturers can plan production with greater predictability and lower volatility in key input costs. The transition also alters service economics: fewer moving parts, reduced fuel handling, and simplified maintenance routines change the labor profile of fleet operation. These supply-side improvements support the commercial case for electrification, but they also create a race to the bottom in segments where differentiation is weak. Companies that rely solely on cost competition may find margin pressure intensifying, while those that combine platform efficiency with strong application engineering can preserve value.
Competitive Landscape and Leading Strategies
The market’s competitive architecture is defined by a mix of established utility vehicle specialists, diversified outdoor and agricultural brands, and regional players with strong conversion or modular capabilities. GEM Cars has carved out a focused position in street-legal all-terrain electric utility vehicles and low-speed vehicles, emphasizing fleet electrification through its electric series. This specialization allows the company to appeal directly to municipal and commercial customers that need compliant, purpose-built platforms rather than adapted recreational vehicles.
Polaris Inc. brings a different strategic advantage: the integration of advanced electric powertrains developed through its Zero Motorcycles partnership, deployed across models such as the RZR Pro XD Kinetic and Ranger EV. This powertrain collaboration signals a technology-forward approach that targets performance-conscious utility users and recreational-commercial crossover demand. Textron Specialized Vehicles Inc. competes with a stronger emphasis on commercial fleet solutions and specialized industrial applications, positioning itself where custom configuration and utility-grade durability matter most. John Deere continues to leverage its agricultural and utility brand equity through its Gator series, extending electrification into farm and utility fleet contexts where brand trust and application familiarity reduce adoption friction.
Kubota Corporation adds a construction and farm-grade dimension with its RTV series and expanding electric ranges, appealing to operators who need rugged utility vehicles with a clear path toward electrified options. Alke S.p.A. differentiates through modular electric utility vehicles with enhanced safety and platform features, an approach that supports customization for diverse commercial environments. Club Car remains a strong presence in electric golf, transportation, and utility vehicles, and its expansion into street-legal models for commercial applications shows how an established golf and transport brand can broaden into municipal and facility markets. Kandi Technologies Group focuses on high-clearance electric UTVs for off-road utility use, targeting customers that require greater ground clearance and rugged capability. Groupe Gruau provides a distinct value proposition through utility vehicle conversion and electric retrofit solutions for commercial fleets, an increasingly relevant path for organizations that want to extend the life of existing assets rather than replace them entirely. The Massimo Group is also expanding into electric utility terrain vehicles with debut models planned for 2026, indicating continued entry activity from manufacturers seeking performance and efficiency gains.
PW Consulting Automotive & Machinery Research Center
Recent market activity underscores both product momentum and brand expansion beyond traditional utility vehicle definitions. Kia’s EV9 was named the 2026 Canadian Electric Utility Vehicle of the Year by AJAC and displayed at the Canadian International Auto Show in February 2026, reflecting how larger electric vehicles are gaining recognition in utility-adjacent categories. Jeep introduced the all-electric 2026 Recon SUV as the only fully electric utility vehicle designed to be trail rated, blending recreational utility expectations with electric propulsion. These developments illustrate a broader competitive trend: the boundaries of the electric utility vehicle market are widening as more brands position electric platforms for mixed-use, off-road, and facility-based applications.
Electric Trucks Market
Strategically, the leading companies are pursuing differentiation along several axes. Some emphasize powertrain sophistication and performance credibility to attract buyers who fear electric platforms will underdeliver in demanding conditions. Others focus on compliance, modularity, and application-specific engineering to win municipal, industrial, and fleet contracts. A third group builds value through conversion and retrofit pathways, allowing commercial operators to electrify existing assets where total replacement is financially or operationally impractical. These divergent strategies suggest a market in which multiple legitimate competitive models can coexist, but only if each is anchored in a clear application fit rather than a generic electric vehicle proposition.
The competitive landscape is also evolving through both consolidation pressure and new entry. High concentration advantages the largest players in scale procurement, service networks, and brand trust, but it does not eliminate opportunities for targeted entrants. New manufacturers can compete by addressing niche range requirements, specialized vehicle geometry, or retrofit services that incumbents underserve. At the same time, the widening definition of utility vehicles invites crossover from broader electric vehicle brands, which can intensify competition at the edges of the market while leaving dedicated utility vehicle manufacturers to defend core commercial and industrial segments.
Forward Outlook: Three Trends Shaping the Next Three to Five Years
Trend One: Commercial Electrification Becomes a Total Cost of Ownership Decision, Not a Compliance Purchase
Over the next several years, buying decisions will increasingly center on lifecycle economics rather than regulatory checkbox compliance. As battery range improvements and chemistry maturity reduce upfront barriers, fleet managers will compare electric options against internal combustion alternatives using maintenance labor, fuel exposure, downtime, and site-level operating conditions. This shift favors manufacturers that can document real-world operational savings and provide credible deployment support, while disadvantaging those that rely primarily on environmental messaging. Commercial opportunity lies in packaging vehicles with charging planning, service expectations, and application-specific performance data that make the economic case clear.
Trend Two: Retrofit and Conversion Pathways Gain Strategic Importance
Conversion and retrofit solutions are likely to become more commercially significant as organizations seek to electrify existing fleets without full replacement. Supply chain maturation, incentive structures that reward replacement of internal combustion models, and the desire to manage capital expenditure all support this direction. Companies that can deliver reliable conversion platforms, maintain safety and compliance standards, and integrate electric powertrains into existing vehicle architectures will capture demand from buyers who value flexibility. The strategic risk is that conversion quality and regulatory alignment vary widely, so credible engineering and consistent certification will separate scalable programs from short-lived experiments.
Trend Three: Infrastructure Pilots Move From Validation to Site-Specific Deployment Planning
Electrified roadway experiments and wireless charging installations currently serve as proofs of concept, but the practical value will come from translating pilot findings into site-specific deployment models. As testing expands in locations such as Germany and Michigan, operators will gain better visibility into charging behavior, route constraints, and operational feasibility for heavier utility vehicles. This creates an opportunity for manufacturers and service providers that can help buyers design charging layouts, manage grid interactions, and match vehicle range profiles to actual routes. The uncertainty lies in whether infrastructure investment scales broadly or remains concentrated in selected corridors and demonstration sites, which could limit the pace of heavy-duty adoption in some regions.
Strategic Actions for Decision Makers
For manufacturers, the priority is to anchor platform development in application-specific value rather than broad electrification positioning. This means defining clear target duty cycles, documenting runtime and maintenance advantages, and aligning product roadmaps with compliance requirements that procurement teams now expect. Companies should also evaluate whether modular platforms or retrofit offerings can open additional revenue streams in commercial fleets that need flexibility. Differentiation will increasingly come from engineering credibility, deployment support, and the ability to prove operating savings in realistic conditions.
For investors, the most important question is where durable margin advantage can be sustained as the market scales. Concentration indicates that scale and channel strength matter, but growth also creates room for specialists with strong application fit or conversion capabilities. Due diligence should focus on battery lifecycle economics, compliance readiness, service infrastructure, and the realism of stated range and uptime claims. Capital allocation that favors companies with credible deployment ecosystems and clear use-case targeting is better positioned than capital that chases generic electric vehicle exposure without commercial differentiation.
For procurement leaders and fleet operators, the practical task is to treat electrification as an operational redesign rather than a simple vehicle swap. This includes evaluating route profiles, charging access, maintenance capacity, and regulatory specifications before committing to a platform. Incentive programs and compliance-driven procurement can reduce financial friction, but only when vehicles are matched to actual use requirements. Organizations that build internal competency in deployment planning and lifecycle cost modeling will make better acquisition decisions and avoid overpaying for capabilities they do not need.
Given the pace of product updates, regulatory shifts, and infrastructure experimentation, decision makers benefit from access to detailed segmentation data, competitive tracking, and application-level deployment benchmarks. A complete research view can support more precise planning around battery chemistry choices, regional procurement patterns, vehicle-type demand shifts, and the commercial implications of range thresholds across different operating environments. The full Electric Utility Vehicles Market report provides that deeper segmentation and customized strategic guidance for manufacturers, investors, and procurement teams evaluating their next moves.
For detailed analysis of this topic, please visit the official page: Electric Utility Vehicles Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


