



Solar Control Window Films Market: Strategic Shifts Driving 7.85% CAGR Growth to 2032

Navigating the SolarControl Window Films Market: Strategic Insights for 2026 and Beyond
The solar control window films market stands at a critical inflection point, driven by an convergence of energy efficiency mandates, technological innovation, and shifting consumer expectations. Representing a global revenue base that reached USD 725.5 million in 2025, the sector is projected to expand at a compound annual growth rate of 7.85 percent through 2032, potentially surpassing the USD 1.25 billion mark by the end of the forecast horizon. This trajectory reflects more than incremental growth; it signals a structural evolution in how commercial builders, automotive manufacturers, and end-users approach thermal management, glare reduction, and ultraviolet protection. For executives and investors mapping their next strategic move, understanding the underlying forces shaping this market is no longer optional.
Worldwide Window Films Market
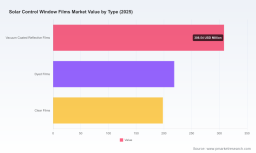
The market's expansion since 2020 has been steady, with revenue climbing from approximately USD 482.75 million five years ago to the current annualized level. Growth has not been uniform across all segments. The Asia Pacific region continues to represent the largest revenue pool, while North America and Europe maintain highly mature, regulation-driven demand environments. In terms of product architecture, vacuum coated reflective films currently command the largest share, followed by dyed films and clear film alternatives, each serving distinct performance and aesthetic requirements. Application-wise, construction remains the dominant end-use sector, with automotive and marine and other specialized applications forming the remainder of the demand base. The competitive fabric is moderately concentrated, with the top three players accounting for just over 52 percent of total revenue and the top five capturing roughly 64 percent, leaving meaningful room for specialized entrants and regional champions to compete on innovation, customization, or localized service models.
Despite the favorable growth outlook, the industry is navigating two structural challenges that will define competitive positioning in the coming years. The first is the tension between premium performance expectations and raw material cost volatility. Polyester and nano-ceramic input prices experienced a modest global decline of 2.1 percent in the short term, reflecting supply chain concentration dynamics in Asia Pacific, yet localized cost pressures persist. In North America, polyethylene terephthalate resin prices climbed by an average of 5 cents per pound through October 2025, constrained by new tariff structures layered onto existing price fluctuations. Manufacturers operating with thin margins or reliant on imported feedstock face a tight balancing act between absorbing input costs and preserving price competitiveness. The second challenge lies in regulatory fragmentation. Standards such as ISO 9050 are sharpening the focus on energy performance metrics, including solar energy transmittance and U-value parameters, while frameworks like the EU F-Gas Regulation and REACH compliance requirements are systematically restricting certain adhesive chemistries. The result is a gradual but irreversible shift toward lower-global-warming-potential formulations, forcing incumbents and new entrants alike to invest in reformulation and testing cycles that extend time-to-market. A third pressure point is the evolving tariff landscape in key import markets. Solar control window films entering the United States from China are subject to Section 301 tariffs ranging from 7.5 percent to 25 percent, depending on the specific HS subheading. This creates a bifurcated sourcing environment where domestic or nearshore production capacity can command a structural cost advantage, while importers must navigate complex classification strategies and potential pass-through pricing resistance from buyers.
Key Drivers Shaping Market Momentum
Technology Innovation and Material Science Breakthroughs
The performance boundary of solar control films is being redrawn through advances in multi-layer nano-technology, ceramic-based coatings, and spectrally selective designs. The shift from traditional dyed or metallic films toward metal-free, infrared-blocking formulations reflects a broader demand for high visible light transmission without sacrificing heat rejection. This is especially relevant in architectural settings where occupants and building managers want glare and thermal control without darkening interiors or compromising natural lighting quality. In the automotive segment, the same performance logic applies: consumers and fleet operators increasingly prioritize cabin comfort and energy efficiency without aesthetic trade-offs.
A concrete example of this innovation trajectory is the July 2025 launch by Lintec Corporation of the BR-50UH RECYCLE 100 line, a solar control window film manufactured entirely from 100 percent recycled PET resin. The product is designed to reduce interior heat gain caused by solar radiation while simultaneously contributing to CO2 emissions reduction. This development matters beyond product-level differentiation. It signals a convergence between performance engineering and circular economy objectives, an alignment that resonates with procurement teams under Scope 3 reporting pressure and with regulators tightening building material sustainability criteria. Companies that can pair thermal performance credentials with verifiable lifecycle benefits are positioned to command price premiums and secure specification wins in green building programs and eco-conscious automotive projects.
Policy and Regulatory Dynamics as Specifier Triggers
Policy is no longer a background variable; it is actively reshaping demand by altering the economics of energy consumption and by defining acceptable material and performance standards. Building codes and energy labeling schemes in mature markets have raised the baseline expectation for fenestration performance, making window retrofit solutions increasingly attractive relative to full glazing replacement. Energy efficiency retrofits, whether driven by corporate ESG commitments or regulatory compliance timelines, create a recurring pipeline of demand for solar control films that can improve interior thermal comfort and reduce cooling loads.
At the same time, regulatory instruments are influencing what can be sold and how it must be validated. The ISO 9050 standard has become a reference point for quantifying solar energy transmittance and U-value parameters, enabling specifiers to compare products on a common performance footing. In parallel, the EU F-Gas Regulation and REACH compliance frameworks are reducing the viability of certain adhesive chemistries, effectively steering the industry toward lower-global-warming-potential alternatives. This dual pressure, performance standardization on one side and chemical reformulation on the other, favors organizations with robust R&D pipelines and testing infrastructure. It also raises the barrier for low-compliance entrants, reinforcing the competitive advantage of established players that can navigate certification cycles efficiently.
Demand-Side Shifts in Construction and Automotive Segments
On the demand side, behavioral and commercial shifts are compounding the impact of policy and technology. In construction, the emphasis on operational carbon reduction and occupant wellness is driving specification decisions toward solutions that improve thermal comfort while minimizing energy intensity. Retrofit activity remains particularly important because it allows building owners to capture energy savings without the disruption and cost of full window replacement. Films that balance heat rejection with visibility are gaining traction in office, healthcare, and hospitality environments where daylight quality directly affects user experience.
PW Consulting Health Care Research Center
In automotive applications, the demand narrative is increasingly tied to electrification and thermal management. Electric vehicles place a premium on minimizing battery drain from cabin climate control, which elevates the value proposition of films that block infrared heat without adding weight or compromising visibility. Fleet operators and OEMs evaluating total cost of ownership are weighing window film upgrades as part of broader efficiency strategies. Meanwhile, consumer preferences in both automotive and residential contexts are tilting toward spectrally selective products that maintain visible light transmission while rejecting unwanted heat and UV radiation. This preference is reshaping purchasing criteria away from price-only comparisons and toward performance-per-unit-area and long-term comfort outcomes.
Supply Chain Realignment and Cost Structure Evolution
Supply chain dynamics are introducing both risk and opportunity. The short-term decline in volatile polyester and nano-ceramic prices, attributed in part to supply chain concentration patterns in Asia Pacific, offers temporary relief for cost-sensitive production planning. Yet the same concentration can amplify disruption risk if regional logistics, trade policy, or environmental constraints shift. In North America, the added cost pressure from PET resin price increases driven by tariff layering has forced manufacturers to reconsider sourcing mixes, inventory buffers, and pricing strategies.
The procurement environment is also being reshaped by trade policy. Section 301 tariffs of 7.5 to 25 percent on solar control window films imported from China into the United States create a clear incentive to evaluate domestic manufacturing partnerships, regional distribution models, or alternative sourcing origins that can mitigate duty exposure. For suppliers, this environment rewards transparency on origin, flexibility in logistics, and the ability to articulate total cost of ownership rather than unit price alone. For buyers, it underscores the value of dual-sourcing strategies and scenario planning around tariff volatility.
Competitive Landscape and Strategic Positioning
Differentiation Themes Among Leading Players
The competitive field is defined by a blend of broad portfolio depth, application-specific specialization, and an accelerating focus on sustainability-linked product attributes. Companies with strong architectural and automotive franchises are leveraging advanced coating technologies to compete on heat rejection, UV protection, and visible light transmission. Multi-layer nano-technology and ceramic-based formulations have become core battlegrounds because they allow manufacturers to claim performance gains without the drawbacks associated with older metallic or purely dyed approaches.
3M continues to emphasize proprietary multi-layer nano-technology and ceramic-based architectural films for heat rejection and UV protection across commercial and residential applications, positioning its portfolio around performance consistency and specification support. Eastman Chemical Company maintains a prominent presence through solar control films marketed under the LLumar and Vista brands, with a focus on architectural and automotive applications and a strong distribution footprint. Saint-Gobain Performance Plastics pursues a distinct angle through its Solar Gard brand, emphasizing advanced coatings that link solar control to energy efficiency and occupant comfort. Avery Dennison Corporation has pushed into metal-free construction with its Encore nanoceramic portfolio, targeting infrared blocking while preserving architectural aesthetics. In Japan, Lintec Corporation has combined performance with circular economy positioning through its BR-50UH RECYCLE 100 line made from recycled PET resin, a move that aligns product innovation with sustainability communication. Madico Inc. emphasizes spectrally selective technology that pairs heat rejection with high visible light transmission across architectural and automotive films, while Johnson Window Films focuses on energy-efficient architectural offerings including the NightVision Series for commercial and residential markets. Garware Hi-Tech Films Limited rounds out the landscape with its Suncontrol series polyester films serving residential, commercial, and automotive applications, highlighting the relevance of regional manufacturing depth in price-sensitive and specification-driven markets.
Market Structure Evolution: Integration, Specialization, and New Entry
The concentration profile, with the top three firms representing a little over half of revenue and the top five around two-thirds, suggests a market that is neither fully consolidated nor highly fragmented. This middle ground allows for both consolidation-driven scale advantages and specialized niche positioning. The recent acquisition agreement by Madico Inc. in February 2026 to acquire Johnson Laminating & Coating and Johnson Window Films illustrates the consolidation impulse, as players seek to combine manufacturing capabilities, broaden product breadth, and strengthen distribution reach within the solar control window films segment. Consolidation can improve capacity utilization, streamline product development, and enhance service consistency, but it also places pressure on smaller competitors to differentiate through technology, customization, or regional responsiveness.
For new entrants and smaller specialists, the path to relevance increasingly runs through performance differentiation and sustainability storytelling rather than price competition alone. Recycled-content films, metal-free infrared-blocking portfolios, and spectrally selective designs that maintain visibility are examples of attributes that can unlock specification wins and justify premium positioning. In parallel, regional manufacturers that can navigate local compliance requirements, offer rapid service, and respond to localized aesthetic or performance preferences can hold their own against global brands in specific markets. The strategic implication is clear: scale matters, but it is no longer sufficient. Differentiation must be anchored in measurable performance, credible sustainability claims, and the operational ability to support installation and warranty expectations.
Forward-Looking Trends and Commercial Implications
Trend One: Performance-Verified, Low-Impact Formulations Become the Baseline
Over the next three to five years, the combination of energy performance standards and chemical compliance frameworks will likely push the market toward formulations that can demonstrate both thermal effectiveness and reduced environmental impact. Products that pair strong solar energy rejection with lower-global-warming-potential adhesives and, where applicable, recycled or lower-footprint substrates will gain preferential treatment in specification processes. This trend creates an opportunity for manufacturers to integrate testing, certification, and lifecycle messaging into their commercial strategy, effectively turning compliance into a differentiator rather than a cost center. The uncertainty lies in the pace and geographic unevenness of regulation; what is standard in one region may lag in another, requiring flexible product architectures and market-specific go-to-market plans.
Trend Two: Retrofit-Driven Demand Accelerates in Construction, Efficiency-Linked Upgrades Grow in Automotive
Construction-driven demand is expected to remain robust as building owners pursue energy efficiency improvements without full glazing replacement. Retrofit films that can be installed with minimal disruption while delivering measurable improvements in thermal comfort and cooling load reduction are well positioned. In automotive applications, the electrification narrative supports continued interest in films that help manage cabin thermal loads, particularly where range and battery efficiency are priorities. The commercial opportunity here is to align product propositions with quantified outcomes, such as reduced cooling demand, improved occupant comfort, or lower energy intensity per square meter of glazing. A key risk is that macroeconomic cycles can slow renovation and fleet upgrade budgets, making it important to maintain a mix of retrofit, replacement-adjacent, and new-build offerings to buffer demand volatility.
Worldwide Commercial Solar Control Glass Market
Trend Three: Supply Chain Localization and Tariff-Aware Sourcing Become Strategic Levers
Trade policy and input cost dynamics are likely to keep supply chain strategy in the spotlight. Companies that can offer transparent origin documentation, diversified sourcing, or regional production are better placed to mitigate duty exposure and respond to buyer concerns about price stability. For buyers, the opportunity lies in structuring procurement to balance cost, compliance, and resilience, potentially through multi-region sourcing or partnerships that protect against single-point disruptions. The main uncertainty is the direction and granularity of future tariff and trade actions, which could alter the relative attractiveness of certain sourcing routes on short notice. Organizations that build scenario flexibility into their sourcing and pricing models will be better equipped to adapt.
Strategic Recommendations for Decision Makers
For Manufacturers and Brand Leaders
Invest in formulation roadmaps that simultaneously address performance metrics and compliance trajectories. Prioritize metal-free, spectrally selective, and recycled-content options where credible testing and certification can support claims. Align R&D with the standards and chemical restrictions most relevant to target markets, and use that alignment as a commercial narrative in specification processes. Strengthen application engineering and installation support capabilities, because performance claims are only as strong as the real-world results delivered through proper deployment. Consider targeted consolidation or capability acquisitions that expand manufacturing depth, broaden the product portfolio, or improve regional service coverage, while ensuring that integration preserves the innovation and responsiveness that differentiate the brand.
For Investors and Capital Allocators
Focus on the intersection of regulatory tailwinds and performance differentiation. Companies that can convert energy performance standards and sustainability requirements into specification advantages are more likely to sustain pricing power and win recurring retrofit demand. Evaluate exposure to tariff-sensitive supply chains and assess whether the business model includes mitigation options such as regional manufacturing, diversified sourcing, or value-added services that reduce reliance on unit-price competition. In the automotive and construction segments, look for evidence that product propositions are tied to measurable efficiency or comfort outcomes, because these are increasingly the criteria that unlock budget allocation in both new projects and retrofit cycles.
For Procurement and Specifying Organizations
Move beyond unit-price comparisons toward total cost of ownership evaluations that incorporate thermal performance, visible light transmission, installation complexity, warranty support, and compliance credentials. Where possible, require documentation aligned with recognized performance standards and verify the substance behind sustainability claims, particularly around recycled content and lower-impact adhesive chemistries. Build sourcing flexibility to navigate tariff volatility and input cost swings, and consider qualifying more than one origin or supplier for critical film categories to reduce concentration risk. For large retrofit programs, pilot products with clear performance claims and monitor real-world outcomes before scaling to full deployment.
From Strategic Direction to Operational Precision
The solar control window films market is entering a phase where momentum is increasingly tied to verifiable performance, compliance readiness, and supply chain discipline. The growth trajectory is favorable, but capturing value will depend on how effectively organizations translate regulatory shifts, material science advances, and demand-side expectations into differentiated offerings and resilient operating models. For leaders who need granular segmentation detail, region-specific tariff mapping, product-level performance comparisons, or customized scenario planning, the next step is to move from market-level direction to project-relevant data. PW Consulting's comprehensive research on the solar control window films market provides the deeper segmentation, competitor profiling, and forward-looking models required to turn strategic intent into executable decisions. Accessing that level of detail can shorten the path from insight to action, particularly when planning product portfolios, specification strategies, or sourcing transformations in a market where timing and precision matter.
For detailed analysis of this topic, please visit the official page: Solar Control Window Films Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


