



Automotive Steel Market: How AHSS Adoption and Regional Shifts Reshape Growth Beyond the 3.1% CAGR

Navigating the Automotive Steel Market: Strategic Shifts, Competitive Dynamics, and Emerging Value Pools
The automotive steel market has entered a phase of measured expansion, characterized by steady volume growth, evolving material specifications, and shifting purchasing behaviors among global OEMs. After moving through a period of post-pandemic normalization, supply chain recalibration, and aggressive lightweighting mandates, the sector now operates at a scale that reflects both automotive production recovery and long-term structural demand for higher-performance grades. Market size has progressed from approximately $102.8 million in 2020 to around $131.2 million in 2025, with projections pointing toward roughly $163.6 million by 2032. The implied compound annual growth rate of 3.1 percent across the 2026 to 2032 horizon signals a market that is expanding, but not accelerating explosively; growth will be earned through specification upgrades, regional manufacturing realignment, and disciplined capacity deployment rather than broad-based volume surges.
For executives and strategic planners, the headline trajectory matters less than the forces reshaping how value is created and captured within that trajectory. The sector is no longer defined solely by tonnage and price cycles. Instead, commercial advantage increasingly depends on engineering collaboration, grade differentiation, supply chain predictability, and the ability to align production with evolving emissions, safety, and lightweighting requirements. Understanding these underlying dynamics is essential for manufacturers evaluating capacity allocation, investors assessing long-cycle exposure, and procurement teams negotiating multi-year supply agreements.
Market Snapshot and the Core Challenges Ahead
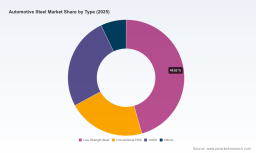
The current market structure reflects a mature but still evolving ecosystem. Demand is distributed across a broad set of applications, with body structure and powertrain components accounting for the largest shares of consumption. Regional demand patterns show a clear tilt toward Asia Pacific, supported by vehicle production scale and ongoing industrialization, while North America and Europe maintain significant shares driven by established OEM bases, stricter safety regulations, and active lightweighting programs. The composition of steel grades further illustrates the market's direction: while lower-strength materials still represent the largest segment by volume, higher-strength and advanced high-strength grades continue to gain relative importance as vehicle architectures prioritize weight reduction and crash performance.
This growth path is not without friction. Three challenges stand out as particularly consequential for the next planning cycle.
First, price volatility and input cost uncertainty remain embedded in the market. Hot-rolled coil pricing has shown periodic resets, with some producers implementing upward adjustments as energy, labor, and rolling-mill operating conditions evolve. In January 2026, for example, one major North American producer raised its hot-rolled coil consumer spot price to $960 per short ton, with further increases anticipated into the second quarter. While spot movements do not capture the full contract environment, they underscore how quickly cost structures can shift and how sensitive margins can be to timing, hedging, and contract design.
PW Consulting
Second, tariff exposure and trade policy uncertainty are reshaping procurement strategies. Automotive steel is heavily traded, and even modest policy shifts can alter landed costs, sourcing options, and the economics of regional production. In response, several suppliers have pursued multi-year fixed-price contracts with US automakers to help hedge tariff impacts and create greater cost predictability. The broader implication is that procurement is moving away from purely transactional purchasing toward longer-duration agreements that emphasize stability, quality assurance, and integrated technical support.
Special Steel Market
Third, the specification transition toward advanced and press-hardened steels is raising the bar for both suppliers and OEMs. Higher-strength grades require tighter process control, enhanced coating and galvanizing capabilities, and closer engineering collaboration at the design stage. This creates a competitive filter: producers with dedicated automotive lines, proven qualification processes, and application-specific expertise are better positioned to capture premium demand, while others face pressure to compete primarily on price in more commoditized segments.
The Forces Reshaping Demand, Supply, and Value Capture
Several interconnected drivers explain why the market is moving toward its projected path and why the nature of competition is changing.
Technological innovation remains a primary catalyst. Advanced high-strength steel and press-hardened grades continue to enable body-in-white designs that reduce mass without sacrificing structural integrity or crash performance. As vehicle architectures become more complex and multi-material designs become more common, steel suppliers are increasingly expected to contribute at the design and simulation stage rather than simply delivering standardized coils. Technical sessions at recent industry forums have highlighted how press-hardened steel and advanced high-strength grades are being integrated into structural and safety components, reinforcing the idea that material selection is now an engineering decision with long-term implications for platform efficiency, performance, and cost.
Regulatory and policy conditions are equally influential. Safety standards, emissions targets, and regional content expectations continue to shape material choices and sourcing decisions. At the same time, trade and tariff dynamics are encouraging OEMs and suppliers to seek contractual structures that reduce exposure to abrupt cost swings. This has increased the strategic value of predictable supply arrangements, localized production footprints, and suppliers that can demonstrate consistent quality across high-volume programs.
On the demand side, OEM behavior is shifting from short-term price optimization toward long-term program stability. Automotive manufacturers are balancing lightweighting goals with cost discipline, and that balance is driving more deliberate specification decisions. Where advanced steels can deliver meaningful weight savings and performance benefits, they are increasingly justified within total-vehicle economics rather than evaluated solely on per-ton cost. This creates opportunities for suppliers that can present credible technical and commercial cases for grade upgrades, especially when paired with reliable delivery and strong application support.
Supply chain and cost structure changes are adding another layer of complexity. Capacity additions are being targeted rather than indiscriminate, with certain producers allocating meaningful portions of new hot-rolled coil capacity specifically to automotive grades. That kind of dedicated allocation signals confidence in sustained automotive demand and reflects a strategic preference for serving higher-value segments rather than flooding the broader market. At the same time, raw material dynamics, energy costs, and regional production economics continue to differentiate competitive positions across North America, Asia, and Europe.
Competitive Landscape: Positions, Moves, and Structural Shifts
The market is moderately concentrated, and the leading participants are pursuing distinct strategic identities rather than competing on a single dimension.
Some of the largest global producers are anchoring their positions in advanced high-strength steel and automotive-grade flat-rolled products, emphasizing body-in-white and structural applications. Their differentiation comes from scale, grade breadth, and the ability to support OEMs across multiple platforms and regions. Others are building strong regional identities around electric arc furnace production, sustainability narratives, and localized supply reliability, particularly in North America. These players often compete by combining cost discipline with dedicated automotive capacity and long-term customer relationships.
A third group of specialists and regional leaders focuses on high-grade steel sheets, micro-alloyed high-strength products, galvanized offerings, and advanced automotive grades tailored for specific performance requirements. Their advantage frequently lies in technical specialization, faster responsiveness to OEM specification changes, and strong positions in niche but valuable application areas. Across these profiles, the common thread is a move toward closer customer integration and more application-specific value propositions.
Recent actions illustrate how this competition is playing out in practice. One US-based producer secured new multi-year supply contracts with major domestic automakers, reinforcing a strategy built on contract stability and tariff hedging. That same producer was recognized as a top supplier by a leading automaker for its automotive steel contributions, highlighting how performance consistency and program support can strengthen commercial positioning. Another North American producer expanded its hot-rolled coil capacity with a dedicated automotive allocation, signaling a commitment to serving vehicle manufacturing demand with purpose-built supply rather than relying solely on general-market output. In parallel, industry symposiums have provided a venue for technical exchange on advanced high-strength and press-hardened steels, with participation from multiple major suppliers and a focus on structural design and manufacturing integration.
Together, these developments point to a landscape that is neither fully consolidating nor fragmenting in a simple way. Instead, it is stratifying. At one level, scale players continue to compete on breadth, global reach, and cost efficiency. At another, differentiated specialists and regionally anchored producers are gaining leverage through specification leadership, contract stability, and engineering collaboration. New entry is difficult because automotive qualification cycles, quality consistency requirements, and long-term program commitments create meaningful barriers. The more likely evolution is a continued separation between suppliers that can credibly compete in advanced grades and integrated program support, and those that remain exposed to more volatile, price-sensitive segments.
Outlook: What the Next Three to Five Years Are Likely to Bring
Looking ahead, several trends are likely to define the market's direction and shape where value is created.
One is the continued migration toward higher-strength and more application-specific grades, especially in body structure and safety-critical components. As lightweighting and crash performance requirements persist, advanced high-strength and press-hardened steels should see sustained interest. The commercial implication is that suppliers with strong technical capabilities, reliable coating and galvanizing infrastructure, and proven OEM qualification track records are likely to capture a larger share of the more profitable parts of the market. For OEMs and tier suppliers, the opportunity lies in selecting materials and partners that reduce total system cost while meeting performance targets, rather than treating steel selection as a commodity procurement decision.
A second trend is the growing importance of contract design and supply predictability. Tariff exposure, pricing volatility, and program timing uncertainty are encouraging longer-duration agreements and more structured relationships between producers and automakers. This benefits suppliers that can offer stable pricing mechanisms, consistent quality, and flexible allocation across programs, while also rewarding OEM procurement teams that can balance cost control with risk reduction. Over time, this may push the market toward fewer but deeper contractual relationships in certain regions, particularly where policy uncertainty or input cost swings make short-cycle purchasing less attractive.
A third trend is regional capacity realignment tied to automotive demand and supply chain resilience. Dedicated automotive allocations, localized production footprints, and targeted hot-rolled coil expansions suggest that producers are increasingly optimizing for specific end-use demand rather than treating automotive as a secondary outlet. This can improve delivery reliability and reduce logistics exposure, but it also means that capacity is becoming more segmented. The risk is that localized supply advantages may be offset by regional cost disparities, policy shifts, or demand volatility if vehicle production patterns change faster than expected.
These trends carry both opportunity and uncertainty. On the opportunity side, the combination of specification upgrades, contract stability, and targeted capacity deployment creates a setting where disciplined suppliers and well-positioned buyers can lock in long-term advantage. On the risk side, policy changes, energy cost swings, and shifts in vehicle production mix could disrupt assumptions about regional demand and grade adoption. The electrification trajectory, in particular, remains a variable that can influence component design, material intensity, and the relative demand for different steel grades over time.
Strategic Implications for Decision Makers
For manufacturing and OEM leaders, the priority is to treat steel selection as a platform-level decision rather than a repetitive procurement task. That means engaging suppliers earlier in the design process, evaluating total program economics, and building qualification pathways for advanced grades where they deliver measurable weight, performance, or cost advantages. Where possible, linking material strategy to modular architecture and multi-program reuse can help capture the benefits of higher-performance steels without inflating per-program cost.
For procurement and supply chain executives, the emphasis should be on contract structures that balance price competitiveness with predictability. Multi-year agreements, transparent index mechanisms, and supplier commitments to dedicated automotive capacity can reduce exposure to spot volatility and policy-driven cost shocks. Equally important is ensuring that supplier selection accounts for quality consistency, application support, and the ability to scale with program ramps, since technical and delivery reliability often matter more over a program lifecycle than marginal per-ton differences at the outset.
For investors and strategic planners, the market rewards differentiation over broad exposure. Companies that are building dedicated automotive capacity, advancing advanced high-strength and press-hardened steel offerings, and securing long-term OEM relationships are likely to be better positioned than those dependent primarily on undifferentiated volume. At the same time, close attention should be paid to regional cost structures, tariff risk, and the pace at which specification upgrades translate into actual volume migration. In a market growing at a mid-single-digit pace, the dispersion between winners and laggards is likely to widen based on execution, customer integration, and grade mix rather than headline demand alone.
Automotive Steel Piston Market
The automotive steel market is not entering a period of dramatic upheaval, but it is entering a period where detail matters more than ever. Regional demand patterns, grade migration, contract design, and supplier specialization are all shaping outcomes in ways that are not always visible in aggregate size figures. For organizations making capacity, sourcing, investment, or program decisions, the ability to map these dynamics to specific applications, customer segments, and regional conditions is a critical advantage.
Those seeking a deeper, segment-level view of market sizing, regional demand patterns, grade adoption trajectories, and company-specific positioning can find a more granular breakdown in the full PW Consulting market analysis. The complete report provides detailed breakdowns and tailored strategic guidance for manufacturers, procurement teams, and investors navigating the next phase of automotive steel demand.
For detailed analysis of this topic, please visit the official page: Automotive Steel Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


