



Chloromethane Market: Why Asia Pacific's Growth Outpaces a 4.8% CAGR Trajectory

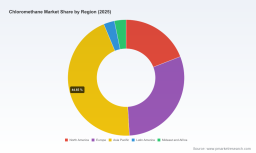
The Strategic Landscape of the Chloromethane Market: Trends, Challenges, and Opportunities
The chloromethane market stands at a pivotal juncture, shaped by evolving regulatory frameworks, shifting supply chain dynamics, and growing demand for specialized chemical intermediates. With an estimated global market size of USD 3.88 billion in 2025 and a projected compound annual growth rate (CAGR) of 4.8% through 2032, the sector reflects steady expansion tempered by structural transformations. Over the past five years, revenues have climbed from approximately USD 3.26 billion in 2020 to the current level, signaling consistent commercial activity across industrial chemical value chains. The forecast period through 2032 suggests an upward trajectory, with market size expected to approach USD 5.35 billion by the end of the decade. Yet beneath these aggregate figures lies a complex interplay of production constraints, compliance requirements, and regional trade realignments that demand careful strategic navigation.
Market Snapshot and Structural Challenges
The chloromethane market operates within a moderately consolidated landscape, where the leading three participants collectively account for roughly 57.3% of total revenue. This concentration reflects long-established manufacturing footprints, integrated production capabilities, and established customer relationships across silicone intermediates, specialty solvents, and chemical synthesis applications. Despite the scale of incumbent players, the market continues to evolve as regional trade flows adapt to tariff adjustments and as end-users increasingly prioritize supply resilience over purely cost-driven procurement.
Several structural challenges are reshaping how manufacturers and buyers approach this market. First, regulatory intervention is no longer a peripheral concern but a central determinant of product portfolio strategy. In the United States, final risk management rules under the Toxic Substances Control Act (TSCA) have prohibited all consumer uses of methylene chloride since May 2025, with commercial applications facing restrictions after April 2026. Permitted industrial uses now require adherence to a Workplace Chemical Protection Program, and exposure limits have been tightened to an eight-hour time-weighted average of 2 parts per million. These provisions fundamentally alter how producers must position certain chloromethane derivatives, shifting emphasis toward non-regulated applications and technically compliant supply channels.
Second, feedstock cost volatility and energy-intensive production processes continue to pressure margins. Chloromethane manufacturing relies heavily on the reaction of methanol and hydrogen chloride, meaning that fluctuations in methanol pricing directly translate into product cost movements. In the fourth quarter of 2025, rising methanol feedstock costs contributed to modest year-over-year price increases of roughly 3% in the United States market. While not an extreme spike, this movement underscores how raw material linkages and utility cost structures can quickly affect commercial competitiveness, particularly for producers operating in regions with higher energy or logistics burdens.
Third, trade policy shifts are reconfiguring traditional sourcing patterns. Tariff measures introduced in 2025 have altered global methyl chloride trade flows, prompting buyers to diversify procurement strategies and evaluate alternative supply regions. This recalibration affects both imported and domestically produced volumes, creating a more fragmented negotiating environment for procurement teams accustomed to stable cross-border trade corridors.
Core Drivers Shaping Market Direction
The trajectory of the chloromethane market is being shaped by a combination of technological, regulatory, demand-side, and supply-side forces. Understanding how these drivers intersect helps clarify where value creation is emerging and where strategic positioning will matter most.
Technological Innovation and Process Optimization
Advancements in production efficiency, purity standards, and sustainability certification are becoming differentiators in an otherwise mature chemical category. Manufacturers are increasingly emphasizing certified grades and traceable production pathways to meet customer requirements for specialty and performance chemicals. For example, some European producers now offer ISCC+ certified sustainable chlorine chemistry grades, signaling a broader industry move toward verifiable environmental credentials. These certifications do not merely serve compliance purposes; they also enable access to procurement programs where sustainability metrics influence supplier selection. At the same time, producers are refining technical-grade offerings with high purity specifications, such as 99.95% purity grades with Kosher certification, to serve chemical synthesis and specialty applications that demand consistent quality and documented production standards.
Regulatory and Policy Environment
Regulatory developments are acting as both a constraint and a catalyst for market reorientation. The U.S. TSCA final risk management rule has already eliminated consumer-facing applications for methylene chloride and is phasing out broader commercial uses. This regulatory trajectory pushes the market toward applications with clearer industrial justification, such as silicone manufacturing intermediates and certain solvent and synthesis uses where exposure controls can be reliably implemented. Beyond the United States, trade policy adjustments have introduced additional complexity. Tariff measures in 2025 have shifted cost structures and encouraged buyers to reassess single-source dependencies. Rather than simply reducing demand, these policy shifts are prompting supply chain redesigns, where regional sourcing, contractual flexibility, and multi-supplier strategies are gaining prominence.
Demand-Side Shifts and End-Use Evolution
Demand patterns are being redefined by downstream industrial priorities. Silicone manufacturing remains a dominant consumption pathway, driven by the broader use of silicones in construction, consumer goods, electronics, and industrial coatings. Pharmaceutical and specialty chemical applications continue to contribute meaningful volume, particularly where chloromethane derivatives serve as intermediates requiring stringent purity and documentation. At the same time, agrochemical and foaming agent applications represent smaller but strategically relevant segments that benefit from stable industrial demand. A notable demand-side trend is the growing preference for supply reliability and certification assurance over lowest-cost sourcing. Procurement teams in regulated industries are increasingly evaluating suppliers based on compliance readiness, product consistency, and the ability to support downstream quality requirements, which elevates the strategic importance of transparent and well-documented supply chains.
Supply Chain and Cost Structure Dynamics
The supply chain for chloromethane is influenced by feedstock availability, plant utilization decisions, and regional production capacity. Methanol feedstock costs, which rose in late 2025, illustrate how input price movements quickly propagate into product pricing. In parallel, producers are making deliberate capacity allocation choices to optimize asset utilization. Some manufacturers have announced strategic idling of certain facilities to concentrate operations at core sites, reflecting a broader trend toward operational focus and cost discipline. These decisions are not purely reactive; they often represent calculated moves to align production with demand centers, reduce overhead, and strengthen margins in a market where price increases can be limited by regulatory constraints and competitive pressure. Transportation and logistics continue to function without extraordinary export controls specific to this category, though general tariff shifts remain a relevant variable for cross-border trade planning.
Competitive Landscape and Leading Strategies
The chloromethane market features a mix of large integrated chemical producers and regional specialists, each pursuing distinct strategic positioning. Major U.S.-based producers maintain significant manufacturing presence through integrated chlorine and methanol-based processes, supplying technical-grade material for silicone intermediates and industrial solvents. Their scale and integrated feedstock access provide a foundation for consistent supply and competitive cost structures. Other established producers operate dedicated facilities with specialized grade offerings, including Kosher-certified technical grades and sustainable-certified product lines, which allow them to serve niche and performance-driven demand segments. In India, one prominent producer has built a full-range chloromethane portfolio supported by a dedicated plant, emphasizing domestic supply and import substitution. This regional strategy reflects broader market dynamics where local production capacity can reduce reliance on imports and respond more directly to domestic demand fluctuations. Across Europe, some producers have positioned themselves around product specialization and sustainability certification, offering complete chloromethane ranges with documented environmental credentials that appeal to customers navigating compliance and procurement requirements.
Recent corporate and operational developments underscore the evolving competitive dynamics. In mid-2025, a notable acquisition expanded the production capacity and market reach of a regional chloromethane producer, illustrating how consolidation can be used to strengthen scale and customer coverage. Around the same period, another manufacturer announced the strategic idling of a chloromethane facility to optimize operations and concentrate resources on a core production site. These moves highlight two simultaneous trends: selective expansion where scale and market access justify investment, and deliberate consolidation or rationalization where asset utilization and cost alignment take precedence. Together, they suggest a market in which competitive advantage is increasingly derived from disciplined capacity management, differentiated product grades, and the ability to adapt to regulatory and trade conditions rather than from undifferentiated volume growth.
The competitive landscape is also showing signs of differentiation by application readiness and certification capability. Producers that can supply documented purity, compliance support, and sustainable production pathways are better positioned to retain or expand relationships with downstream users facing stricter internal procurement standards. At the same time, price sensitivity remains relevant, especially where end-use applications are exposed to cost pressures or where alternative feedstocks and intermediates can serve similar functions. This dynamic sets up a competitive environment where both technical differentiation and commercial agility matter.
Forward Outlook: Key Trends and Commercial Implications
Looking ahead across the next three to five years, several trends are likely to define the chloromethane market’s evolution and shape where commercial opportunities emerge.
- Regulatory-driven product portfolio realignment will intensify. As consumer uses disappear and commercial applications face tighter exposure controls, producers will increasingly concentrate on industrial and specialty applications with manageable compliance pathways. This shift creates opportunities for suppliers that can demonstrate robust workplace protection programs, consistent purity, and documentation aligned with downstream requirements. It also raises the stakes for product segments that cannot adapt to stricter regulatory conditions.
- Regional supply chain diversification will become a default procurement strategy. Tariff-induced trade adjustments and the broader emphasis on supply resilience are encouraging buyers to avoid overreliance on single regions or single suppliers. This trend favors producers with flexible logistics, multi-site capabilities, or strong regional presence that can support localized supply commitments. For buyers, it means that supply agreements may need to incorporate more flexible origin options, contingency planning, and clearer compliance documentation.
- Sustainability credentials and certified grades will gain commercial weight. The emergence of ISCC+ certified chlorine chemistry grades and other traceability initiatives reflects an industry-wide push toward verifiable sustainability attributes. While not every application demands these certifications today, procurement programs in regulated and sustainability-conscious sectors are increasingly treating them as meaningful selection criteria. Producers that can offer certified grades without sacrificing cost competitiveness or supply reliability will be better placed to capture premium demand and long-term contracts.
These trends carry both opportunity and uncertainty. On the opportunity side, demand for silicone intermediates and specialty chemical synthesis is expected to remain resilient, and certified or compliance-ready supply can command stronger customer loyalty. On the risk side, regulatory timelines can accelerate faster than anticipated, feedstock costs can shift unpredictably, and trade policy can alter relative competitiveness across regions. Producers and buyers alike will need to monitor how exposure limits, commercial use restrictions, and tariff structures evolve, as these variables directly affect volume allocation, pricing flexibility, and sourcing strategies.
Strategic Guidance for Decision-Makers
Manufacturers, investors, and procurement leaders face different but interconnected priorities in this environment. Aligning strategy with the market’s regulatory, cost, and supply realities can improve resilience and position organizations to capture value as the market matures.
PW Consulting
For Manufacturers and Producers
Focus on application-specific differentiation and operational discipline. Rather than competing solely on volume, emphasize purity consistency, documentation quality, and compliance readiness for industrial and specialty applications that remain viable under tighter regulatory conditions. Where feasible, develop certified product lines and traceability capabilities that meet customer sustainability expectations. At the same time, maintain disciplined capacity allocation by aligning plant utilization with demand centers and feedstock cost realities, and avoid overcommitting to segments likely to face the steepest regulatory constraints.
For Investors and Strategic Capital Allocators
Evaluate exposure to regulated applications versus industrial and specialty segments that are more likely to retain demand. Attention should be given to producers with integrated feedstock access, multi-site flexibility, and the ability to offer differentiated grades, as these attributes can support margin stability in a market where price increases may be constrained. Acquisitions and facility optimization moves suggest that scale and asset focus remain relevant value drivers, but due diligence should account for regulatory risk, feedstock sensitivity, and regional trade exposure rather than relying on top-line growth assumptions alone.
For Procurement and Supply Chain Leaders
Treat supply diversification and compliance documentation as strategic imperatives rather than administrative tasks. Given tariff-driven trade adjustments and the phase-out of certain commercial uses, procurement strategies should incorporate multiple sourcing options, clearer origin flexibility, and supplier qualification criteria that include regulatory readiness and product certification. Contract structures may benefit from provisions that address feedstock-linked cost movements and allow for adaptive sourcing when trade or regulatory conditions change. Building visibility into supplier production practices and certification status can reduce downstream risk and strengthen negotiation leverage.
Worldwide Monochlorobenzene Market
Closing Perspective
The chloromethane market is not simply expanding; it is reorganizing around regulatory clarity, supply resilience, and product differentiation. Aggregate growth projections reflect continued industrial demand, but the practical value for decision-makers lies in understanding which applications, regions, and supplier capabilities will remain most relevant as rules tighten and trade patterns shift. Manufacturers that align production with compliant and certified demand, investors that weigh regulatory and feedstock exposure carefully, and procurement teams that build flexible and well-documented supply chains will be best positioned to navigate the coming years. For organizations seeking a more detailed breakdown of segment dynamics, regional nuances, and custom strategic scenarios, a comprehensive market report can provide the granularity needed to translate these high-level trends into concrete commercial decisions.
Methyl Mercaptan Market
For detailed analysis of this topic, please visit the official page: Chloromethane Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


