



Anatomical Models Market: Why the 5.88% Cagr and Medical Education Shift Reshape Outcomes

The Anatomical Models Market: Strategic Trends & Commercial Opportunities Through 2032
Market Overview: Scale, Growth Trajectory, and Structural Headwinds
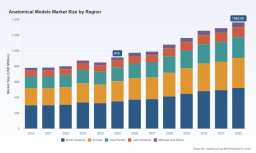
The global market for anatomical models reached approximately $915 million in 2025, following a compound annual growth rate of 5.88 percent across the 2026 to 2032 forecast period. Historical figures from 2020 through 2024 illustrate a market that has weathered volatility but maintained an upward trajectory, with 2023 marking a notable peak before a brief recalibration in 2024. By 2032, projected revenue crosses the $1.36 billion threshold, signaling a maturing industry transitioning from steady expansion to more structured, technology-driven growth phases.
This trajectory is not merely a function of population growth or healthcare spending. The anatomical models sector sits at the intersection of medical education, clinical training, surgical planning, and increasingly, patient-specific device development. That positioning creates a dual-demand structure: one anchored in institutional procurement cycles and another emerging from rapid adoption curves in digital and additive manufacturing workflows. The result is a market that rewards precision in forecasting, particularly around how educational budget cycles interact with clinical innovation pipelines.
Several structural challenges define the current inflection point. First, procurement fragmentation across academic institutions, hospital systems, and independent training centers creates uneven demand signals. Budget committees in medical schools often operate on multi-year cycles, while clinical departments may prioritize immediate training needs, leading to lurching purchasing patterns that complicate capacity planning for manufacturers. Second, regulatory clarity around patient-specific printed models remains unevenly distributed across jurisdictions. While certain pathways have eased, reimbursement structures still vary significantly, creating adoption friction in health systems that depend on predictable cost recovery. Third, the cost architecture of high-fidelity synthetic models versus additively manufactured alternatives is shifting rapidly. Traditional molding and casting approaches offer durability and tactile realism, but they carry higher upfront tooling costs and longer lead times. In contrast, digital fabrication lowers unit economics at scale, but requires investment in software pipelines, material validation, and quality control processes that many mid-tier producers are still mastering.
Core Growth Drivers: Technology, Policy, Demand, and Cost Dynamics
The expansion of the anatomical models market is propelled by four interconnected forces that are reshaping both product design and commercial distribution.
Technology Innovation and the Additive Manufacturing Inflection
Additive manufacturing has moved from prototyping niche to mainstream production enabler. Recent corporate activity signals a clear pivot: multi-center clinical studies are now evaluating 3D-printed anatomical models for orthopedic oncology, measuring surgical outcomes and procedural efficiency rather than just visual fidelity. At the same time, regulatory milestones have removed practical barriers for personalized model production, with clearance obtained for solutions that allow physicians to print patient-specific anatomy for planning and communication purposes. These developments are not isolated product launches; they represent a shift in how models are valued, moving from static teaching props toward decision-support tools in clinical workflows.
Eye Anatomical Model Market
Beyond printing hardware, material science is compressing the gap between synthetic durability and anatomical realism. Bone-like composites, layered tissue analogues, and vascular injection trainers are improving haptic feedback and procedural relevance. That matters because educational outcomes increasingly depend on how closely training tools replicate clinical conditions, especially for minimally invasive techniques and emergency response training. The commercial implication is straightforward: vendors that integrate material validation, anatomical accuracy, and procedural context into a single product line are capturing more of the training value chain than those competing on visual detail alone.
Policy and Regulatory Environment
Regulatory evolution is reshaping the market's risk profile. Updates to clearance requirements have reduced obstacles for patient-specific printed models and surgical guides, creating a more predictable path for companies targeting clinical applications. At the same time, diagnostic- or training-grade models that intersect with regulated use cases must still satisfy quality management standards and device classification frameworks. The net effect is a bifurcated compliance landscape: education-focused models follow one set of expectations, while patient-specific or procedural models face additional scrutiny and documentation requirements.
Reimbursement dynamics add another layer. Patient-specific printed models and related surgical guides are reimbursed through specific coding categories, though reimbursement levels vary by payer. This partial coverage model means adoption is strongest where clinical teams can demonstrate clear time savings, reduced error rates, or improved patient communication. Manufacturers and distributors that actively support evidence generation, coding guidance, and implementation workflows are better positioned to convert clinical interest into sustained procurement.
Demand-Side Shifts in Education and Clinical Training
The demand base is widening beyond traditional anatomy classrooms. Medical education programs continue to be the largest application area, but hospitals and clinics are increasingly deploying anatomical models for staff onboarding, procedural rehearsal, and interdisciplinary training. Research institutions also contribute a meaningful share, using realistic anatomy replicas for device testing, biomechanical studies, and protocol development. This diversification reduces dependence on any single procurement cycle, but it also raises expectations for application-specific design. A model that works for undergraduate anatomy instruction may not satisfy surgical training requirements, and a patient education model needs different usability characteristics than a lab research replica.
A notable demand-side trend is the push toward inclusive and scenario-based training. New product modules targeting women's health emergency response and advanced vascular access illustrate how training content is becoming more specialized and more representative of real-world patient populations. This mirrors a broader shift in healthcare training toward competency-based assessment, where the model is not just a visual reference but a platform for repeatable skill evaluation. Companies that provide modular content, scenario libraries, or integration pathways with simulation systems are gaining relevance in procurement decisions that prioritize outcomes over units purchased.
Supply Chain and Cost Structure Evolution
Cost economics are being redefined by digital production and material choice. Lower-cost printed models commonly use widely available polymers, with unit costs varying by method and size across a broad range. That flexibility allows institutions to produce in-house for certain use cases, but it also creates pressure on commercial suppliers to justify value beyond simple geometry. The winning position is increasingly held by providers that offer validated material properties, regulatory-ready documentation, and application-specific finishing rather than raw printing alone.
Supply chain resilience is another factor. Educational procurement often favors durable, reusable synthetic models that withstand repeated handling across cohorts. Clinical and research applications may prioritize rapid turnaround and patient-specific customization. Balancing these needs requires a supply strategy that can shift between batch production for standard curricula and on-demand manufacturing for individualized use cases. Firms that can manage both ends of this spectrum, while maintaining consistent quality and lead-time transparency, reduce the risk of being undercut by purely low-cost competitors or overwhelmed by specialty orders.
Competitive Landscape: Positioning, Differentiation, and Market Evolution
The market is moderately concentrated, with the top three players accounting for roughly 48.5 percent of revenue and the top five reaching approximately 59.2 percent. This concentration suggests a core of established manufacturers with broad catalogs, durable brand recognition, and entrenched relationships in academic and clinical procurement. Yet the presence of several specialized and digitally oriented companies indicates that differentiation is now more important than scale alone.
The competitive field spans traditional synthetic model producers and newer entrants levering digital fabrication. Leading manufacturers with broad portfolios emphasize durable plastic anatomical models, including skeletons, organs, joints, and specialized structures, often supplemented by 3D-printed options. Their advantage lies in catalog breadth, established distribution channels, and familiarity within medical education procurement teams. Other strong positions are built around life-like replicas using bone-like materials, realistic synthetic models tailored for clinical and classroom use, and durable synthetic models paired with educational supplies. These players compete on material fidelity, proportion accuracy, and durability.
Worldwide Nursing Mannequin Market
A second group of competitors focuses on procedural and simulation-integrated solutions. Some companies supply synthetic bone models and tissue replicas specifically for surgical training and orthopedic education. Others embed anatomical models into broader simulation systems or provide trainers designed for professional medical simulation programs. This segment competes less on static visual realism and more on integration, repeatability, and scenario coverage. The strategic value here is clear: when training programs need to assess competency or rehearse specific procedures, models that connect to simulation workflows and evaluation metrics become procurement priorities.
Digital and additive players are expanding the definition of an anatomical model. One prominent digital platform offers life-sized virtual anatomical models and digital dissection environments for education, creating an alternative to physical replicas for programs that prioritize visualization flexibility and content updates. On the hardware side, companies providing 3D-printed models for training, surgical planning, and device testing are building ecosystems around file preparation, material selection, and clinical collaboration. Recent activity underscores this direction: new vascular access trainers and inclusive CPR training modules have broadened educational use cases, while clinical studies and regulatory clearances are reinforcing the role of patient-specific printed models in surgical planning.
Several market evolution patterns are emerging. First, consolidation pressure is building around catalog breadth and distribution reach, as institutions increasingly prefer fewer vendors capable of supplying models across anatomy, simulation, and procedural training. Second, segmentation is sharpening, with companies choosing between education-focused durability and clinical-grade precision, rather than trying to serve both with a single product line. Third, new entrants are not necessarily competing on catalog size; many are entering with narrow, high-value use cases such as orthopedic oncology modeling, vascular access training, or patient communication replicas, then expanding through partnerships with hospitals, research centers, and training networks. The market is therefore moving toward a structure where incumbents defend share through breadth and relationships, while challengers gain relevance through application specificity and digital integration.
PW Consulting
Future Trends and Commercial Opportunities (2026-2031)
The next three to five years will likely be defined by three trends that turn current momentum into structured commercial opportunity.
The first trend is the convergence of physical and digital anatomy training. Virtual dissection platforms, digital model libraries, and physical trainers are increasingly used together rather than as substitutes. Programs want the flexibility to switch between remote visualization, hands-on practice, and scenario assessment without managing incompatible systems. For suppliers, this creates opportunity in interoperable content, cross-platform licensing, and bundled training packages that combine durable synthetic models with digital modules and evaluation tools. The risk is that programs expecting seamless integration may penalize vendors whose products remain isolated in a single format.
The second trend is the expansion of patient-specific modeling from exceptional cases to routine planning workflows. Regulatory and reimbursement developments are making it more feasible for health systems to adopt printed models for pre-procedural planning and patient communication. The commercial opportunity lies in supporting the full workflow: image segmentation, model design, material selection, validation, and post-use documentation. Companies that can reduce the friction from scan to finished model, while providing evidence of clinical value, will be well placed to capture recurring demand rather than one-off projects. The uncertainty here is reimbursement consistency and institutional willingness to standardize on specific workflows across departments.
The third trend is the shift toward competency-based, scenario-driven training content. Anatomical models are increasingly evaluated based on how well they support repeatable skill practice, assessment, and inclusive training scenarios. This benefits vendors that invest in content libraries, modular accessories, and integration with simulation or assessment systems. It also raises the stakes for manufacturers that compete primarily on price or visual detail without addressing how the model fits into a training curriculum. The key uncertainty is how quickly educational accreditation and institutional standards will formalize expectations around scenario diversity, inclusive representation, and measurable competency outcomes.
Strategic Implications for Decision Makers
For manufacturers and product leaders, the priority is to align product roadmaps with the shift from static teaching aids to application-linked training tools. That means investing in material validation, procedural context, and integration pathways rather than treating anatomical accuracy as a standalone selling point. A practical step is to map product lines against real use cases—undergraduate anatomy, clinical onboarding, surgical rehearsal, device testing, and patient communication—and ensure each line has clear differentiation in material, durability, content support, or workflow integration. Companies that can demonstrate documented accuracy, quality management alignment, and scenario versatility will face fewer head-to-head price challenges and stronger procurement arguments.
For investors and strategic planners, the most instructive signal is the widening gap between broad catalog incumbents and application-focused challengers. Market concentration suggests room for continued consolidation, but value creation is increasingly coming from specialized workflows, digital-physical hybrids, and clinical evidence generation. Due diligence should focus on a company's ability to serve recurring institutional demand, support reimbursement or evidence-building where relevant, and manage the cost trade-offs between durable synthetic production and additive customization. Businesses that depend on a single procurement channel or a single product format face more exposure to budget cycles and substitution risk than those with diversified application coverage.
For procurement and training leaders in healthcare and education, the evaluation framework should expand beyond unit price and visual realism. The relevant questions include how a model supports competency assessment, whether it can be integrated with existing simulation or digital platforms, how maintenance and replacement cycles affect total cost, and whether the supplier provides documentation or workflow support for regulated or patient-specific use cases. Procurement strategies that align model purchases with curriculum objectives, training outcomes, and multi-year planning horizons typically achieve better value than transactional buying patterns that optimize only for initial cost.
The anatomical models market is entering a phase where differentiation is defined less by what a model looks like and more by what it enables: better training outcomes, faster clinical preparation, clearer patient communication, and more repeatable assessment. Companies and institutions that treat anatomical models as part of a broader training and planning ecosystem will be better positioned to capture the value embedded in the forecast growth path. For decision makers seeking a more detailed breakdown of segment dynamics, regional demand patterns, competitive positioning, and scenario-based forecasts, the full research report provides the supporting data and customized recommendations needed to convert these trends into actionable strategy.
For detailed analysis of this topic, please visit the official page: Anatomical Models Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


