



Acrylic Rubber Market: Why 6.98% CAGR and Asia Pacific’s Surge Redefine Growth Through 2032

The Acrylic Rubber Market: Navigating Growth, Regulation, and Strategic Positioning Through 2032
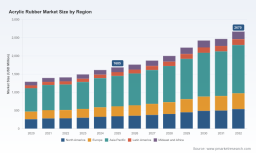
The acrylic rubber (ACM) market has transitioned from a steady niche segment into a structurally important component of industrial elastomers, driven by shifting application demands and evolving material performance requirements. Over the 2020-2025 period, the market expanded from approximately $1.29 billion to $1.69 billion, reflecting a compound trajectory that underscores both resilience and selective growth. Forward projections through 2032 point toward sustained expansion, with the market expected to reach roughly $2.67 billion, supported by a mid-to-high single-digit CAGR. This growth is not evenly distributed across regions or product categories; rather, it reflects concentrated demand in specific applications and regional manufacturing footprints that are actively reshaping supply dynamics.
Understanding where the market is heading requires looking beyond aggregate revenue figures. The underlying growth is tied to performance-driven substitution, regulatory pressure on legacy materials, and regional capacity adjustments that are altering pricing power and availability. For executives and investors tracking this space, the central question is not whether the market will grow, but which players will capture margin, where demand will shift, and how supply-side constraints will influence strategic decisions over the next several years.
Market Snapshot and Structural Context
The broader market trajectory between 2020 and 2025 reflects a pattern of moderate acceleration punctuated by periodic disruptions in raw material availability and regional manufacturing capacity. By 2025, total market size reached roughly $1.69 billion, with forward estimates indicating a steady climb through the late 2020s and into the early 2030s. The forecast window through 2032 suggests continued expansion, though the pace will likely vary by segment and geography as end-use industries recalibrate procurement strategies and material specifications.
Several structural features define the current landscape. First, the market is characterized by a concentrated supplier base, with the top three players accounting for a significant share of global supply and the top five firms representing a substantial majority. This concentration shapes pricing dynamics, innovation velocity, and the ability to respond to regional demand fluctuations. Second, the landscape is not monolithic in terms of product performance or end-use relevance; standard, high-performance, and specialty grades serve distinct technical and commercial purposes, and demand has been leaning toward higher-performance variants where operating conditions require improved heat, oil, and environmental resistance. Third, regional activity is uneven, with Asia Pacific representing the largest share of market value, while North America and Europe maintain strong positions tied to automotive, industrial, and specialty applications.
For decision-makers, the takeaway is that scale alone does not guarantee competitive advantage. The market’s growth is being shaped by performance requirements, regional capacity strategies, and the ability to secure reliable raw material streams. Companies that understand these dynamics are better positioned to plan capacity investments, pricing strategies, and long-term supply partnerships.
Core Challenges and Inflection Points
Despite the favorable trajectory, the acrylic rubber market faces several challenges that are likely to influence competitiveness and margin structure over the forecast period.
One of the most significant pressures comes from raw material cost volatility. Key feedstocks for acrylic rubber production are subject to fluctuations driven by upstream chemical cost pressures, regional demand imbalances, and intermittent supply tightness. In recent quarters, prices for critical intermediates have shown firm trends in major producing regions, with notable spreads between markets such as China and India. These variations affect production economics, especially for manufacturers operating across multiple jurisdictions or relying on imported inputs. When feedstock costs rise and supply is constrained, margin pressure intensifies unless pricing power, product mix, or hedging strategies can offset the impact.
PW Consulting
A second challenge is the ongoing shift in end-use requirements. Automotive and industrial customers increasingly demand materials that can withstand higher temperatures, aggressive fluids, and extended service life while meeting stricter environmental and regulatory expectations. This shift is not simply a matter of volume growth; it requires re-engineering product portfolios, validating new grades, and sometimes reworking downstream processing conditions. Firms that cannot move quickly toward higher-performance offerings may find themselves confined to lower-margin standard grades with intensifying competition.
A third inflection point relates to regulatory and energy transmission dynamics that influence industrial operating costs. Changes in energy tariff structures and transmission pricing can affect the cost base for chemical manufacturing and downstream processing, particularly for energy-intensive operations or facilities connected to high-voltage networks. Even when such changes are not directly targeted at rubber production, they alter the broader cost environment and can influence regional competitiveness, investment decisions, and procurement timing.
Together, these challenges create a market environment where strategic agility matters more than ever. Growth is available, but capturing it requires managing input cost risk, aligning product development with application trends, and anticipating how regulatory and energy-related shifts will affect regional cost structures.
Key Drivers Shaping the Market
The market’s direction is being shaped by a combination of technical, regulatory, demand-side, and supply chain forces. These drivers interact with one another, meaning that changes in one area often amplify or moderate effects in another.
Technology Innovation and Material Performance Breakthroughs
Material innovation remains one of the most powerful growth levers in the acrylic rubber market. Advances in polymer formulation, molecular design, and processing compatibility have expanded the range of applications where ACM can outperform alternative elastomers. High-performance grades with improved heat resistance, oil resistance, and low-temperature flexibility are increasingly specified in environments where traditional materials degrade more quickly or require more frequent replacement.
These technical gains are not abstract improvements; they translate into tangible value for end users. Longer service life reduces maintenance frequency, improved resistance supports higher operating temperatures, and better compatibility with formulated compounds can simplify compounding and lower total system cost. As a result, innovation is shifting the conversation from price per kilogram to total cost of ownership and performance reliability. Companies that can consistently deliver grades with demonstrable performance advantages are better positioned to defend pricing and expand share in demanding applications.
Regulatory and Policy Environment
Regulatory and policy developments are influencing both material selection and manufacturing economics. Environmental requirements, emissions considerations, and evolving industry standards are encouraging users to evaluate alternatives that offer durability and reduced replacement cycles. At the same time, energy and transmission policy changes can indirectly affect production costs and regional competitiveness.
Recent regulatory signals in energy transmission illustrate how policy can shape industrial cost structures. Tariff proposals that adjust pricing for different voltage-connected customers can alter the operating expense base for manufacturing facilities, particularly where energy is a meaningful share of input costs. While these changes vary by region and network operator, they highlight a broader point: regulatory environments are not static, and cost assumptions built around stable energy or transmission pricing may need regular reassessment. For producers and downstream users alike, monitoring policy trajectories is becoming part of effective supply chain and investment planning.
Demand-Side Shifts in Automotive and Industrial Applications
Demand is increasingly shaped by application performance needs rather than simple volume expansion. Automotive applications continue to represent a significant share of market value, driven by the need for seals, gaskets, hoses, and shaft seals that can endure heat, oil exposure, and long service intervals. As vehicle platforms evolve and operating conditions become more demanding, material specifications are tightening, which favors higher-performance grades and creates opportunities for suppliers with strong technical support capabilities.
Industrial machinery and related sectors also contribute meaningful demand, particularly where equipment must operate reliably under continuous stress or in environments with exposure to oils and elevated temperatures. Construction and energy-related applications add further diversity to the demand base, though their relative importance varies by region and project cycles. Across these segments, the common thread is a preference for materials that reduce failure risk, support longer maintenance intervals, and integrate well into engineered systems.
This demand-side shift has strategic implications. It rewards suppliers that can combine product variety with application-specific technical expertise, and it increases the importance of qualification processes, testing support, and consistent quality. In practice, the winning posture is less about offering the broadest catalog and more about delivering the right performance profile with reliable supply and documented performance.
Supply Chain and Cost Structure Evolution
Supply chain dynamics are increasingly central to competitive positioning. Feedstock availability, regional production capacity, and logistics constraints all influence cost and responsiveness. When key intermediates face firm pricing and constrained supply, manufacturers must decide how to absorb costs, pass them through, or mitigate exposure through sourcing strategy and product mix adjustments.
Regional differences in raw material pricing further complicate the picture. Spreads between major producing markets can create arbitrage opportunities but also expose companies to currency, logistics, and regulatory variability. In addition, capacity location decisions matter more when customers prioritize supply security and continuity. A supplier with diversified production footprint or strong regional sourcing may be able to offer more stable delivery terms, which can be a meaningful differentiator in tight markets.
Cost structure evolution also affects investment priorities. Firms may need to reconsider where to allocate capacity, how to structure inventory buffers, and whether to pursue vertical integration or long-term supplier agreements to stabilize input costs. In a market where margins can be pressured by feedstock movements, supply chain design becomes a strategic variable rather than a purely operational one.
Competitive Landscape and Leading Strategies
The acrylic rubber market is defined by a relatively concentrated group of leading players with distinct technological identities, geographic footprints, and product strategies. Rather than competing solely on price, the leading firms are differentiating through grade specialization, performance consistency, and application-focused support.
Zeon Corporation: Performance Grades and Multi-Region Capacity
Zeon Corporation has built a strong position around its ACM portfolio, with product grades designed to address specific performance requirements such as heat resistance and low-temperature behavior. Its Nipol AR71 and AR72LS grades illustrate a strategy focused on meeting targeted operating conditions rather than offering a one-size-fits-all material. Production capacity spanning facilities in Japan, Thailand, and the United States supports a multi-region supply approach, which can improve delivery flexibility and reduce exposure to single-market disruptions.
For customers, this positioning offers a combination of technical specificity and geographic diversification. For Zeon, the strategic value lies in maintaining performance leadership while expanding the ability to serve regional demand with localized production. In a market where qualification and consistency matter, such an approach can strengthen customer relationships and support premium positioning in higher-performance segments.
Mitsui Plastics: Broad Grade Range and Purification Emphasis
Mitsui Plastics takes a different but complementary approach, emphasizing a wide range of ACM grades derived from highly purified acrylic esters. Its RACRESTER line spans standard, low-Mooney, cold-resistant, high-temperature, epoxy, carboxyl, and special low-temperature variants, indicating a focus on serving diverse formulation needs and application conditions. Producing in Japanese facilities underscores a quality and process-control orientation that can be appealing to users seeking consistency and technical reliability.
Polyacrylate Rubber Acm Market
The breadth of grades allows Mitsui Plastics to address multiple performance profiles within a single product family, which can simplify sourcing for compounders and manufacturers handling varied specifications. At the same time, the emphasis on purification and grade variety suggests a strategy centered on material consistency and formulation flexibility. In practice, this can translate into stronger positioning in applications where processing behavior and batch-to-batch reliability are critical.
Unimatec Chemicals Europe GmbH: Application-Focused Automotive Solutions
Unimatec Chemicals Europe GmbH has positioned itself around acrylic elastomers designed for demanding automotive and industrial sealing applications. Its NOXTITE ACM grades are oriented toward high heat and oil resistance, targeting use cases such as seals, gaskets, hoses, and shaft seals. This application-focused approach reflects a strategy built on solving specific performance problems for end users rather than competing primarily on generic material attributes.
By concentrating on performance characteristics that matter in sealing and fluid-exposed environments, Unimatec aligns its offering with the practical needs of automotive and industrial customers. Such positioning can be especially effective when combined with technical support and qualification assistance, since customers in these segments often evaluate materials based on real-world reliability as much as base material properties.
Market Structure Evolution: Consolidation, Differentiation, and Entry Dynamics
The competitive landscape is evolving along several lines. Incumbent players are strengthening differentiation through grade specialization and regional capacity deployment, while customers increasingly reward reliability, technical support, and performance consistency. This environment favors firms that can combine product depth with dependable supply and clear application value propositions.
At the same time, market concentration creates both stability and barriers. A consolidated supplier base can support consistent quality and long-term investment in product development, but it can also make it more difficult for new entrants to gain traction unless they bring a distinct technical advantage, cost structure, or regional access. As a result, future competition is likely to be shaped less by outright price wars and more by performance differentiation, supply reliability, and the ability to meet evolving application requirements.
There is also room for strategic divergence. Some players may pursue broader grade portfolios to serve diverse customer bases, while others may concentrate on high-performance niches where margin and technical leadership are more defensible. Regional dynamics will further influence these choices, as producers align capacity and sourcing with local demand patterns and feedstock availability.
Future Trends and Commercial Opportunities
Looking ahead to the next three to five years, several trends are likely to define the market’s evolution and create actionable opportunities for well-positioned firms.
Shift Toward Higher-Performance and Application-Specific Grades
Demand is expected to continue tilting toward grades that deliver stronger heat resistance, improved oil compatibility, and better low-temperature behavior. This trend is being driven by operational demands in automotive and industrial settings, where failure avoidance and service life are prioritized. The commercial opportunity lies in expanding higher-value product mixes, building technical support capabilities, and aligning product development with the most demanding application segments. Companies that can validate performance claims and streamline qualification processes are likely to capture a larger share of this shifting demand.
A related opportunity is in compounding and system-level value addition. As customers seek to reduce total cost and improve reliability, suppliers that can provide guidance on formulation, processing, and integration may strengthen their position beyond the base material level. This creates a path to differentiation that is less dependent on volume alone and more tied to solution quality.
Regional Capacity Realignment and Supply Security as a Competitive Factor
Regional supply dynamics are likely to become more important as customers prioritize continuity and cost predictability. Where feedstock pricing is volatile or logistics are constrained, suppliers with diversified production footprints, regional sourcing, or strong inventory and delivery capabilities can gain preference even if they are not always the lowest-cost option. This trend favors strategic capacity planning and long-term supplier relationships.
Acrylic Fibers Market
For producers, the opportunity is to align capacity investments with regional demand patterns and feedstock access. For buyers, the opportunity is to reduce exposure to single-source risk by qualifying multiple suppliers or securing long-term agreements that provide stability during tight periods. In both cases, supply security is becoming a value driver rather than just an operational concern.
Regulatory and Energy Cost Sensitivity as a Planning Variable
Regulatory and energy-related developments will continue to influence cost structures and regional competitiveness. Even when changes are not specific to acrylic rubber, they can alter the economics of production and processing, especially in energy-sensitive operations. Firms that incorporate regulatory and energy cost monitoring into planning will be better equipped to anticipate shifts in relative competitiveness and adjust sourcing, pricing, or capacity strategies accordingly.
The commercial opportunity here is in flexibility and foresight. Companies that scenario-plan around energy and transmission cost changes, feedstock movements, and policy adjustments can make more informed decisions about where to produce, how to price, and when to lock in supply agreements. This proactive posture can reduce surprises and improve margin resilience over time.
Risks and Uncertainties to Watch
Despite the positive trajectory, several risks could alter outcomes. Raw material cost spikes or prolonged supply constraints could compress margins and disrupt delivery commitments, especially for firms without effective hedging or sourcing alternatives. Demand patterns could shift more quickly than expected if end-use industries accelerate material substitution or if project cycles change in construction and energy-related applications. Regulatory or energy transmission changes could also affect regional cost competitiveness in ways that are difficult to predict with precision.
In addition, competitive intensity in standard grades may increase as suppliers seek volume to utilize capacity, potentially pressuring price and differentiation. In such an environment, strategic clarity matters: firms need to decide where they can win on performance, where they can win on supply reliability, and where they may be better served by repositioning away from commoditizing segments.
Strategic Guidance for Decision-Makers
For manufacturers, investors, and procurement teams, the market presents a mix of growth potential and complexity. The most effective responses will depend on role, risk tolerance, and time horizon, but several priorities are broadly relevant.
For Manufacturers and Material Suppliers
Focus on performance differentiation and application-specific value rather than competing primarily on base material price. Align product development with demanding use cases where heat resistance, oil resistance, and service life are decisive. Evaluate capacity and sourcing strategies with feedstock volatility in mind, and consider whether regional diversification or long-term supplier agreements can improve stability. Where possible, strengthen technical support and qualification capabilities, since these often determine customer preference in performance-driven segments.
For Investors and Strategic Planners
Assess the market with attention to product mix, regional footprint, and exposure to feedstock cost movements. Companies with stronger high-performance grade portfolios and diversified production capabilities are generally better positioned to defend margins and capture demand shifts. Track energy and regulatory developments as part of the investment thesis, since they can influence cost structures and regional competitiveness over time. Look for signs of strategic alignment between capacity deployment and demand geography, as well as evidence of technical leadership that can sustain pricing power.
For Procurement and Procurement-Led Organizations
Treat supply security and performance consistency as core evaluation criteria alongside cost. Where applications are critical, qualify multiple suppliers and consider long-term agreements that reduce exposure to intermittent tightness in feedstocks or logistics. Evaluate total system value rather than unit price alone, including service life, failure risk, and processing compatibility. In a market where raw material costs can move unevenly across regions, a diversified sourcing strategy can provide both cost and continuity benefits.
Conclusion: Positioned for Growth, but Requiring Strategic Discipline
The acrylic rubber market is moving into a phase where growth and competitive differentiation are increasingly intertwined. Aggregate expansion through 2032 is supported by demand from automotive, industrial, and specialty applications, but the real value will be captured by firms that can navigate raw material volatility, meet higher performance expectations, and adapt to regional and regulatory shifts. Concentration among leading suppliers gives the market structure and stability, yet it also raises the bar for new entrants and reinforces the importance of technical credibility, supply reliability, and application-focused solutions.
For executives and investors, the key is to look beyond headline market size and understand where performance, geography, and supply chain design are creating durable advantages. Detailed segment-level data, regional cost analysis, and tailored scenario planning can make these decisions sharper and more confident. For those seeking deeper granularity on product segments, regional dynamics, and customized strategic recommendations, the full PW Consulting research report provides a more detailed decision-making framework built around these market forces.
For detailed analysis of this topic, please visit the official page: Acrylic Rubber Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


