



USB Wall Charger Market 2026: Why 3.9% CAGR and USB-C Shift Redefine Growth

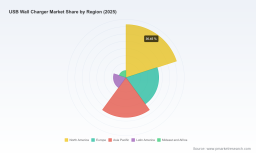
The USB Wall Charger Market: Strategic Trends and Commercial Opportunities Through 2032
The global USB wall charger market has entered a phase of measured expansion, with total revenue projected to grow from approximately 1,611 million in 2025 to nearly 2,096 million by 2032, representing a compound annual growth rate of 3.9 percent. This trajectory reflects a market that is no longer driven primarily by raw device proliferation but by structural shifts in charging architecture, regulatory intervention, and consumer expectations around speed, size, and interoperability. After navigating a period of pandemic-era supply volatility and subsequent normalization, the sector now faces a more nuanced competitive environment where technological maturity, compliance readiness, and material cost discipline determine commercial outcomes. For executives, investors, and procurement leaders, the next several years will reward organizations that align product roadmaps with standardized power delivery frameworks, optimize bill-of-materials economics, and anticipate how regional mandates reshape distribution and product mix. Understanding these dynamics is essential for positioning in a category where incremental wattage gains, form-factor compression, and ecosystem alignment increasingly dictate shelf space and margin structure.
Market Landscape and Core Challenges
The base-year valuation of 1,611 million in 2025 sits at the inflection point between legacy charging ecosystems and the next generation of high-capacity, multi-port adapters. The broader trajectory from 2020 through 2032 indicates steady, if unspectacular, expansion, with the 2026-2032 period expected to deliver consistent top-line growth rather than explosive acceleration. This pattern signals a maturing category where replacement cycles, upgrade-driven purchases, and professional-grade power needs contribute more to revenue than the early smartphone adoption surge. At the same time, the market is fragmenting along lines of power class, connector architecture, and regional compliance requirements, creating both pricing pressure and differentiation opportunities. The competitive structure remains moderately concentrated, with leading portfolios capturing meaningful share while numerous mid-tier and regional players compete on price, speed-to-market, and accessory bundling. This concentration level suggests that scale advantages in component procurement, certification velocity, and channel relationships matter, but they do not eliminate room for targeted innovation in form factor, thermal management, and device-specific optimization.
Several structural challenges define the current operating environment. First, the transition from proprietary fast-charging standards to unified power delivery frameworks is compressing legacy product lines while raising the engineering bar for compliance, safety, and thermal control. Manufacturers that rely on older USB-A-centric architectures or region-specific proprietary protocols face incremental revenue erosion as end-users and device makers converge on common interfaces. Second, regulatory momentum is reshaping product mandates with operational consequences for design cycles, inventory planning, and certification spend. Legislation requiring standardized connectors for a broad range of handheld and computing devices has already begun altering the mix of chargers shipped into key European markets, and the subsequent extension of similar requirements to laptops introduces new power-class demands and documentation requirements. Third, material and manufacturing economics are creating a bifurcated cost structure. Standard polymer enclosures remain inexpensive, but premium housings made from polycarbonate or machined aluminum carry materially higher per-unit costs and introduce machining complexity that affects lead times and margin sensitivity. Companies must therefore decide whether to compete in the cost-optimized volume segment, the premium durability segment, or a hybrid positioning that balances material choice with perceived value.
Key Drivers Reshaping the Category
Technology Innovation and Power Architecture Breakthroughs
Power density and thermal efficiency have become the primary technical battlegrounds. The shift toward gallium nitride-based semiconductors and advanced controller architectures enables higher wattage outputs in smaller physical footprints, directly addressing consumer and professional demand for compact yet high-capacity adapters. Controller ICs that manage USB power delivery negotiation, buck-boost transitions, and safety thresholds are critical enablers, allowing manufacturers to support expanded power classes without sacrificing reliability or increasing component count. Recent reference designs for 240-watt applications illustrate how integrated solutions are reducing time-to-certification and simplifying multi-port architectures for devices such as e-bikes, power banks, and portable stations. On the sink side, hybrid controllers with refined negotiation algorithms are improving compatibility across premium chargers and a wider array of devices, reducing handshake failures and enhancing user experience. These advances are not merely incremental; they are reshaping the engineering economics of charger design by compressing size, improving efficiency, and supporting higher power classes that previously required larger, heavier, and more costly assemblies.
Policy and Regulatory Environment as a Market Mover
Regulatory mandates are no longer peripheral considerations; they are now central to product strategy and regional portfolio planning. The EU common charger directive has already required USB-C ports for a defined set of handheld mobile phones, tablets, and digital cameras since late 2024, and the mandate extends to laptops in April 2026. This shift is accelerating the phase-out of legacy dedicated connectors and reinforcing USB-C as the de facto interface for a large share of consumer electronics. The compliance timeline is equally important. The USB-IF has extended a grace period for certain silicon and end-products under the compliance program, providing manufacturers additional runway to align designs, complete testing, and ship certified units without disruptive discontinuity. These policy dynamics create a dual effect: they reduce fragmentation in the long term while introducing near-term obligations for documentation, certification, and product-mix adjustments. For companies with multi-region distribution, the challenge is to synchronize engineering roadmaps with evolving regional requirements without overcommitting inventory to transitional SKUs.
Demand-Side Shifts in Consumer and Professional Behavior
Consumer expectations have moved beyond basic charging to a combination of speed, portability, and multi-device convenience. Users increasingly prefer single adapters that can serve a smartphone, tablet, and wearable simultaneously, which elevates the importance of intelligently distributed multi-port outputs and intelligent load balancing. At the same time, professional and prosumer segments are demanding higher wattage for demanding peripherals and mobile workstations, expanding the addressable use cases beyond everyday personal devices. This behavioral shift influences not only product specifications but also packaging, accessory bundling, and retail positioning. A charger that appears interchangeable on a shelf may in practice be selected based on port configuration, cable compatibility, and device ecosystem alignment, making clear value communication and interoperability assurance important purchase drivers.
USB Car Chargers Market
Supply Chain and Cost Structure Dynamics
BOM economics are exerting growing influence on product positioning and margin strategy. Casing material choices directly affect unit cost, perceived quality, and thermal performance, forcing design teams to weigh the trade-offs between cost-efficient polymer enclosures and higher-cost polycarbonate or aluminum options. Beyond housings, the availability and pricing of semiconductor components, magnetics, and passive elements shape lead times and price sensitivity, especially during cycles of component allocation or freight volatility. Companies with resilient sourcing strategies, flexible manufacturing footprints, and disciplined cost engineering are better positioned to maintain stable pricing while still advancing performance. In this environment, margin preservation increasingly depends on component standardization, design reuse across wattage tiers, and the ability to absorb certification costs across a broader volume base.
Competitive Landscape and Leading Strategies
The competitive field blends consumer-focused power brands, component and controller specialists, and regional players with strong retail channel presence. Consumer-oriented leaders have built recognizable portfolios around GaN efficiency, multi-port designs, and integrated fast-charging protocols, often emphasizing power class flexibility and compact form factors as the core differentiators. These players tend to compete on brand trust, retail visibility, accessory ecosystems, and the clarity of their power-delivery claims. In parallel, semiconductor and controller companies provide the underlying intellectual property and reference architectures that enable advanced chargers, effectively shaping the performance ceiling for the broader industry. Their product releases, reference designs, and compliance-oriented specifications influence design timelines and certification pathways for numerous downstream manufacturers. This division of roles means that end-product brands and component suppliers are interdependent: charger makers rely on controller innovation to reach higher power classes and smaller sizes, while controller suppliers depend on broad adoption to amortize development investment.
USB Wall Socket Market
Strategy differentiation is increasingly evident in how companies balance performance, compliance, and cost. Some leaders focus on premium multi-port GaN chargers with refined thermal design and clear power-delivery branding, aiming for higher-margin retail and accessory-channel sales. Others target a broad volume position with a range of wattage classes and port configurations, emphasizing price accessibility and wide device compatibility. A separate segment pursues professional-grade or specialized power solutions, leveraging stricter safety expectations and application-specific engineering as barriers to entry. The strategic tension lies in choosing the right mix of wattage tiers, port architectures, and housing materials to match a chosen customer base without diluting brand positioning. Companies that succeed typically combine disciplined certification readiness, modular design approaches that scale across power classes, and clear product storytelling that connects technical capability to real-world convenience.
The landscape is also evolving through consolidation pressure and targeted entry. Larger consumer-electronics ecosystems can leverage accessory bundling, cross-device compatibility messaging, and established distribution to capture share, while smaller brands attempt to gain traction through specialized features, niche wattage classes, or regional retail strength. At the same time, component suppliers continue to influence competitive outcomes by introducing controllers and reference designs that reduce engineering risk and accelerate compliance. New entrants face a higher bar today than in earlier growth cycles because certification complexity, regulatory alignment, and component cost discipline require more capital and process maturity. The result is a market where differentiation increasingly comes from execution reliability, interoperability assurance, and the ability to move efficiently across power classes without sacrificing safety or user experience.
Forward Outlook: Trends and Commercial Implications
Trend 1: Wider Adoption of High-Power USB-C and Multi-Port Architectures
The next several years will see broader deployment of higher-wattage USB-C adapters and more sophisticated multi-port configurations as laptops, mobile workstations, and demanding peripherals converge on common interfaces. This trend expands the addressable market for premium power classes and encourages modular design strategies that allow manufacturers to reuse core architectures across multiple wattage tiers. Commercial opportunity lies in developing clear product ladders that connect everyday charging needs with professional-grade scenarios, enabling upsell pathways and reducing SKU fragmentation. The risk is that power-class competition can become hypersensitive to price if differentiation is confined to wattage alone, so brands will need complementary value such as thermal performance, cable compatibility assurance, and intelligent port distribution.
PW Consulting Health Care Research Center
Trend 2: Regulatory Harmonization Reducing Fragmentation but Raising Compliance Costs
As common charger requirements take hold across more device categories and regions, the long-term effect should be reduced interface fragmentation and greater interchangeability. In the near term, however, companies must invest in certification, documentation, and portfolio rationalization to align with evolving mandates. The opportunity is to standardize on future-proof architectures that minimize redesign exposure and simplify regional distribution. The risk lies in transitional mismatch: products designed for legacy requirements may lose relevance faster than anticipated, while overinvestment in transitional SKUs can trap working capital. Timing compliance investments to actual device-category mandates, rather than speculative requirements, will be a key discipline.
Trend 3: Premiumization vs. Cost-Optimized Volume as Parallel Paths
Market growth will not be uniform across all price points. A premium segment will continue to expand around durability, higher power density, refined aesthetics, and specialized multi-device scenarios, while a volume segment will remain highly sensitive to materials, component costs, and retail pricing pressure. This bifurcation creates an opportunity for companies to define a deliberate positioning rather than drifting between tiers. Brands that commit to a clear cost strategy and product architecture can protect margins more effectively than those that attempt to serve both extremes without distinct engineering and sourcing plans. The uncertainty is that raw material and semiconductor cost cycles can compress available headroom in either segment, requiring continuous BOM optimization and disciplined inventory planning.
Actionable Recommendations for Decision-Makers
For manufacturers, the most consequential move is to align product roadmaps with standardized power delivery architectures and the certification timelines that accompany them. Designing for modular reuse across wattage classes, prioritizing controller and reference-design partnerships that reduce engineering risk, and choosing enclosure materials based on a deliberate positioning strategy will help balance performance, compliance, and cost. It is equally important to manage SKU breadth carefully; too many overlapping configurations can dilute manufacturing efficiency and confuse retail positioning, while too few can leave gaps in multi-port and high-power demand segments. Establishing a clear product ladder that connects everyday consumer needs with professional use cases can improve channel clarity and margin resilience.
For investors, the priority is to evaluate exposure to the underlying structural drivers rather than short-term shipment noise. Companies with credible certification readiness, disciplined BOM economics, and a defined strategy across power classes are better positioned to capture share as the category matures. Attention should also be paid to exposure in regions where regulatory mandates are accelerating interface standardization, because those markets reward compliance capability and penalize late portfolio adjustments. Investment theses should account for the fact that competitive advantage increasingly derives from execution reliability, thermal and safety engineering, and the ability to scale modular designs efficiently, not simply from being first to announce a wattage claim.
For procurement and channel decision-makers, the emphasis should be on interoperability assurance, compliance documentation, and supply stability. Selecting partners with transparent certification status and consistent quality practices reduces downstream risk for retail, enterprise, and service-channel deployments. Procurement strategies should also consider total cost of ownership, including the implications of enclosure material choices, port configuration relevance, and whether a supplier’s portfolio can adapt as laptop and high-power device requirements expand through 2026 and beyond. Building relationships with suppliers that can provide consistent availability across multiple wattage tiers and port architectures helps mitigate the risk of sudden SKU discontinuation or compliance-driven repricing.
Detailed segmentation data, regional revenue splits, application-level breakdowns, competitive benchmarking, and company-level profiles can sharpen these decisions further by revealing where growth is concentrated and how individual players are positioning across power classes and compliance timelines. For teams that need granular forecasts, scenario modeling, or tailored portfolio guidance, access to the full research report provides the level of detail required to translate these market-level insights into operating decisions.
For detailed analysis of this topic, please visit the official page: USB Wall Charger Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


