



The Real Drivers Behind the Washing Machines Market’s 3.7% Growth Trajectory to 2032

The Washing Machines Market at an Inflection Point: Strategic Trends and Commercial Opportunities Through 2032
The global washing machines market has entered a phase of measured expansion, shaped by macroeconomic resilience, accelerating product innovation, and tightening regulatory frameworks. From 2020 through 2025, the sector moved from approximately US$163.15 million to roughly US$215.0 million, reflecting steady demand recovery, replacement cycles, and gradual premiumization. Looking ahead to the forecast period of 2026 through 2032, the market is projected to climb toward US$344.8 million, anchored by a compound annual growth rate of 3.7 percent. This trajectory signals more than incremental growth; it indicates a structural shift in how appliances are designed, sold, and integrated into broader home and commercial ecosystems.
For executives, strategic planners, and investors, the question is no longer whether the market will expand, but how value will be allocated across regions, product architectures, and capability sets. Revenue concentration remains relatively moderate, with the top three players accounting for about 38.2 percent of the market and the top five reaching roughly 40.8 percent. This level of dispersion suggests that competitive advantage will increasingly derive from differentiated technology, service ecosystems, and regional execution rather than scale alone. The following analysis unpacks the operational realities behind the numbers and maps practical pathways for capturing growth.
Market Reality and Core Challenges
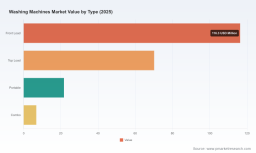
The market’s headline expansion masks several operational tensions that decision-makers must navigate. First, the industry is confronting a product architecture transition. Front-load designs continue to command the largest share of revenue, while top-load units retain relevance in price-sensitive and space-constrained segments. Portable and combo configurations represent smaller but strategically important niches, particularly where multi-functional appliances or limited installation footprints shape purchasing decisions. The commercial segment, though smaller than residential, carries distinct performance expectations around durability, throughput, and serviceability. Understanding where volume concentrates versus where margins accrue is essential for portfolio planning.
Second, regulatory momentum is reshaping engineering and compliance roadmaps. In the United States, mandatory energy conservation standards for consumer clothes washers took effect in February 2025, with product testing requirements beginning in July 2025. These requirements raise the floor for efficiency and force manufacturers to validate performance under stricter measurement protocols. For companies with broad SKU counts and fragmented supply chains, compliance adds cost and complexity. For others, it creates a barrier that rewards already-modernized production lines and advanced control systems.
Third, the market faces a profitability paradox. Unit growth is being driven partly by replacement demand and partly by feature-led upgrades, but component costs, logistics volatility, and the expense of integrating smart functionality can compress margins if not managed deliberately. The challenge is to convert technological investment into perceived value that customers will pay for, rather than allowing innovation to become a cost center absorbed through price competition. The strategic task is to align product roadmaps with willingness-to-pay, service economics, and regional purchasing behavior.
Core Drivers Reshaping the Market
Several interconnected forces are determining where growth will concentrate and which capabilities will separate winners from followers.
Technology Innovation and Smart Differentiation
Artificial intelligence and connected control systems are moving from premium add-ons to core design elements. Recent product introductions illustrate how rapidly functionality is advancing. In January 2026, Samsung expanded its Bespoke AI Laundry Combo line with upgraded AI Wash & Dry + optimization, faster wash-to-dry performance, and refined voice controls. Earlier, in October 2025, LG introduced the AI DD 2.0 series with fabric and soil auto-detection supported by 20,000 optimized wash patterns, and later showcased its Signature Series with AI load sensing. Haier followed in September 2025 with the Candy ProWash 750, combining an advanced user interface with an automatic detergent dosing system and camera-guided wash optimization. These launches share a common theme: machines are becoming adaptive rather than static, using sensors, software, and user-facing intelligence to improve outcomes while reducing manual input.
For commercial players, the same logic applies in a different register. Intelligent cycle selection, load-based resource management, and remote diagnostics can improve uptime and reduce operating cost, especially in multi-unit or high-frequency environments. The strategic implication is that software capability, sensor integration, and user experience are becoming as important as mechanical reliability. Companies that can iterate quickly on firmware, integrate third-party smart home ecosystems, and maintain robust after-sales support will be better positioned to defend pricing and build loyalty.
Policy and Regulatory Environment
Regulation is not simply a constraint; it is a re-architecturing force. The U.S. Department of Energy standards effective from February 2025, with testing required from July 2025, illustrate how compliance deadlines can synchronize product refreshes and supplier qualification cycles. In parallel, efficiency labeling and eco-cycle expectations are influencing design priorities across multiple markets, pushing manufacturers toward better insulation, optimized water usage, and smarter heating and motor control. The practical effect is a market in which efficiency is increasingly table stakes, and differentiation must come from user convenience, durability, and service.
This environment favors players who can modularize efficiency improvements and reuse validated components across regions. It also rewards early investment in testing infrastructure and documentation, since compliance delays can disrupt launch timing and inventory planning. For strategic planners, policy cycles should be treated as design inputs rather than after-the-fact adjustments.
Demand-Side Behavior and Use-Case Evolution
Consumer and commercial buying behavior is shifting around convenience, fabric care, and total cost of ownership. Households are increasingly interested in appliances that reduce manual effort, preserve clothing quality, and integrate with broader home routines. At the same time, commercial operators focus on throughput, robustness, and service contracts. This divergence creates an opportunity for market participants to segment more intelligently rather than compete on broad specifications alone.
A notable example of use-case innovation is Haier Europe’s Multi Wash concept, unveiled at IFA 2025, which uses three independent drums for advanced laundry performance. While still a specialized offering, it signals a broader direction: appliances are being reimagined around how people actually do laundry, including separating loads, handling different fabrics simultaneously, and reducing cycle handling. Whether such concepts scale widely or remain niche, they demonstrate that market leaders are willing to redesign form factors around user workflows rather than simply improve incremental specifications.
Supply Chain and Cost Structure Dynamics
Cost structures are being recalibrated by material pricing, energy usage, and the economics of smart component integration. Motors, control boards, sensors, and connectivity modules all contribute to both performance and expense. Companies that can standardize high-value sub-systems, localize sourcing where feasible, and manage lifecycle cost through durable design will have more room to invest in features that customers value. At the same time, the commercial side of the market introduces different logistics and installation considerations, meaning that supply chain design must reflect regional service density as much as component availability.
The strategic message is that cost management and innovation are no longer separate tracks. Efficient engineering, shared platforms, and disciplined SKU rationalization can fund the differentiated capabilities that protect margin. In contrast, fragmented product lines with overlapping specifications increase complexity without improving customer perception.
Parts Washer Market
Competitive Landscape and Leading Strategies
The competitive set spans global consumer-electronics champions, established appliance manufacturers, and regionally strong specialists. Each group is pursuing a slightly different value proposition, and the market’s moderate concentration leaves room for multiple successful models.
Differentiated Positioning Among Leading Players
Samsung is leaning into integrated AI laundry and voice-enabled convenience through its Bespoke AI Laundry Combo, emphasizing faster performance and adaptive wash-and-dry optimization. This approach aligns with a broader consumer-electronics mindset in which appliances are part of a connected home experience and brand loyalty is reinforced through software and ecosystem integration.
LG is emphasizing fabric intelligence and wash-pattern breadth. With the AI DD 2.0 series, the company highlights automatic detection of fabric weight, type, and soil, combined with a large library of optimized wash patterns and load-sensing capabilities in its Signature Series. The strategic signal is that superior care outcomes and customization can justify premium positioning and strengthen retention in segments where laundry quality matters.
Home Appliances Market
Whirlpool continues to focus on practical high-efficiency solutions for mainstream consumers, with top-load and front-load models built around user-friendly dispensing and freshness-focused technology. This positions the company around ease of use, broad compatibility, and reliability in volume-oriented segments.
Robert Bosch GmbH brings a European engineering orientation, with automatic detergent and softener dosing and advanced user interfaces designed to balance performance with convenience. This suggests a strategy rooted in precision, usability, and credibility in markets where efficiency and feature maturity are closely scrutinized.
AB Electrolux emphasizes energy-efficient front-load models aligned with stringent efficiency recognition, appealing to buyers for whom operating cost and environmental performance are decisive. Haier and Midea are expanding smart, large-capacity, and multi-configuration offerings, combining global scale with varied product architectures. IFB Industries contributes compact and standard front-load solutions with efficiency features, serving segments where footprint and cost efficiency matter. Toshiba and Panasonic continue to advance integrated smart solutions and AI-optimized efficiency, reflecting the broader industry shift toward intelligent, low-consumption appliances.
Market Structure Evolution
The landscape is evolving along two parallel tracks. On one hand, leading multinationals are deepening technology integration and brand ecosystems, using smart features, service networks, and regional adaptations to defend share. On the other hand, specialized manufacturers and regional players can win by focusing on narrow use cases, cost-efficient engineering, or strong local service relationships. Consolidation pressure exists, particularly where overlapping SKUs and rising compliance costs strain smaller players, but fragmentation persists because regional preferences, installation conditions, and commercial requirements differ widely.
New entrants and line extensions are also reshaping expectations. Speed Queen, for example, expanded its portfolio with enhanced lid-lock mechanisms and extra-large capacity options, indicating continued attention to robustness and capacity among customers who prioritize durability and high-volume performance. Such moves show that even within a concentrated competitive field, targeted product extensions can open or reinforce distinct positions.
Forward Outlook: Trends Shaping 2026 to 2032
Several trends are likely to define the next phase of market development and point toward concrete commercial opportunities.
AI-Enabled Performance as a Purchasing Criterion
As machine intelligence becomes more visible in everyday use, buyers will increasingly compare appliances on adaptive performance, not just drum size or exterior design. This creates opportunities in differentiated wash programs, automated dosing, and service features that reduce user friction. It also raises the importance of software support, update pathways, and user interface clarity. Companies that can demonstrate measurable care outcomes and long-term reliability of smart functions will be better positioned to sustain pricing power.
Efficiency-First Design Becoming the Norm
With regulatory standards raising the baseline and consumers becoming more cost-conscious, efficiency will move from a selling point to a requirement. The commercial opportunity lies in making efficiency tangible: lower operating cost, better cycle optimization, and durable components that reduce total cost of ownership. Manufacturers that can package efficiency with convenience will have an advantage, because the most efficient appliance is not always the most attractive if it complicates daily use.
PW Consulting
Use-Case Specialization and Multi-Function Form Factors
Innovations such as multi-drum concepts, combo washer-dryer solutions, and larger-capacity smart models indicate growing interest in matching appliance architecture to real laundry behavior. This may lead to greater segmentation by household type, spatial constraint, and user routine. Commercial opportunities include tailored portfolios for small living spaces, multi-person households, and commercial settings with distinct throughput needs. The risk is over-fragmentation: too many niche configurations can complicate manufacturing, inventory, and service. The winners will likely be those who balance specialization with platform discipline.
Potential Risks and Uncertainties
Several factors could alter the trajectory. Regulatory timelines may shift or be enforced differently across markets, affecting launch planning and cost structures. Component availability and logistics can still introduce volatility, especially for smart subsystems and specialized motors. Consumer willingness to pay for advanced features may vary by region and economic conditions, meaning that premiumization is not guaranteed to spread uniformly. Finally, if software-driven differentiation is not matched by reliable after-sales support and clear user benefits, there is a risk that smart features become a source of dissatisfaction rather than advantage.
Actionable Recommendations for Decision-Makers
The market’s direction suggests that value creation will come from aligning product strategy with user outcomes, compliance readiness, and disciplined execution. The following recommendations are tailored by role.
- For manufacturers and product strategists, prioritize platform-based development that allows efficiency improvements and smart features to be shared across models without exploding SKU complexity. Treat regulatory deadlines as design inputs, and build testing and validation capacity early so that compliance does not become a bottleneck. Invest in sensor and software capabilities that translate into measurable care, convenience, and durability benefits, and make sure service teams are equipped to support connected functions over the product lifecycle.
- For investors and corporate development teams, focus on companies with clear differentiation in either intelligent performance, efficiency leadership, or regional service strength. Moderate market concentration means that execution quality, portfolio discipline, and regional adaptation can matter as much as scale. Evaluate exposure to compliance-driven cost inflation, supply chain resilience for smart components, and the credibility of software roadmaps, since these factors will influence margin stability and repeat purchase behavior.
- For procurement leaders and commercial operators, align specifications with actual use patterns rather than generic premium features. In residential contexts, prioritize ease of use, fabric care, and total cost of ownership; in commercial settings, emphasize durability, throughput, serviceability, and contract support. Procurement strategies should also account for regulatory compliance timelines and the operational implications of connected appliances, including data handling, maintenance planning, and lifecycle updates.
For teams that need a deeper operational view, a fuller research report can provide more granular segmentation, regional nuance, and tailored recommendations that go beyond the market-level picture. Detailed breakdowns of product architectures, commercial versus residential dynamics, regional execution considerations, and company-specific positioning can help translate these strategic themes into concrete investment, sourcing, and product decisions.
For detailed analysis of this topic, please visit the official page: Washing Machines Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


