



Pulmonary Function Testing Systems Market: Why 6.8% CAGR and COPD Drivers Change Everything

The Pulmonary Function Testing Systems Market: Strategic Trends and Commercial Opportunities Through 2032
The global pulmonary function testing systems market has entered a phase of sustained expansion, with total revenue projected to reach approximately $5.95 billion by 2032. This trajectory reflects a compound annual growth rate of 6.8% across the 2026–2032 forecast period, building on a market base that surpassed $3.7 billion in 2025. The growth is not merely a function of incremental demand; it signals a structural shift in how respiratory diagnostics are deployed across clinical, occupational, and decentralized care settings. Equipment that once lived exclusively in hospital pulmonary labs is now being adapted for primary care, home monitoring, and clinical trial environments, driven by tighter diagnostic protocols, evolving reimbursement models, and a wave of technology miniaturization.
For executives, investors, and procurement leaders, the market presents a dual reality: steady top-line growth alongside intensifying competition for specific use cases. The challenge is no longer whether pulmonary function testing will grow, but where value will concentrate, which product configurations will win procurement contracts, and how regulatory and reimbursement pressures will reshape margins. Understanding these dynamics requires moving beyond headline figures and examining the underlying drivers, competitive moves, and emerging risk vectors that will define the next five years.
Market Landscape and Structural Challenges
The market's expansion has been broad-based, but the composition of demand reveals clear Concentration patterns and pressure points. Pulmonary function testing systems span a diverse equipment set, including spirometers, peak flow meters, gas analyzers, oximeters, and associated diagnostic platforms. This breadth creates both opportunity and fragmentation: buyers increasingly expect integrated solutions rather than standalone instruments, while manufacturers must balance specialization with system-level interoperability. In practice, the market is transitioning from a device-centric model to a workflow-centric one, where accuracy, data connectivity, and compliance documentation carry as much commercial weight as raw measurement performance.
Fragmented Demand and Integration Pressure
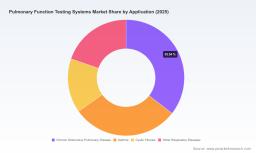
One of the defining characteristics of the current market is the uneven distribution of demand across clinical applications. Chronic respiratory conditions, asthma management, cystic fibrosis monitoring, and a wider set of respiratory diseases each pull equipment requirements in different directions. For example, an asthma-focused program may prioritize portable peak flow and spirometry tools with patient-friendly interfaces, while a cystic fibrosis center may require more comprehensive lung volume and gas exchange capabilities. This segmentation makes it difficult for any single product architecture to dominate every setting, and it forces manufacturers to develop modular portfolios or risk missing high-value niches.
PW Consulting Health Care Research Center
At the same time, hospitals and diagnostic networks are consolidating procurement around platforms that can reduce training burden, standardize quality control, and integrate with electronic health records. The result is a market where incumbents with established clinical reputations retain advantages, but new entrants with stronger software ecosystems and simpler device form factors can gain traction in specific customer segments.
Regulatory Compliance as a Strategic Filter
Regulatory and certification requirements are becoming a significant filter in procurement decisions, particularly in regulated healthcare markets. Pulmonary function equipment must increasingly align with international standards for spirometry and lung volume measurement, and reimbursement pathways often depend on demonstrated compliance with accepted clinical protocols. In parallel, infection control expectations for reusable equipment have tightened, with accreditation bodies emphasizing documented cleaning, disinfection, and sterilization procedures consistent with the Spaulding classification. This creates a compliance burden that small or under-resourced manufacturers may struggle to absorb, while also rewarding companies that can provide clearer validation packages and service support.
Reimbursement Stability and Margin Constraints
While clinical demand continues to expand, reimbursement structures remain a critical determinant of commercial viability for many deployment models. Medicare Physician Fee Schedule pricing for common pulmonary function testing codes has provided a baseline of predictability, but the rates do not automatically translate into strong equipment margins, especially for high-volume, lower-acuity testing. Providers must weigh capital cost, maintenance, and workflow efficiency against reimbursement levels that differ across codes and care settings. This tension encourages buyers to favor equipment that enables faster throughput, fewer repeated tests, and more reliable data capture, reinforcing the strategic importance of system reliability and software usability.
Key Drivers Shaping Market Direction
Technology Innovation and Device Miniaturization
The most visible driver of market change is the ongoing miniaturization and digitization of pulmonary function equipment. Compact spirometers, connected oximeters, and smartphone-compatible testing devices are expanding the practical boundaries of where testing can occur. This shift matters because it broadens the addressable use case set: primary care clinics can perform more standardized spirometry on site, occupational health programs can conduct field testing with portable units, and home-based monitoring can complement clinic visits for chronic disease management. Innovation is not limited to hardware size; it extends to workflow integration, wireless data transfer, and software-assisted quality control that helps reduce operator-dependent variability.
Recent product activity illustrates the direction of travel. In mid-2025, Vitalograph expanded its respiratory diagnostics portfolio through a strategic partnership with Thorasys, introducing the tremoflo C2 oscillometer at the Respiratory Diagnostics Summit. The move highlights a broader industry pattern: established diagnostic companies are extending beyond conventional spirometry into complementary measurement modalities that capture lung mechanics and airway resistance, thereby deepening their clinical value proposition. At the same time, Norav Medical launched a compact USB-powered spirometer designed for fast and accurate pulmonary analysis, with certifications aligned to international standards and regulatory requirements. The emphasis on compact form factors, certification readiness, and demonstration at a major trade event signals that portability and compliance are being pursued together rather than as separate priorities.
Policy, Certification, and Quality Standards
Policy and standards environments are shaping both market access and competitive differentiation. Equipment classification under medical device regulations, conformity assessment pathways, and international standards for spirometry and lung volume measurement have become central to procurement eligibility in many healthcare systems. Buyers are increasingly looking for documented alignment with recognized standards because it simplifies internal validation, supports accreditation, and reduces the risk of audit findings. In practice, this means that certification is not merely a regulatory checkbox; it is a commercial asset that can shorten sales cycles and strengthen positioning in tenders and group purchasing environments.
The same logic applies to infection control expectations. As accreditation standards reinforce the need for disciplined reprocessing of reusable equipment, manufacturers that provide clearer instructions, validated cleaning workflows, and Accessories that support safe handling can differentiate themselves in hospital and clinic markets. This is a subtle but meaningful shift: product performance alone no longer defines leadership; operational support and compliance documentation increasingly do.
Demand-Side Shifts in Care Delivery
On the demand side, pulmonary function testing is benefiting from broader changes in respiratory care delivery. Rising awareness of chronic obstructive pulmonary disease, asthma control, and other respiratory conditions is encouraging earlier and more frequent testing in both specialty and general practice settings. At the same time, the growth of decentralized and home-based care models is creating new expectations for equipment that can be used outside traditional lab environments without sacrificing data quality. Clinical research is also a growing application area, where pulmonary function endpoints must be collected consistently across sites and often integrated with other physiologic measurements.
This demand evolution is pushing manufacturers toward solutions that are easier to deploy, simpler to interpret, and more compatible with distributed care workflows. For buyers, the implication is that equipment selection is increasingly influenced by total cost of ownership and workflow fit, not just measurement accuracy in a controlled setting. For manufacturers, it means that winning products are those that reduce friction across the testing pathway, from patient intake to result documentation.
Supply Chain and Cost Structure Realignment
Cost structures across the industry are being reshaped by component availability, manufacturing scale, and software development intensity. As devices become more connected and standards compliance more demanding, the cost of quality systems, certification preparation, and post-market support grows. At the same time, buyers are increasingly price-conscious in lower-acuity settings, putting pressure on manufacturers to balance feature richness with affordability. This environment favors companies that can achieve reliable scale, standardize core platforms, and invest selectively in differentiated capabilities rather than attempting to compete across every price tier simultaneously.
The practical effect is a market in which some suppliers are consolidating around stronger platform architectures while others focus on specialized, high-touch applications. This reallocation of resources is visible in product launches and partnership activity, where the emphasis is often on expanding clinical reach through targeted capability additions rather than broad, undifferentiated expansion.
Competitive Landscape and Evolving Strategies
The competitive field includes established diagnostic manufacturers with strong clinical reputations and a growing set of smaller or regionally focused players that compete through portability, affordability, and software usability. Companies such as Vitalograph, Jaeger Medical, MGC Diagnostics Corporation, Norav Medical, and MIR Medical International Research each illustrate a distinct strategic posture within the same overall market.
Incumbent Positioning and Differentiated Strengths
Larger, clinically entrenched manufacturers tend to compete on completeness of offering, diagnostic reliability, and integration with laboratory or hospital workflows. Their advantage lies in established relationships with pulmonary function labs, familiarity among clinicians, and the ability to deliver system-level solutions that span multiple measurement types. In this context, strategic moves are often about deepening the portfolio rather than simply broadening it. For example, the introduction of oscillometry capabilities alongside existing spirometry and diagnostic platforms reflects an effort to serve a wider set of respiratory assessments without forcing customers to assemble multipurpose solutions from multiple vendors.
Agile and Access-Oriented Positioning
Other participants differentiate through compact devices, simplified operation, and compatibility with decentralized use. A USB-powered spirometer designed for rapid professional testing, or smartphone-compatible devices intended for both clinical and home settings, points to a strategy centered on accessibility and ease of deployment. These offerings are particularly relevant where procurement budgets are tighter, space is constrained, or testing must occur outside a dedicated pulmonary function laboratory. The commercial logic is not to win every high-complexity lab contract, but to capture volume in primary care, occupational health, and home monitoring pathways where convenience and cost matter disproportionately.
Regulatory and Certification-Led Differentiation
A third strategic thread is compliance-driven positioning. Manufacturers that align product development and documentation with recognized certification requirements and regulatory clearance pathways can use this alignment as a differentiator in regulated procurement environments. Recent FDA clearance activity for a wireless-integrated pulmonary function testing device intended for clinical trials underscores how regulatory milestones can open specific commercial doors, especially in research and specialized clinical use. In such cases, the clearance itself becomes part of the value proposition because it reduces buyer uncertainty and supports adoption in settings where regulatory confidence is essential.
Market Evolution: Consolidation, Fragmentation, and New Entry
Looking across these strategies, the market appears to be evolving through a combination of consolidation at the platform level and fragmentation at the application level. Larger players are strengthening system coherence and expanding modality coverage, while smaller firms continue to find room in portable, home-use, and price-sensitive segments. At the same time, new entrants with strong software, connectivity, or trial-focused capabilities can gain relevance by solving narrow but high-value problems rather than competing head-to-head across the entire equipment spectrum. The net effect is a market where broad incumbents and specialized challengers can coexist, provided each clearly defines the workflow problems it solves best.
Forward-Looking Trends and Commercial Implications
Trend One: Workflow-Integrated Diagnostics Will Outpace Standalone Devices
Over the next three to five years, pulmonary function testing is likely to be evaluated less as a collection of instruments and more as an integrated diagnostic workflow. Buyers will increasingly favor platforms that reduce manual steps, improve repeatability, and connect cleanly with record-keeping and quality assurance processes. This trend favors manufacturers that invest in software usability, data standardization, and service support, while pressuring those that rely primarily on hardware specifications to win deals. The commercial opportunity lies in packaging measurement capability with workflow reliability, so that testing becomes easier to scale across sites and staff configurations.
Trend Two: Decentralized Testing and Home-Based Monitoring Will Expand the Addressable Base
Decentralized care models and chronic disease management programs are expected to continue expanding the contexts in which pulmonary function testing is used. Compact, connected devices that can be deployed in primary care, occupational settings, and home environments will broaden the market's reach, but they will also introduce new requirements around patient training, data transmission, and result interpretation. Companies that can provide not only the device but also the supporting instructions, software, and service model will be better positioned to convert this expansion into durable revenue. The opportunity is significant, yet it depends on demonstrating that decentralized testing can deliver reliable data without adding operational burden.
Trend Three: Compliance and Standards Will Act as Both Gatekeeper and Advantage
As regulatory classification, certification expectations, and infection control standards remain central to procurement, compliance will function as both a barrier and a competitive lever. Manufacturers with mature quality systems and clear documentation will find it easier to enter or expand in regulated markets, while those with weaker compliance infrastructure may face longer adoption cycles or limited access to certain buyer groups. The risk here is twofold: compliance costs can compress margins if not managed efficiently, and any lapse in documentation or post-market support can quickly undermine trust in a market where clinical credibility is paramount. The upside is equally real, because strong compliance positioning can differentiate a product in tenders, group purchasing, and multi-site deployments.
Strategic Recommendations for Decision-Makers
For Manufacturers and Product Leaders
Focus product strategy on workflow fit as much as measurement performance. In practice, this means prioritizing software usability, data connectivity, and compliance documentation alongside hardware accuracy. Where portability or home use is a target, ensure that the complete offering—device, software, instructions, and support—is designed for non-specialist environments. Consider whether the portfolio should be extended through complementary modalities or consolidated around a stronger core platform, and treat certification and regulatory readiness as commercial enablers rather than back-office tasks.
FeNO Breathing Monitor Market
For Investors and Strategic Allocators
Evaluate opportunities with attention to deployment context and total cost of ownership rather than unit price alone. Segments that require broader system integration, stronger service networks, or specialized clinical validation may offer more durable positioning than commoditized low-complexity segments. Monitor moves that combine modality expansion, software connectivity, and regulatory milestones, since these often signal an intent to capture higher-value workflows. Also watch for consolidation patterns, because platforms that can serve multiple respiratory testing needs with reduced training and support burden may gain procurement preference over time.
Worldwide Lung Diffusion Gas (Pulmonary Diffusion Gas) Market
For Procurement and Clinical Operations Leaders
When evaluating equipment, weigh not only measurement performance but also the operational burden of deployment, training, cleaning and disinfection requirements, and integration with existing documentation systems. In regulated environments, prioritize vendors that can provide clear evidence of standards alignment and post-market support, since these factors affect both accreditation risk and long-term operating cost. For decentralized or home-based testing, require a realistic plan for data handling, result interpretation, and patient support, because the device alone does not determine outcomes in those settings.
Conclusion
The pulmonary function testing systems market is moving from steady expansion to a more structurally complex phase in which value is shaped by workflow integration, compliance readiness, and deployment flexibility. The growth trajectory remains attractive, but the commercial winners will be those who convert that growth into differentiated solutions for specific care settings rather than competing solely on device specifications. As regulatory expectations firm up, decentralized testing broadens, and software becomes a central part of the value proposition, the market will increasingly reward clarity of strategy and operational execution.
Detailed segmentation data, regional and application-level breakdowns, and customized scenario analysis can further sharpen these decisions. For leaders who need a more granular view of where demand is concentrating and how procurement dynamics are evolving, the full research report provides deeper datasets and focused recommendations tailored to specific strategic questions.
For detailed analysis of this topic, please visit the official page: Pulmonary Function Testing Systems Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


