



Thioctic Acid (ALA) Market at $985M: 5.92% CAGR Trajectory & 3 Strategic Shifts Reshaping the Industry

Navigating the Thioctic Acid (Alpha Lipoic Acid) Market: Strategic Trends and Commercial Opportunities
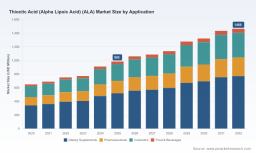
The Thioctic Acid (Alpha Lipoic Acid) market has matured beyond its origins as a niche chemical intermediate into a strategic ingredient spanning pharmaceuticals, nutraceuticals, and personal care. Global revenue climbed from $650.0 million in 2020 to an estimated $985.0 million in 2025, with a projected compound annual growth rate of 5.92 percent through 2032. This trajectory reflects broader shifts in preventive health, oxidative-stress management, and the convergence of clinical-grade efficacy with consumer-facing formulations. Yet the expansion path is uneven. Structural cost pressures, regulatory scrutiny, and geographic supply concentration are reshaping how manufacturers, investors, and procurement teams approach the category. Understanding where value accrues—and where it erodes—requires a clear read on technological differentiation, policy signals, and the evolving purchasing behavior of end markets.
Market Landscape and Structural Challenges
The baseline trajectory of the ALA market is anchored by steady volume growth and expanding application breadth. Revenue expanded consistently from 2020 through 2025, with the most pronounced inflection occurring between 2023 and 2024 as formulation adoption accelerated across multiple end-use channels. Forward projections indicate sustained growth through the early 2030s, positioning the category as a durable component of the broader bioactives ecosystem. This expansion is not uniform across applications or regions. Dietary supplements and cosmetics together represent the dominant commercial weight, while pharmaceutical-grade formulations maintain a meaningful but slower-moving share tied to clinical validation cycles and reimbursement pathways. Asia Pacific and North America anchor demand volume, with Europe contributing steady consumption supported by established supplement infrastructure. By molecular form, the market is increasingly bifurcated between racemic blends and enantiomer-pure variants, a distinction that increasingly influences pricing, formulation flexibility, and downstream marketing claims.
Concentration and Fragmentation Dynamics
Market structure remains moderately consolidated, with the largest players commanding a combined share in the mid-thirties and the top five entities approaching nearly half of total commercial activity. This concentration coexists with a long tail of regional suppliers, contract formulators, and research-grade distributors. The resulting landscape presents both stability and vulnerability. Consolidation has improved quality consistency and supply visibility for large-scale buyers, yet it also concentrates execution risk around a limited number of manufacturing nodes. Meanwhile, smaller regional players compete on agility, local regulatory navigation, and specialized enantiomer or derivative offerings, creating a segmented environment where competitive advantage depends on more than scale alone.
PW Consulting
Key Challenges at the Current Inflection Point
Several structural frictions are redefining how stakeholders position themselves in the ALA market. First, raw material volatility has become a persistent margin test. Octanoic acid prices swung between 15 and 25 percent during 2024 and 2025 as El Niño-related disruptions affected palm kernel and coconut oil availability. Because octanoic acid is integral to ALA conversion pathways, this input movement directly inflated production costs and compressed the economics of supplement formulators and private-label buyers who operate on thin spreads. Second, regulatory uncertainty is reshaping demand visibility, particularly in Europe, where ongoing scrutiny under Article 8 proceedings may reduce the addressable supplement market meaningfully. The prospect of tighter claim structures or usage limitations has prompted formulation teams to reevaluate ingredient positioning, shelf-life planning, and geographic allocation of inventory. Third, geographic concentration in sourcing remains a latent operational risk. With a concentrated share of global capacity centered in China, supply chain shocks such as shipping route disruptions highlighted the fragility of relying on a narrow set of origin points. Buyers with lean inventories and just-in-time procurement models faced disproportionate exposure, reinforcing the need for diversified origin strategies and buffer planning.
Core Demand Drivers Shaping the Category
The growth of ALA is not driven by a single tailwind but by intersecting forces across technology, regulation, consumer behavior, and cost architecture. Each driver alters where investment should flow and how product portfolios should be constructed.
Technological Differentiation and Form Advances
Innovation in molecular form and stabilization has emerged as a decisive commercial lever. The shift from racemic blends toward stabilized enantiomer forms reflects a broader consumer and formulation preference for bioavailability and consistent performance. Suppliers offering stabilized R-lipoic acid or solvent-free grades have carved defensible positions by aligning molecular purity with formulation stability, lower excipient load, and clearer claim narratives. These advances do not merely improve technical specs; they influence downstream pricing power and the ability to serve premium supplement and cosmeceutical applications where performance consistency is a purchase driver. In practical terms, form innovation has become a gatekeeper to higher-margin segments and a differentiator against commoditized bulk supply.
Worldwide Thiochemicals Market
Policy, Regulatory, and Reimbursement Signals
Regulatory dynamics are acting as both a filter and a directional signal. In the United States, compounded ALA remains accessible for patient use through established bulk drug substance pathways, preserving a channel for clinical and customized applications. In parallel, marketing environments for combination products face tighter constraint. Recent restrictions on DHA/EPA nutrient claims have limited how omega-3-enriched ALA supplements can be promoted, compelling brands to reposition messaging around antioxidant support, nerve health, and metabolic wellness rather than synergistic fatty-acid narratives. European scrutiny adds an additional layer of uncertainty. Potential adjustments to supplement usage could reshape regional demand, pushing manufacturers to diversify geographic exposure and to validate formulations against evolving compliance expectations before committing to large-scale inventory. These policy developments reward companies that invest early in compliance readiness, claim substantiation, and flexible formulation architectures.
Consumer Behavior and Application Expansion
Demand-side behavior continues to tilt toward preventive wellness and multi-benefit formulations. ALA benefits from its dual visibility as an antioxidant agent and a metabolic support ingredient, allowing it to enter product architectures spanning nerve comfort, energy metabolism, and skin-care antioxidant coverage. In supplements, the ingredient is increasingly paired with complementary actives in comprehensive wellness regimens. In cosmetics, the emphasis on oxidative stress mitigation and skin resilience has opened room for ALA in premium topical formats. Importantly, consumer purchasing is increasingly influenced by transparency around origin, purity, and molecular form. Buyers are less responsive to generic ingredient listings and more attentive to differentiators such as stabilized enantiomers, solvent-free processing, and documented quality systems. This behavioral shift raises the bar for supplier positioning and rewards brands that can translate technical superiority into clear consumer and practitioner messaging.
Supply Chain Architecture and Cost Structure Evolution
Cost structure evolution is reshaping sourcing strategies. The octanoic acid price volatility of 2024-2025 underscored how input concentration can cascade into margin pressure across conversion and formulation. Beyond raw material swings, logistics risk has become a strategic consideration. The Red Sea shipping disruptions demonstrated how quickly geographic concentration in manufacturing capacity can translate into delivery uncertainty, particularly for buyers dependent on a limited set of origin countries. In response, supply chain design is moving toward multi-origin sourcing, regional safety stock, and longer-term supplier agreements that stabilize pricing while preserving flexibility. For manufacturers, this means that cost leadership is no longer purely a function of scale; it increasingly depends on input hedging, logistics redundancy, and the ability to maintain consistent quality across multiple production sites.
Competitive Positioning and Strategic Moves
The competitive field is defined by companies that have chosen distinct lanes of differentiation: enantiomer purity, solvent-free processing, medical-grade quality systems, and application-specific formulation expertise. These choices shape pricing, customer segments, and resilience to regulatory and cost shocks.
Differentiated Leaders and Value Propositions
Several established players illustrate how strategic focus translates into market positioning. One group of suppliers emphasizes high-purity ALA for cosmeceutical and nutraceutical applications, building brand trust around consistent assay and documented quality for formulators who require reliable input characteristics. Another tier focuses on solvent-free grades for dietary supplements and pharmaceutical use, positioning around cleaner processing profiles and suitability for sensitive formulations. A third orientation centers on bio-enhanced stabilized enantiomer forms, targeting applications where bioavailability and stability are central to the value narrative. Alongside ingredient suppliers, branded supplement manufacturers and formulators convert these inputs into finished products with specific nerve-support and antioxidant messaging. Across these categories, the common thread is that technology and quality claims are no longer optional enhancements; they are the primary mechanisms for distancing from bulk commodity pricing.
Competitive Evolution: Integration, Specialization, and New Entrants
The market is evolving along multiple axes simultaneously. Larger, integrated suppliers are expanding application coverage, attempting to serve pharmaceutical, supplement, and cosmetic channels with consistent quality systems and broader grade portfolios. This integration can strengthen negotiation leverage with downstream buyers and reduce dependency on any single channel. At the same time, specialization continues to thrive. Niche players that concentrate on stabilized enantiomers, research-grade material, or region-specific GMP supply maintain relevance by serving customers who value technical specificity and local compliance familiarity. New entrants typically emerge by targeting underserved formulation needs or by offering differentiated processing attributes that incumbent bulk suppliers do not prioritize. The resulting landscape is neither purely consolidated nor fully fragmented. It is a layered market in which scale, technical specificity, and compliance readiness each create distinct lanes of advantage.
Competitive Implications for Commercial Strategy
For buyers and investors, the practical implication is that supplier selection must account for more than unit cost. Evaluation criteria increasingly include molecular form availability, processing attributes, country-of-origin exposure, and the supplier’s ability to navigate evolving regulatory expectations. For manufacturers, competitive positioning depends on whether they can convert technical differentiation into formulation performance, claim support, and supply reliability. Companies that treat ALA as a commodity input risk margin erosion and exposure to volatility; those that integrate quality narratives, form differentiation, and diversified sourcing into their planning are better positioned to protect pricing and expand premium product lines.
Forward Outlook: Trends Defining the Next Three to Five Years
Looking toward the late 2020s and early 2030s, three trends are likely to shape where value is created and where risk concentrates.
Stabilization and Enantiomer Premiumization
The market is likely to continue shifting toward stabilized and enantiomer-pure forms in higher-value applications. As formulators and brands seek consistent bioavailability and stronger claim narratives, demand for premium grades should outpace growth in bulk racemic supply. The commercial opportunity lies in building product architectures that make molecular differentiation visible to practitioners and consumers, while ensuring that stability claims are substantiated through robust quality documentation. The uncertainty here is regulatory interpretation: if claim environments tighten, the premiumization path depends on the ability to justify performance benefits without overextending marketing language.
L-Alanine Market
Geographic Rebalancing and Supply Resilience
Supply concentration risk will continue to drive rebalancing. Buyers and manufacturers will likely diversify origin points, increase regional inventory buffers, and strengthen contractual safeguards against logistics shocks. This creates opportunities for suppliers in alternative regions to capture share by offering reliable quality, transparent documentation, and flexible commercial terms. The risk is that diversification introduces complexity in quality harmonization and cost management, requiring disciplined vendor qualification and ongoing audit processes. Companies that treat resilience as an investment rather than a reactive measure will be better placed to maintain continuity when disruption recurs.
Regulatory Navigation as a Competitive Advantage
Regulatory developments in key regions will function as both constraint and selection mechanism. In Europe, potential adjustments to supplement usage could compress demand in the near term while rewarding manufacturers with prepared compliance strategies and reformulated product options. In the United States, continued access for compounded use preserves clinical and customized pathways, but marketing constraints on combination products will require sharper positioning. The companies most likely to capture opportunity are those that build regulatory intelligence into product planning, maintain claim substantiation readiness, and keep formulation portfolios flexible enough to adapt to shifting compliance boundaries without sacrificing core consumer benefits.
Strategic Actions for Decision Makers
Different roles within the market face distinct priorities, but a few strategic moves apply broadly and can improve positioning regardless of whether the focus is manufacturing, investment, or procurement.
For Manufacturers and Formulators
- Prioritize form and processing differentiation that translates into measurable formulation advantages, such as stability, lower excipient burden, and cleaner processing profiles, rather than competing primarily on bulk pricing.
- Build multi-origin sourcing and agreed buffer inventory to reduce exposure to raw material swings and logistics disruptions, and structure supplier relationships to provide pricing visibility over longer horizons.
- Align product claims and documentation with evolving regulatory expectations early, especially in regions where scrutiny may reshape addressable demand, so reformulation and repositioning can be managed proactively.
For Investors and Capital Allocators
- Assess exposure to enantiomer purity, solvent-free processing, and application diversification when evaluating companies, because these attributes increasingly determine margin resilience and pricing power.
- Monitor regulatory trajectories in Europe and the United States as signals that can alter demand visibility, and weigh portfolio exposure against potential claim constraints or usage adjustments.
- Seek suppliers and brands with demonstrated quality systems and supply resilience, since geographic concentration and input volatility remain structural risks that can affect continuity and profitability.
For Procurement and Supply Chain Leaders
- Diversify source geography and establish qualification protocols that account for both quality consistency and continuity risk, rather than optimizing solely on spot pricing.
- Negotiate commercial terms that provide clarity on input cost linkage, especially for conversion-dependent materials, to reduce surprise margin compression when commodity prices move.
- Treat ALA sourcing as a multi-dimensional decision that includes molecular form availability, processing attributes, and documentation readiness, so downstream product performance and compliance posture are protected.
The Thioctic Acid (Alpha Lipoic Acid) market is moving from broad expansion toward a more differentiated and compliance-sensitive phase. Growth remains attractive, but the reward is increasingly concentrated in players who can combine technological specificity, supply resilience, and regulatory readiness. A deeper look at segment-level demand shifts, regional dynamics, grade-level pricing behavior, and competitive benchmarking can sharpen planning and reduce exposure to volatility. For stakeholders seeking a more granular view with tailored scenario analysis and actionable recommendations, the complete PW Consulting research report provides the detailed breakdowns and customized guidance needed to convert market intelligence into execution.
For detailed analysis of this topic, please visit the official page: Thioctic Acid (Alpha Lipoic Acid) (ALA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


