



Laminate Flooring Market: How the 6.98% CAGR and Residential Demand Redefine Growth

Navigating the Laminate Flooring Market: Strategic Trends and Commercial Opportunities Through 2032
Market Context: Scale, Growth Trajectory, and Structural Headwinds
The laminate flooring sector has demonstrated resilient expansion over the past half-decade, recovering from a brief contraction in 2024 to reach an estimated USD 1.7 billion in annual revenue by 2025. Over the 2020–2025 historical window, the market expanded at a compound annual rate that reflected both post-pandemic housing activity and a steady shift toward cost-effective, aesthetically versatile flooring alternatives. Looking ahead to the 2026–2032 forecast horizon, the sector is positioned to sustain a robust growth path, with revenues projected to cross the USD 2.6 billion threshold by the end of the period. The annualized growth rate implied by these projections underscores a market that is not merely rebounding but structurally expanding, driven by durable demand signals and incremental product innovation rather than short-lived cyclical spikes.
Despite the favorable top-line trajectory, the industry sits at a inflection point where growth alone no longer guarantees profitability or market share retention. Three structural challenges are reshaping how participants compete and allocate capital. First, raw material volatility—particularly in amino resin inputs—has compressed margins and forced manufacturers to revisit pricing strategies, inventory planning, and formulation alternatives. Second, the regulatory environment has tightened on both sides of the Atlantic, with formaldehyde emission thresholds and performance standards creating a compliance barrier that favors established producers with robust quality systems and penalizes smaller players lacking technical infrastructure. Third, consumer and specifier preferences are shifting faster than traditional product development cycles, placing a premium on waterproof capabilities, realistic wood visuals, and sustainable positioning—attributes that require sustained R&D investment and supply chain coordination.
Cork Flooring Market
Core Drivers Reshaping the Laminate Flooring Landscape
Material Innovation and Performance Upgrades
The most visible driver of market evolution is the transition from traditional laminate as a purely decorative, moisture-sensitive surface to engineered formats that deliver water resistance, enhanced durability, and tighter click mechanisms. Recent product updates emphasizing multi-hour water resistance and spill-defense technologies illustrate how manufacturers are responding to real-life usage scenarios in both homes and light commercial settings. These advances are not cosmetic; they alter the value proposition of laminate relative to rigid core and luxury vinyl alternatives, allowing laminate to retain relevance in moisture-prone spaces such as kitchens, entryways, and some hospitality environments. The integration of advanced locking systems and refined surface treatments also raises installed performance, which matters increasingly to contractors and end-users who weigh total cost of ownership rather than upfront material price alone.
Regulatory Tightening as Both Constraint and Differentiator
Regulatory frameworks governing formaldehyde emissions and product performance have matured from compliance checkboxes into strategic variables. In the United States, emission standards under TSCA Title VI and CARB Phase 2 continue to shape sourcing decisions, while European market access hinges on performance classifications and emission limits that must be demonstrated through consistent testing and documentation. For manufacturers, these requirements raise the cost of entry and reward scale, process control, and transparent supply chains. At the same time, they create a differentiation path for brands that can communicate low-emission credentials and certified performance with credibility. The net effect is a market where regulatory conformance is becoming a competitive asset rather than a simple cost of doing business.
Demand-Side Shifts in Residential and Commercial End Use
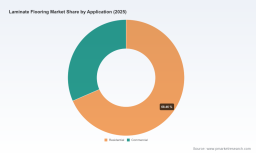
Demand patterns reflect evolving lifestyles and asset management priorities. In residential settings, owners are prioritizing flooring that balances visual warmth with practical resilience—especially in households with children and pets, where spill resistance and easy maintenance carry real purchase weight. In commercial applications, facility managers and designers are seeking products that support durability targets, ease of replacement, and sustainability goals without sacrificing design quality. This dual demand profile encourages product line extensions that serve both segments while preserving distinct branding and performance messaging. Trade show activity and industry trend publications reinforce the direction of travel, with recurring emphasis on natural textures, sustainable design narratives, and installation-friendly systems that reduce labor friction.
Supply Chain and Cost Structure Realignment
The laminate value chain remains sensitive to input costs, particularly resin systems and wood fiberboard substrates sourced from sustainably managed forests. Price fluctuations in amino resin inputs during recent periods have rippled through production economics, prompting producers to diversify suppliers, renegotiate contracts, and in some cases reformulate top-layer compositions where feasible. Alongside input volatility, logistics costs and trade dynamics influence landed pricing and geographic availability. Some producers have repositioned local or regional manufacturing as a hedge against tariff-heavy import exposure, using design-forward, PVC-free programs to capture buyers seeking quality and supply security. This reorientation hints at a broader supply chain realignment in which proximity, compliance assurance, and material transparency are gaining strategic weight alongside unit cost.
Competitive Landscape: Positioning, Differentiation, and Structural Shifts
The competitive set spans large diversified flooring organizations and specialized laminate producers, each pursuing distinct positioning strategies. Several North American-based manufacturers have concentrated on waterproof laminate collections with realistic wood visuals and advanced locking systems, targeting both residential and commercial use cases where moisture performance is a deal driver. Others have built premium lines around integrated technology for durability and low-emission residential options, using certification and performance messaging to justify price premiums and strengthen dealer confidence. In Europe, established panel and flooring groups continue to emphasize high-quality laminate built on wood fibreboard substrates and impregnation papers, aligning product development with on-trend residential and commercial aesthetics. A parallel strand of competition comes from brands advancing sustainable sourcing narratives, including high proportions of sustainably sourced wood and eco-conscious resins, paired with click systems designed to improve installation speed and joint integrity.
Recent activity shows how these strategies are being operationalized. One major European panel and flooring group re-established design-forward, sustainable, PVC-free laminate programs as a high-quality alternative to tariff-heavy imports, signaling a deliberate pivot toward supply resilience and material positioning. Around the same period, another producer showcased new PVC and mineral core flooring technologies alongside laminate offerings at a major trade event, reflecting a broader portfolio approach that treats laminate as part of a wider hard-surface ecosystem rather than a standalone silo. Industry associations and expos continue to function as coordination points for new product catalogs and installation techniques, while trend reports from European producer groups highlight natural textures and sustainable design as recurring themes for upcoming collections. Product-level updates extending water resistance in core collection lines further illustrate the pace of incremental improvement across the market.
PW Consulting Health Care Research Center
Market structure data indicates a moderately fragmented landscape with a consolidated top tier. The combined share of the leading three participants sits below a quarter of total revenue, and the top five collectively account for just over a quarter. This concentration pattern suggests room for both specialized challengers and scaled incumbents, but also implies that share gains are likely to accrue to players that can combine compliance assurance, performance differentiation, and efficient scale rather than to those competing primarily on price. The market is simultaneously consolidating where manufacturing and compliance require capital intensity, while fragmenting in design-led niches where visual differentiation and installation characteristics allow smaller brands to carve out positioning. New entrants tend to succeed when they bring a clear material or performance claim—such as enhanced water resistance, low-emission credentials, or sustainable sourcing—backed by credible documentation and a distribution pathway that reaches specifiers and retailers efficiently.
LVT Flooring Market
Forward Outlook: Three Trends Defining the Next 3–5 Years
Performance-Led Product Convergence
Over the next several years, laminate offerings are likely to converge further toward performance characteristics that were once the domain of rigid core and luxury vinyl products. Water resistance, spill defense, and improved locking systems will become baseline expectations in many residential and light commercial applications, reshaping comparison sets at point of sale. The commercial opportunity lies in packaging these capabilities with credible installation benefits and maintenance narratives that reduce total cost of ownership arguments against competing formats. The risk is a race to the middle if differentiation rests on similar claims without supporting documentation, installation consistency, or durable quality control. Winners will be those who pair performance upgrades with transparent testing, clear warranties, and installer education that converts technical claims into confident purchase decisions.
Sustainability as Specification Currency
Sustainability is transitioning from a marketing accent to a specification factor in both residential and commercial procurement. Sourcing transparency, emission performance, and material choices are increasingly weighed alongside aesthetics and price, particularly in projects with environmental certification targets or corporate sustainability commitments. The commercial opportunity is to build coherent product stories that link sourcing, resin choices, and emission compliance into a verifiable narrative supported by recognized standards and documentation. The uncertainty lies in the pace and harmonization of regulatory expectations across markets, which can shift the relative attractiveness of specific formulations or sourcing models. Participants that maintain flexible input strategies and robust compliance systems will be better positioned to adapt without sacrificing market access.
Regional Rebalancing and Supply Chain Localization
Geographic demand and supply strategies are likely to rebalance as trade dynamics, input cost volatility, and lead-time expectations evolve. Producers with localized manufacturing or diversified sourcing footprints can mitigate exposure to import-related cost shocks and respond more quickly to regional design preferences. The commercial opportunity is to align product portfolios with regional demand signatures—warm natural visuals in some markets, performance-led waterproof lines in others—while maintaining economies of scale in core processes. The risk is over-investment in capacity ahead of demand or under-investment in compliance and quality infrastructure that erodes brand trust. Strategic capacity decisions should be tied to verified regional demand signals and a realistic assessment of input cost trajectories, rather than to short-term promotional cycles.
Decision-Maker Playbook: Actions by Stakeholder Type
For Manufacturers and Brand Owners
- Prioritize performance claims that can be documented and defended, especially water resistance, emission compliance, and installation reliability, because these attributes increasingly determine specification outcomes and reduce returns.
- Diversify resin and substrate sourcing while maintaining formulation integrity, and build scenario plans around input cost volatility so that pricing and margin decisions do not depend on a single supply assumption.
- Align product development with regional demand signatures and installation realities, using design-led and performance-led line extensions where they address real specifier concerns rather than pursuing broad portfolios that dilute focus.
For Investors and Corporate Development Teams
- Evaluate exposure to regulatory and input-cost risk as part of valuation, focusing on producers with credible compliance systems, diversified supply chains, and documented performance advantages that support pricing power.
- Look for consolidation opportunities where scale improves margin stability and market access, but distinguish true operational value from purely financial engineering by examining quality systems, distribution strength, and brand credibility.
- Consider the pace of format convergence carefully, since laminate’s relative attractiveness will depend on its ability to hold performance and aesthetic ground against competing rigid core and vinyl solutions in key demand segments.
For Procurement, Distribution, and Channel Partners
- Assess supplier health and compliance documentation alongside unit pricing, since emission standards and performance consistency affect downstream risk, customer satisfaction, and rework costs over the lifecycle of a project.
- Match portfolio breadth to channel demand, emphasizing product lines with clear installation and maintenance benefits in segments where labor time, durability, and maintenance are decisive for repeat business.
- Track regional trend signals and trade activity to anticipate demand shifts, using design and performance cues to inform range planning and inventory commitments without overcommitting to short-lived style cycles.
Closing Perspective
The laminate flooring market is moving from a phase defined by price competition and basic decorative utility toward one where performance, compliance, and sustainability credentials determine competitive advantage. The mid-term growth path remains attractive, but value capture will favor organizations that convert technical improvements into credible customer benefits, manage input and regulatory risk with discipline, and align portfolios with real regional demand. For leaders seeking to shape strategy rather than react to it, detailed segmentation data, company-level benchmarking, and scenario analysis can sharpen resource allocation and timing decisions. A comprehensive research report offering granular segment splits, competitive profiles, and forward scenarios is available for teams that need to translate these market-level insights into actionable plans with greater precision.
For detailed analysis of this topic, please visit the official page: Laminate Flooring Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


