



Paracetamol Market: Why the 4.5% CAGR Trajectory Changes Everything by 2032

Paracetamol Market: Strategic Trends and Commercial Opportunities Through 2032
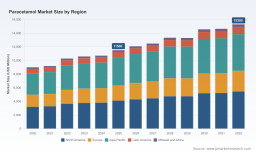
The global paracetamol market has reached a significant inflection point, with total revenues climbing to approximately USD 11,500 million in 2025 and a projected trajectory toward USD 15,300 million by 2032. This expansion reflects a compound annual growth rate of 4.5 percent across the 2026 to 2032 forecast window, building on a period of steady recovery and structural reshaping from 2020 through 2025. The market's resilience stems from paracetamol's entrenched position as a first-line analgesic and antipyretic, yet the operating environment is no longer defined by stable demand and predictable margins. Instead, manufacturers, distributors, and investors are navigating a landscape shaped by raw material volatility, evolving regulatory expectations, and shifting consumer preferences that favor differentiated delivery formats. Understanding where value is being created—and where it is being eroded—requires looking beyond headline figures to the underlying dynamics that will dictate competitive outcomes over the next several years.
Market Snapshot and Emerging Challenges
The paracetamol sector has grown from a baseline of roughly USD 9,000 million in 2020 to its current scale, with the pace of expansion accelerating modestly as healthcare systems stabilized and over-the-counter self-medication regained momentum following pandemic-era disruptions. Growth has been broad-based, but regional performance tells a more nuanced story. Asia Pacific and North America together account for the largest revenue shares, reflecting both high population density in the former and strong branded distribution networks in the latter. Europe remains a mature but stable contributor, while Latin America and the Middle East and Africa represent smaller but strategically important markets where access-to-medicine initiatives and pricing reforms continue to shape volume trajectories.
Industry concentration offers another lens on market structure. The top three players command roughly 35 percent of global revenue, while the top five extend that share to approximately 45 percent. Such concentration indicates that scale, supply chain leverage, and regulatory expertise remain meaningful barriers to entry, yet it also signals room for specialization. Smaller and mid-tier manufacturers can compete effectively by focusing on niche formulations, regional regulatory approvals, or value-added delivery systems rather than attempting to match incumbents across every segment.
Several challenges are reshaping how companies approach the market. First, the supply chain for para-aminophenol, the primary precursor for paracetamol synthesis, experienced notable disruption in 2025 when export controls imposed by China constrained global availability. This episode exposed the sector's reliance on a concentrated precursor base and highlighted the vulnerability of cost structures that lack diversification or contractual flexibility. Second, pricing pressures intensified in key markets. In India, the National Pharmaceutical Pricing Authority documented sharp increases in paracetamol prices during 2025, driven by raw material cost escalation and the complex interplay of government production-linked incentive schemes that altered competitive dynamics among domestic manufacturers. Third, the regulatory environment is becoming more demanding. Amendments to US FDA monographs expected in 2026 are projected to raise labeling compliance costs, adding a new layer of expense for both branded and generic producers operating in or exporting to the United States.
For executives, these challenges translate into three immediate priorities: securing more resilient raw material sourcing, preparing for incremental compliance costs that may compress margins on low-differentiation products, and evaluating whether existing portfolio mixes align with markets where pricing power can be defended.
Key Drivers Shaping Market Trajectory
Technological and Formulation Innovation
Innovation in paracetamol has shifted from the molecule itself to the way it is delivered, absorbed, and experienced by patients. Recent developments underscore this focus. In early 2025, Haleon completed a bioequivalence study of an orodispersible paracetamol tablet at a 500 mg dose in healthy adults under fasting conditions. By mid-2025, ClinicalTrials.gov recorded the completion of a Phase 1 bioequivalence study for similar orodispersible tablets. These activities point to a broader industry effort to improve convenience, adherence, and perceived efficacy, particularly in segments where swallowing conventional tablets is a barrier for certain patient populations.
Orodispersible formats are not merely a technical exercise; they represent a pathway to premium positioning in over-the-counter channels where consumer perception and ease of use influence purchase decisions. Companies that can demonstrate consistent bioavailability, stable manufacturing processes, and acceptable taste profiles are better placed to capture share in categories where differentiation has historically been thin. The commercial implication is clear: formulation capability is becoming a competitive lever, and manufacturers that invest in delivery-system expertise can reduce reliance on commodity pricing dynamics.
Policy and Regulatory Environment
Regulatory developments are reshaping both market access and cost structures. In India, the National Pharmaceutical Pricing Authority's 2025 findings on paracetamol price increases illustrate how domestic policy can amplify or mitigate the effects of raw material inflation. Production-linked incentive schemes, while intended to strengthen domestic manufacturing capacity, have interacted with cost escalation in ways that produced noticeable price movements and altered competitive positioning among local suppliers.
In the United States, anticipated FDA monograph amendments for 2026 are expected to increase labeling costs for paracetamol products. While these changes do not alter the drug's clinical role, they do affect the economics of product line management. Companies with complex SKU portfolios, multiple packaging configurations, or extensive distribution footprints will need to model the cumulative impact of compliance costs and decide where simplification or consolidation can preserve profitability. Parallel attention to pharmacovigilance expectations remains relevant, as regulatory bodies continue to evaluate the broader safety narrative around widely used analgesics, even when clinical evidence remains reassuring.
Demand-Side Shifts and Consumer Behavior
Consumer behavior continues to evolve in ways that influence both volume and product mix. A growing preference for self-care and accessible over-the-counter options has reinforced demand for paracetamol across multiple indications, including headache, fever, cold and cough, and muscle cramps. The application landscape is broad, and the relative weight of each use case varies by region and demographic profile. What matters strategically is that demand is not monolithic; it is segmented by age, presentation, and purchase context, which creates opportunities for targeted product design and channel strategy.
Recent safety research has also contributed to a more stable demand environment by addressing long-standing public questions. A February 2026 meta-analysis published by UpToDate found no association between prenatal paracetamol use and autism or ADHD risk in low-bias studies with long follow-up. In January 2026, MedicalXpress released findings supporting the safety of paracetamol and ibuprofen in infants under one year of age, with no link to eczema or other measured risks. In April 2026, JAMA Network published a trial comparing acetaminophen versus opioid addition to ibuprofen for pediatric pain relief, contributing to ongoing discussions about optimal analgesia strategies. Collectively, these developments help sustain confidence in paracetamol's role in both adult and pediatric settings, reducing the likelihood that safety concerns will materially disrupt demand in mainstream markets.
Supply Chain and Cost Structure Dynamics
The cost side of the equation has become a strategic focal point. China's dominant position in paracetamol precursor supply has been a defining feature of the market. A May 2026 US State Department report highlighted China's roughly 70 percent share of para-aminophenol supply, with direct US imports at only 17 percent. That concentration became more consequential in 2026, when an Iran-related conflict triggered vessel shortages that restricted API movement from China and drove paracetamol raw material prices up by more than 26 percent in India.
These events are not isolated; they reveal structural dependencies that companies must manage proactively. Firms that depend on single-source precursor procurement or that lack visibility into tiered supplier networks are exposed to both price shocks and availability risk. Conversely, organizations that have built multi-source strategies, maintained strategic inventory buffers for critical inputs, or invested in forward contracting are better positioned to stabilize costs and protect supply continuity. The broader lesson is that supply chain design is now a competitive differentiator in a market where margins on undifferentiated products are already under pressure.
Competitive Landscape and Leading Strategies
The paracetamol market features a mix of large multinationals, established Indian API and formulation producers, and regional specialists. This blend creates a competitive environment in which scale, geographic reach, and formulation capability interact in different ways across segments.
Among the companies shaping the market, several Indian manufacturers stand out for their high-volume production of paracetamol API and finished dosage forms. Granules India Limited, based in Hyderabad, is a major producer of paracetamol API and tablets with extensive global supply relationships. IOL Chemicals and Pharmaceuticals Limited, headquartered in Ludhiana, is an active manufacturer and exporter of paracetamol API and formulations. Farmson Pharmaceutical Gujarat Private Limited, operating from Gujarat, produces paracetamol API and tablets under WHO-GMP and other recognized standards. These firms illustrate the strategic importance of cost-efficient, compliant manufacturing in a market where precursor dynamics and pricing regulation can move quickly.
Larger integrated players bring a different set of advantages. Sun Pharmaceutical Industries Ltd, based in Mumbai, operates as a global pharmaceutical company with paracetamol tablet and API production capabilities. Cipla Ltd, also headquartered in Mumbai, manufactures paracetamol tablets and formulations across multiple markets. Their scale, regulatory infrastructure, and distribution reach allow them to compete across both generic and branded contexts, though they must still navigate the same raw material and compliance pressures affecting the broader industry.
On the branded side, GSK, headquartered in London, remains a global producer of paracetamol-branded products including Panadol and combination formulations. Sanofi, based in Paris, is an active supplier of paracetamol products and formulations worldwide. Mallinckrodt Pharmaceuticals, located in St. Louis, is a US-based producer of paracetamol API and finished dosage forms. On the branded side, GSK, headquartered in London, remains a global producer of paracetamol-branded products including Panadol and combination formulations. Sanofi, based in Paris, is an active supplier of paracetamol products and formulations worldwide. Mallinckrodt Pharmaceuticals, located in St. Louis, is a US-based producer of paracetamol API and finished dosage forms. These organizations typically compete on brand equity, patient-facing positioning, and broader portfolio integration rather than price alone.
Acetaminophen Market
The strategic positioning of these players diverges in ways that matter for competitive planning. Indian API and formulation manufacturers often emphasize volume, cost discipline, and export capacity, leveraging regulatory certifications and production efficiency to serve both domestic and international markets. Multinationals and branded players more frequently invest in patient convenience, formulation variety, and trust-based consumer relationships, which can support pricing resilience in categories where differentiation is credible. Companies that combine strong manufacturing fundamentals with formulation-driven differentiation are increasingly well placed to navigate both commodity pressure and premium opportunity.
PW Consulting
Market structure is evolving through selective consolidation and parallel fragmentation. On one hand, larger players continue to seek efficiencies in supply, regulatory management, and distribution, which can lead to tighter integration across API, formulation, and packaging. On the other hand, specialized niche participants are carving out positions around delivery formats, regional approvals, and patient-centric packaging that do not require matching the full scale of the largest competitors. New entrants face meaningful hurdles given existing concentration and regulatory complexity, but targeted entry remains possible where formulation novelty, local market knowledge, or channel access provides a defensible starting point.
Recent industry events reinforce the strategic significance of these divergent paths. Safety and clinical developments have reinforced demand confidence in established use cases, while formulation work on orodispersible tablets indicates where incremental differentiation is being pursued. At the same time, raw material disruptions and pricing actions in key markets show that even well-positioned companies must manage upstream dependencies and regulatory cost exposure with discipline.
Antipyretic and Analgesic Market
Forward Outlook: Trends and Commercial Implications
Trend One: Greater Emphasis on Delivery Format Differentiation
Over the next three to five years, formulation differentiation is likely to become a more visible feature of competition, especially in over-the-counter channels where consumer choice is shaped by convenience, taste, and perceived ease of use. Orodispersible and other patient-friendly formats are attracting clinical and commercial attention, and companies that can bring these formats to market with consistent quality and credible bioequivalence data may gain incremental pricing latitude. The commercial opportunity lies in aligning format innovation with target populations and channel strategies, rather than treating new delivery systems as a generic upgrade. A related risk is that differentiation only pays off when it is supported by manufacturing reliability, taste acceptability, and clear consumer communication; otherwise, premium positioning is difficult to sustain.
Trend Two: Supply Chain Reconfiguration and Sourcing Diversification
The concentration of para-aminophenol supply and the price shocks associated with geopolitical and logistical disruptions point toward a longer-term shift in sourcing strategies. Companies are likely to pursue a combination of multi-source procurement, closer supplier relationships, and regional capacity planning to reduce exposure to single-point failures. For manufacturers with significant exposure to precursor imports, this may mean renegotiating supply terms, qualifying alternative sources, or adjusting production planning to absorb short-term volatility more efficiently. The opportunity here is to convert supply chain resilience into a more stable cost base and more dependable fulfillment, both of which support customer trust and margin protection. The risk is that diversification takes time and capital, and that transitional periods can create their own inefficiencies if supplier qualification and quality assurance are not managed carefully.
Trend Three: Regulatory Cost Management as a Core Competency
As labeling and monograph requirements evolve, particularly in major markets such as the United States, regulatory cost management will become a more central element of portfolio strategy. Companies that proactively rationalize SKU complexity, streamline packaging variations, and align compliance processes with manufacturing workflows are more likely to preserve margins than those that treat regulatory changes as an external cost to be absorbed passively. This trend also intersects with market access and pricing policy in regions such as India, where domestic regulation can interact with raw material economics in ways that drive price outcomes. Businesses that monitor these dynamics closely and incorporate them into planning will be better positioned to anticipate margin shifts and adjust product strategies before pressure becomes acute.
Implications for Decision Makers
For manufacturers, the immediate priority is to strengthen upstream resilience while identifying where formulation or delivery improvements can support differentiation. This means reviewing precursor sourcing strategies, testing alternative supply paths, and assessing whether current portfolio complexity is justified by the margin it generates. Where product lines are commoditized, simplification can reduce compliance burden and improve operating efficiency. Where there is credible potential for a differentiated format, targeted development and evidence generation can create a more defensible position in specific consumer segments.
For investors, the market rewards companies that combine cost discipline with credible differentiation and that demonstrate visibility into supply risk. The most attractive profiles are likely those with diversified sourcing, manageable regulatory exposure, and a clear strategy for where premium positioning is possible. It is equally important to distinguish between growth that comes from volume recovery and growth that is supported by product or process advantages, because the durability of each differs. Raw material volatility and regulatory cost changes should be treated as structural considerations rather than temporary noise, and valuation assumptions should reflect the sensitivity of margins to those factors.
For procurement and supply chain leaders, the priority is to reduce single-point dependencies and increase transparency across tiered suppliers. This includes mapping exposure to precursor concentration, evaluating contractual protections, and planning for periods of elevated cost or constrained availability. Building scenarios that account for geopolitical disruption, vessel availability, and regional pricing actions can improve responsiveness and reduce the likelihood of reactive purchasing at unfavorable terms. Procurement strategy in this market is not only about price; it is about continuity, quality assurance, and the ability to support manufacturing stability when upstream conditions shift.
Bringing the Analysis Together
The paracetamol market is moving through a phase in which growth is real but not uniform, and where competitive advantage will increasingly depend on how well companies manage supply exposure, regulatory cost pressure, and the opportunity to differentiate through formulation and patient-facing value. Demand fundamentals remain strong across core indications, and recent clinical and safety developments have helped sustain confidence in the molecule's role. At the same time, precursor concentration, pricing dynamics in key markets, and evolving compliance expectations mean that the path to profitable growth is narrower than it may appear from headline size alone.
Companies and investors that gain the deepest visibility into these interacting forces will be best positioned to act early—whether that means restructuring sourcing, refining portfolio complexity, investing in format differentiation, or reassessing where pricing power can be defended. The strategic window is open now, before further regulatory changes, supply disruptions, or competitive moves reshape the terms of participation.
For decision makers seeking detailed segmentation data, company-level benchmarks, and scenario-based guidance tailored to specific geographies and product lines, the full PW Consulting research report provides a more granular view of the market and its strategic levers. The broader analysis presented here is intended to frame the most important choices; the complete study is designed to support the next step in planning with deeper segmentation, competitive mapping, and forward-looking scenarios.
For detailed analysis of this topic, please visit the official page: Paracetamol Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


