



Stationery Market Outlook: How Asia Pacific and Education Demand Drive 4.85% CAGR Growth to 2032

The Stationery Market in 2026: Navigating Growth, Disruption, and Strategic Opportunity
Market Reality Check: Resilient Growth Amid Structural Headwinds
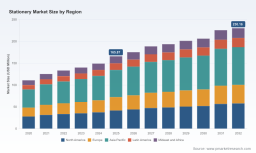
The global stationery market has demonstrated remarkable resilience, expanding from approximately $111 million in 2020 to a projected $166 million by 2025. This trajectory reflects a consistent upward curve, with the sector expected to surpass $230 million by 2032, translating to a compound annual growth rate of 4.85% across the 2025-2032 forecast horizon. Such performance underscores a market that has successfully adapted to shifting consumption patterns, digital disruption, and macroeconomic volatility. Rather than being rendered obsolete by technology, the stationery sector has evolved into a hybrid ecosystem where traditional paper and writing products coexist with specialized, experience-driven offerings. The growth narrative is not merely about volume expansion; it reflects deepening value creation across product tiers, regional dynamics, and end-use applications.
Behind the headline figures lie three structural challenges that are actively reshaping competitive dynamics. First, the tension between digital substitution and tactile utility continues to redefine category relevance. While basic note-taking and administrative documentation have migrated to screens, demand for curated, high-performance, or aesthetically differentiated physical products has intensified. Second, cost pressures and supply chain reconfigurations are forcing manufacturers to recalibrate sourcing strategies, pricing architectures, and inventory positioning. Third, sustainability and circularity expectations are no longer peripheral concerns; they are becoming embedded in procurement criteria, brand positioning, and product design mandates. Companies that treat these forces as isolated issues rather than interconnected strategic vectors risk gradual margin erosion and relevance loss.
Core Growth Drivers Redefining the Stationery Value Chain
Technology innovation in the stationery sector has moved beyond incremental product tweaks into material science, manufacturing efficiency, and intelligent replenishment models. Advances in biodegradable substrates, low-emission inks, and precision molding techniques are enabling brands to reduce environmental footprints while maintaining performance benchmarks. At the same time, digital-to-physical integration is emerging as a differentiator. Brands that link physical products with subscription replenishment, usage tracking, or co-creation platforms are transforming stationery from a transactional commodity into a recurring engagement touchpoint. This shift is particularly visible in segments where consistent quality and supply reliability directly affect user experience, such as educational settings and professional creative workflows.
Regulatory and policy dynamics are simultaneously reshaping input costs and market access. Recent tariff adjustments in major import-dependent markets have elevated effective duty rates, directly affecting manufacturing and retail input costs for office and school supplies. In this environment, companies that previously optimized for low-cost transcontinental sourcing are confronting margin compression unless they rebalance portfolios toward regionalized production, alternative material inputs, or value-added product tiers. The policy signal is clear: cost structures are no longer static, and resilience is increasingly tied to sourcing agility and regulatory foresight rather than sheer volume leverage.
Specialty Paper Market
On the demand side, behavioral shifts in both institutional and professional contexts are rerouting purchasing logic. Educational environments continue to anchor baseline volume, but procurement preferences are increasingly influenced by durability, safety standards, and brand trust. In corporate and residential settings, stationery is being repositioned less as a utilitarian necessity and more as a tool for focus, personalization, and brand expression. The result is uneven category performance: standardized bulk segments face intensifying price competition, while specialized writing instruments, premium paper goods, and creative materials command stronger loyalty and higher perceived value. This bifurcation is a central strategic consideration, because it implies that growth cannot be captured through undifferentiated scale alone.
Supply chain and cost structure evolution completes the driver set. Manufacturing concentration patterns suggest a moderately fragmented landscape, where no small group of players dominates total output. That fragmentation is strategically meaningful: it allows regional specialists and nimble mid-tier manufacturers to compete on responsiveness, customization, and local market intimacy rather than purely on global scale. At the same time, it forces larger multinational operators to differentiate through portfolio breadth, channel strength, and brand architecture. In practice, the most resilient operators are those that combine stable core franchises with agile innovation pipelines and diversified geographic exposure.
Competitive Architecture: Where Leaders Position and How the Map Is Shifting
The global stationery competitive field is defined by a mix of broad-based multinationals, heritage writing brands, and regionally anchored manufacturers. Companies such as BIC, Newell Brands, Faber-Castell, Staedtler, Pilot Corporation, Pentel, Zebra, and Mitsubishi Pencil represent distinct strategic archetypes. Some compete primarily on volume, distribution reach, and school- and office-grade reliability. Others anchor their identity in craftsmanship, premium materials, and professional or creative end-use credibility. This dual structure creates a market where leadership is multidimensional: scale advantage matters, but so does brand trust, product consistency, and the ability to preserve margin in premium subcategories.
Strategic differentiation among leading players increasingly rests on three levers. The first is brand positioning across value tiers. Entrants and incumbents alike must decide whether to defend share in high-frequency, price-sensitive segments or lean into higher-margin creative, executive, and specialty segments where performance and aesthetics justify premium pricing. The second lever is product innovation cadence. In a market where basic functionality is widely available, incremental differentiation in ink flow, grip ergonomics, paper feel, refill systems, and environmental profile can shift purchase preference. The third lever is channel and partnership strategy, especially in education and institutional procurement, where campaign-led engagement, supply reliability, and localized distribution can create durable share advantages.
Recent corporate activity illustrates how leaders are balancing responsibility signaling, demand-side engagement, and product renewal. Sustained sustainability communication and eco-oriented production commitments have become part of the baseline expectation for major manufacturers. Alongside that, school-focused supply campaigns and refreshed product partnerships signal an effort to protect core demand pools while modernizing the assortment. These moves are not isolated public relations actions; they reflect a broader reality that demand retention in education and mass segments requires both reliability and relevance. In parallel, tariff-related cost increases and import volume pressures are pushing companies to scrutinize the economics of cross-border supply, making regional diversification and input substitution increasingly important strategic priorities.
The market structure is evolving along two complementary paths. Consolidation remains plausible in mature categories where scale economics, distribution density, and procurement leverage confer durable advantages. At the same time, fragmentation is gaining ground in creative, premium, and niche segments where smaller players can win through design leadership, specialty materials, and community-driven branding. New entrants are most likely to succeed not by challenging incumbents across the entire aisle, but by capturing underserved demand pockets, leveraging direct-to-consumer engagement, or pairing physical products with digital discovery and replenishment mechanics. For incumbents, the strategic question is whether to absorb these niches through brand architecture and acquisitions or risk gradual erosion in the uppermost value tiers.
Forward Outlook: Three Trends Shaping the Next Three to Five Years
The first defining trend is the recalibration of physical and digital stationery roles. Digital tools will continue to absorb routine documentation and collaboration, but physical products will increasingly occupy categories where tangibility, focus, and premium experience matter. This implies sustained demand for well-designed notebooks, specialized writing instruments, and creative materials, while commoditized bulk items face continued substitution pressure. The commercial opportunity lies in building product lines that explicitly serve this hybrid reality: reliable core SKUs for volume stability, paired with curated premium or specialty lines that protect margin and brand equity.
The second trend is the rise of cost-resilient sourcing and product architecture. As input cost volatility and trade policy uncertainty persist, manufacturers and distributors will increasingly weigh total landed cost, lead-time reliability, and repatriation risk alongside unit price. Companies that can flex between sourcing regions, standardize high-volume components, and reserve customization for higher-value subcategories will be better positioned to maintain service levels without sacrificing profitability. The strategic upside is not simply cost reduction; it is the ability to keep product availability stable during periods when competitors face supply bottlenecks or margin-driven assortment cuts.
Greeting Cards Market
The third trend is the embedding of sustainability into procurement and product design as a baseline expectation rather than a differentiator. Recycled content, lower-impact inks, durable refill systems, and packaging optimization are becoming part of competitive parity. In practice, this creates both a risk and an opportunity: brands that lag on credible environmental improvements may face exclusion from increasingly conscious institutional and consumer purchasing criteria, while those that can substantiate performance with verifiable material and process improvements can use sustainability as a trust multiplier. The critical nuance is that sustainability must be paired with product quality and cost realism; otherwise, it becomes a marginal feature rather than a growth enabler.
These trends carry inherent uncertainty. Macroeconomic swings can compress discretionary and institutional spending simultaneously. Trade and tariff dynamics may continue to alter the cost base for import-dependent product lines. Digital substitution could accelerate in specific functional categories faster than suppliers can reposition assortments. Additionally, overinvestment in premiumization without sufficient demand depth can leave companies exposed to inventory imbalances. The most effective forward strategies will therefore combine scenario planning with portfolio discipline, ensuring that core volume is protected while higher-value experiments are sized appropriately.
Strategic Actions for Decision Makers
For manufacturers, the priority is to build a two-speed portfolio architecture. The base of the business should emphasize supply reliability, cost control, and consistent quality in high-frequency segments, while the upper tier should pursue differentiated materials, ergonomics, and brand storytelling that justify premium positioning. Equally important is sourcing flexibility: maintaining redundancy in critical inputs and evaluating regional production options can reduce exposure to tariff shocks and logistics volatility. Innovation cycles should be shortened for refill systems, functional improvements, and sustainability upgrades, because these are the areas where incremental gains can accumulate into durable advantage.
PW Consulting Health Care Research Center
For investors, the opportunity is less about generic sector growth and more about identifying which business models can capture value across the value-tier split. Companies with strong distribution density, credible premium franchises, and the ability to manage input-cost volatility are better placed to convert market expansion into margin expansion. Watch closely for portfolio balance, resilience in education and institutional channels, and evidence that sustainability commitments are being translated into product and process changes rather than communication alone. Valuation and growth potential will increasingly depend on whether a company can defend volume while expanding share of higher-margin subcategories.
For procurement leaders and corporate buyers, the strategic imperative is to treat stationery purchasing as a service continuity decision rather than a simple cost-minimization exercise. Diversification of suppliers, clarity on total cost including duties and lead times, and alignment with sustainability expectations can reduce operational risk while preserving quality. In institutional and corporate contexts, preference should be given to suppliers that combine dependable replenishment with transparent material and production practices, because consistency and trust often outweigh marginal unit-price differences over multi-year contracts.
The stationery market is not standing still, and neither should the organizations depending on it. To map these dynamics to specific subsegments, regional conditions, and customized strategic options, PW Consulting maintains a dedicated stationery market research practice that develops detailed breakdowns and tailored recommendations.
For detailed analysis of this topic, please visit the official page: Stationery Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


