



Shock Absorber Market 2026: Why the 5% CAGR Trajectory Redefines Revenue Drivers

Strategic Shifts in the Global Shock Absorber Market: Navigating Growth, Innovation, and Consolidation
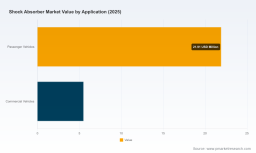
The global shock absorber market is entering a phase of steady expansion, underpinned by consistent demand from automotive production and a gradually modernizing aftermarket. Valued at approximately 21.47 billion USD in 2020, the market has progressed to roughly 27.4 billion USD in 2025, reflecting a compound annual growth rate of about 5.0 percent through the forecast horizon extending to 2032. This trajectory points toward a market size approaching 38.55 billion USD by the end of the forecast period, signaling that suspension damping systems remain a structurally important component category even as vehicle architectures and powertrains evolve.
For executives and investors, the headline growth figure is only the starting point. The more important question is where value is being created, which segments are gaining share, and how manufacturers are responding to cost pressure, regulatory change, and technological differentiation. The market is not simply getting larger; it is becoming more segmented by performance requirements, regional supply dynamics, and the pace of vehicle platform renewal. Companies that treat shock absorbers as commodities risk margin erosion, while those that align product roadmaps with OEM integration needs, aftermarket replacement cycles, and regulatory-driven performance standards are better positioned to capture durable profitability.
The market’s current shape also reflects a moderately concentrated competitive environment. A small group of leading suppliers accounts for a meaningful share of global activity, yet no single player dominates the field outright. That structure matters because it leaves room for differentiated strategies: some firms compete through scale and OEM partnerships, others through specialized high-performance or motorsport-grade products, and still others through regional cost leadership and aftermarket distribution strength. Understanding these strategic choices is essential for anyone evaluating partnership options, acquisition targets, or long-term positioning in the damping systems space.
Core Challenges and Inflection Points
Despite the positive growth outlook, the market is navigating several structural challenges that are reshaping competitive dynamics. The first is the tension between cost control and performance upgrading. Manufacturers face rising input pressure from materials such as steel and hydraulic fluids, and those pressures have been amplified by supply disruptions linked to geopolitical instability. When raw material and fluid costs climb, the margin structure of damping products becomes more sensitive, especially for suppliers serving price-sensitive replacement channels or commercial vehicle segments where total cost of ownership is a major purchase criterion.
A second challenge lies in the regulatory environment. Stricter vehicle safety expectations and emissions-related efficiency targets are changing what automakers require from suspension systems. In the United States, guidelines from the National Highway Traffic Safety Administration influence how shock absorbers are designed and integrated, while new EPA greenhouse gas emissions standards for passenger cars and light trucks through model year 2026 are encouraging efficiency-oriented technologies that can indirectly support advanced damping solutions. At the same time, trade and partnership agreements such as the EU–Japan Economic Partnership are reducing tariffs on automotive components, making it easier for multinational suppliers to coordinate OEM supply across borders but also intensifying competitive exposure.
A third inflection point is the shift in application mix and vehicle architecture. As electric vehicles, heavier passenger vehicles, and more sophisticated commercial platforms gain prominence, damping requirements are changing in ways that affect both product design and replacement behavior. The aftermarket remains a substantial demand base for passenger vehicle components, while commercial vehicles continue to represent a distinct, durability-driven segment. Suppliers must therefore manage two parallel demands: one shaped by OEM specification and platform cadence, the other shaped by replacement cycles, distributor networks, and performance expectations in the service market.
Key Drivers of Market Change
Technology Innovation and Damping Performance
Technological differentiation is becoming one of the clearest ways to defend margins and win OEM programs. Passive dampers still form the backbone of many applications, but the market is increasingly shaped by advances in valve design, adaptive damping, and integrated electronic suspension capabilities. Recent product-level developments illustrate this direction. In early 2026, Monroe Ride Solutions announced a breakthrough in passive damper valve technology intended to improve ride comfort and handling without necessarily requiring more complex electronic architectures. That kind of innovation matters because it can enhance perceived performance while preserving the cost and reliability advantages that make passive systems attractive in high-volume applications.
At the same time, sustainability-oriented engineering is entering the product conversation. In 2025, Showa Corporation announced an eco-friendly hydraulic fluid designed to support carbon neutrality goals. While a single fluid formulation may appear incremental, it reflects a broader shift in which suppliers are expected to address not only ride quality and durability but also environmental footprint and regulatory alignment. As automakers search for efficiency gains and lower-emission components, damping technologies that contribute to vehicle efficiency or reduce the environmental impact of production and servicing can become a meaningful part of the value proposition.
Policy, Safety, and Emissions Pressure
Policy is not only shaping what can be sold; it is influencing how products are engineered and where suppliers choose to locate their partnerships. Regulatory expectations around safety and emissions are encouraging demand for high-performance and adaptive systems that can support better vehicle control, stability, and efficiency. In practical terms, this creates a stronger incentive for OEMs to specify damping solutions that can meet tighter testing and validation requirements, especially in markets where safety standards and emissions rules are advancing rapidly.
Trade policy is adding another layer. By lowering tariff barriers on automotive components, agreements such as the EU–Japan partnership are facilitating cross-border OEM collaboration for suppliers with international manufacturing and engineering footprints. That does not automatically make all suppliers equal; instead, it tends to reward firms that can combine technical capability with a flexible supply footprint, since global programs increasingly require consistent quality, quick responsiveness, and the ability to serve multi-region vehicle programs without excessive cost friction.
Demand-Side Shifts in Passenger and Commercial Vehicles
Consumer and commercial buyer behavior is evolving in ways that affect both product specification and aftermarket demand. Passenger vehicle owners are increasingly aware of ride quality, noise, and handling, and that awareness can translate into stronger demand for replacement components that restore or improve original performance characteristics. At the same time, vehicle parc growth and aging fleets in several regions continue to support a robust replacement market, which gives aftermarket-oriented suppliers a steady source of demand even when new vehicle production cycles fluctuate.
Commercial vehicle demand tells a related but distinct story. Heavy-duty usage patterns, load variability, and total cost of ownership concerns place a premium on durability and consistent damping performance. For operators, the choice of shock absorbers is less about premium perception and more about uptime, service intervals, and protection of other suspension components. That creates a market in which reliability and serviceability can be as important as headline performance metrics, and it rewards suppliers that can demonstrate measurable outcomes in commercial applications.
Supply Chain and Cost Structure Dynamics
Cost structure is reshaping the competitive field. Higher material costs and intermittent supply disruption have pressured producers to improve sourcing resilience, hedge volatility where possible, and focus on design efficiency. In a market where many components are mechanically mature, value creation increasingly comes from manufacturing precision, process control, and the ability to reduce waste or rework without compromising performance. Suppliers that can maintain cost discipline while upgrading product capability typically gain an advantage, especially when they can pass credibility in quality and service life through OEM validation and aftermarket trust.
Regional dynamics also influence cost and availability. Asia Pacific remains a strategically important production and demand base, while North America and Europe continue to represent large, mature demand centers with different channel structures and regulatory expectations. The practical implication is that suppliers often need a multi-regional approach: local or near-local production and distribution can reduce exposure to logistics volatility and improve responsiveness to OEM and service-channel needs, while global scale can support cost efficiency and technology sharing across programs.
PW Consulting
Competitive Landscape and Leading Strategies
The competitive environment is defined by a group of well-established manufacturers with different strategic emphases. KYB Corporation and Showa Corporation bring strong OEM integration capabilities and a deep history in hydraulic damping technology for passenger vehicles, trucks, and commercial applications. ZF Friedrichshafen AG and thyssenkrupp Bilstein GmbH occupy strong positions in high-performance and adaptive suspension solutions, with an emphasis on OEM integration across passenger cars, commercial vehicles, and off-highway use. Tenneco Inc., through its Monroe brand and DRiV ride control products, maintains a notable presence in both replacement and OEM-facing ride control systems for light vehicles and commercial trucks. KONI B.V. is associated with premium damping systems across automotive, motorsport, and commercial applications, while Gabriel and Tokico maintain strong aftermarket and OEM supply traditions in their respective domains.
A second tier of players adds regional specificity and niche capability. Mando Corporation is notable for its focus on AI-enabled and EV-specific adaptive shock absorbers and suspension systems, reflecting a forward-looking angle on electrification and smart suspension. Hitachi Astemo and Mubea contribute high-performance damping and industrial-adjacent quality emphasis, Arnott Inc. extends the field into air suspension and shock absorber products for light and commercial applications, and Loosoo underscores the importance of Asian market supply chains with an OEM and aftermarket focus.
Differentiation Strategies Among Leaders
The leading firms are not all competing for the same prize. Some pursue scale and broad OEM coverage, relying on engineering breadth, global production capacity, and the ability to meet multiple vehicle platforms with consistent quality. Others lean into performance credibility and brand positioning, particularly where motorsport heritage, handling reputation, or premium aftermarket perception can support pricing power. A third group emphasizes application specialization, designing products around commercial durability, off-highway duty cycles, or the particular needs of electrified vehicle platforms.
This divergence creates a market in which “winning” depends heavily on the target segment. In OEM programs, the decisive factors are often validation performance, integration compatibility, delivery reliability, and cost competitiveness across the program lifecycle. In the aftermarket, brand recognition, distribution reach, packaging clarity, and perceived restoration of original ride quality can be equally important. In commercial applications, the emphasis shifts again toward service life, load handling, and fleet economics. Suppliers that understand which game they are playing are more likely to build defensible positions than those that attempt to compete on all fronts simultaneously.
Market Evolution: Consolidation, Fragmentation, and New Entrants
The structure of the market appears likely to continue evolving along several paths. Consolidation may proceed where scale economies, global program coverage, and engineering investment requirements favor larger players, particularly in OEM-facing segments. At the same time, fragmentation can persist in performance aftermarket, regional replacement channels, and specialized applications where local brand strength, service relationships, and product specialization matter more than global scale. New entrants and technology-focused suppliers may find openings in areas such as adaptive damping, electronic suspension integration, and EV-specific component design, where product complexity and software-adjacent capability raise barriers but also create differentiation opportunities.
For decision-makers observing this landscape, the key is to avoid treating the field as either fully consolidated or fully fragmented. It is better understood as layered: concentrated at the top in terms of global reach and program presence, yet still diverse in product types, application focus, and channel strategy. That layered structure means M&A, partnership, and licensing dynamics can be as important as organic product competition, especially when suppliers look to expand into adaptive systems, air suspension, or regional production footprints.
Future Trends and Commercial Opportunities
Toward Smarter and More Efficient Damping Systems
Over the next three to five years, one clear trend is the continued movement toward damping systems that are more responsive, more efficient, and better integrated with vehicle electronics. Even where fully active suspension remains a premium or niche proposition, the broader direction favors components that can support improved ride control, safety-related handling performance, and efficiency goals. Suppliers that can offer valve technology, control compatibility, and packaging flexibility will be well placed to participate in this shift. Commercial opportunity lies not only in high-end applications, but also in making advanced performance accessible in high-volume platforms where cost constraints remain tight.
Electrification and Changing Vehicle Architecture
Electrification is reshaping platform design, vehicle weight distribution, and NVH expectations, all of which influence damping requirements. Electric vehicles can change ride behavior and suspension loading patterns, while the need to manage efficiency and durability remains central. This creates demand for suspension solutions tailored to EV platforms, including adaptive and AI-enabled concepts that can help optimize comfort and control without compromising efficiency targets. For manufacturers, the opportunity is to align product development with the needs of next-generation vehicle architectures before platform decisions become locked in. For investors, the relevant question is which suppliers are building credible EV-related damping capabilities rather than simply extending traditional product lines.
Aftermarket Renewal, Regional Growth, and Supply Resilience
A third trend is the ongoing importance of the replacement market and regional demand diversification. Even as new vehicle production cycles vary, there is a durable base of demand from aging passenger fleets and commercial vehicles in service. Growth in specific regions can create localized opportunities for suppliers that invest in distribution strength, regional manufacturing, or tailored product assortments. At the same time, the market’s exposure to raw material volatility and logistics disruption encourages suppliers to build more resilient sourcing and production arrangements. Companies that can combine regional proximity with consistent quality and competitive cost structures are more likely to protect margins through cycles of input volatility.
These trends do not eliminate uncertainty. Demand can shift with vehicle sales cycles, regulatory timelines can change, and technology roadmaps may be reweighted as automakers balance cost, performance, and electrification priorities. The commercial opportunity is real, but it is not uniformly distributed: it tends to accrue to firms that can move quickly on product adaptation, maintain strong OEM or channel relationships, and manage cost and supply risk without sacrificing performance credibility.
Actionable Implications for Decision-Makers
For manufacturers, the central priority is to match product strategy with the segment economics in which they compete. That may mean investing in valve technology and passive damping refinements for high-volume programs, building adaptive or EV-specific capability where platform trends point that way, or strengthening aftermarket brand and distribution where replacement demand is the main growth engine. It also means treating cost resilience as a strategic capability, not just a procurement task, since material volatility and supply disruption can quickly erode the economics of otherwise strong product lines.
For investors, the useful question is less about whether the market is growing than about which business models are likely to convert growth into margin and share. Attention should be directed toward suppliers with clear differentiation, credible OEM relationships, and evidence of progress in higher-value damping solutions or regional expansion strategies. Equally important is scrutiny of exposure to input cost volatility, regulatory risk, and dependence on specific vehicle production cycles. In a moderately concentrated market, valuation logic should account for both scale advantages and the durability of competitive differentiation.
For procurement and sourcing leaders, the immediate focus should be on balancing performance requirements with supply security and total cost. That includes evaluating suppliers not only on unit price, but also on engineering support, program flexibility, quality consistency, and the ability to accommodate changing regulatory and safety expectations. In environments where tariff reductions and cross-border OEM collaboration are expanding, procurement decisions can also benefit from mapping supplier footprints and partnership options across regions, especially where multi-market vehicle programs are involved.
Industrial Hydraulic Shock Absorber Market
The broader takeaway is that the shock absorber market is large enough to support multiple successful strategies, but selective enough that positioning matters. The firms gaining advantage are those that combine technical relevance with disciplined execution, align product roadmaps with vehicle and regulatory trends, and manage the cost and supply dynamics that increasingly shape outcomes. Detailed segment-level data, company-level benchmarks, and regional scenario analysis can sharpen these decisions further, especially for teams planning investments, procurement strategies, or long-range product development in the damping systems space.
Automotive Stabilizer Bar Market
For detailed analysis of this topic, please visit the official page: Shock Absorber Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


