



Irrigation Controllers Market: Why 8.82% CAGR & Sensor Shifts Redefine Growth

Strategic Outlook: Navigating Growth and Transformation in the Irrigation Controllers Market
Market Trajectory and Core Challenges
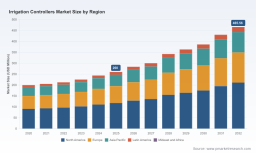
The global irrigation controllers market is entering a period of sustained expansion, driven by the intersection of resource scarcity, technological maturity, and regulatory alignment. Measured in USD millions, the market has grown from approximately 200 million in 2020 to 260 million in 2025, reflecting a compound annual growth rate of 8.82 percent across the historical and forecast window extending to 2032. By the end of the outlook period, market revenue is projected to reach 465.56 million, signaling a structural acceleration rather than a cyclical upturn. This trajectory is underpinned by consistent year-over-year gains, with growth steepening notably in the latter half of the forecast as smart controller adoption moves from early-adopter segments into mainstream commercial and agricultural deployments.
Despite the favorable macro outlook, the industry faces several inflection points that will shape competitive outcomes over the next five years. First, regulatory fragmentation is intensifying. Water efficiency mandates, certification requirements, and rebate architectures vary widely across jurisdictions, creating compliance complexity for manufacturers seeking scale. Second, material cost volatility and trade policy shifts are compressing margins in the short term while forcing supply chain reconfiguration. Third, the definition of "connected" is evolving rapidly. Early smart controllers relied on basic scheduling and remote access; the next generation integrates real-time sensor feedback, predictive weather modeling, and interoperability with broader water management ecosystems. Companies that treat connectivity as a feature rather than a platform risk losing relevance as procurement standards rise.
Key Drivers Reshaping the Market
Technology Innovation and the Shift to Adaptive Control
The transition from timer-based and fixed-schedule systems to weather-based and sensor-driven controllers represents the most consequential technical shift in the category. Weather-based controllers currently account for the largest share of product-type revenue, reflecting their broad applicability across residential, commercial, and agricultural settings. Sensor-based systems, however, are gaining traction in applications where precision and automation deliver measurable operational savings. The value proposition has moved beyond water conservation alone. Advanced controllers now enable labor reduction, pressure management, leak detection, and integration with centralized facility or farm management platforms. This evolution is mirrored in recent industry activity: exhibitors at the 2026 Irrigation Show, co-located with Groundwater Week in Las Vegas, showcased a wave of innovations spanning connectivity upgrades, energy-efficient designs, and hybrid control architectures. Startup winners announced at the 2025 show further highlighted emerging product directions, including alkaline battery-powered GSM controllers that extend reliable operation in off-grid or low-infrastructure environments. These developments indicate that the technology frontier is expanding in both connectivity and deployment flexibility, opening new addressable use cases.
Policy and Regulatory Dynamics as a Demand Accelerator
Regulatory frameworks are increasingly acting as both a compliance gate and a demand catalyst. The US EPA's updated WaterSense criteria for irrigation controllers, requiring independent certification for efficiency and performance with new labeled controllers available as of March 2026, establish a clearer benchmark for procurement teams and municipal buyers. Certification is becoming a de facto market access requirement in higher-value segments, particularly where public funding or rebate eligibility is tied to labeled products. At the municipal level, rebate programs are lowering the effective purchase price for end users. Programs such as the 2026 Woodbury, Minnesota initiative and the Hays, USA program offer discounts of up to 100 dollars for WaterSense-labeled smart controllers, directly stimulating adoption among residential and small commercial buyers.
State and local building codes are reinforcing this pull. In Minnesota, for example, WaterSense-certified controllers are required for all new systems installed after 2020, embedding the technology into standard construction and landscaping practice. At the same time, government-sector validation is building confidence in performance claims. The US Department of Energy's Federal Energy Management Program notes that advanced controllers, including both sensor-based and weather-based models, demonstrate water use reductions of 15 to 40 percent in federal applications. This range is significant because it spans diverse climates, system ages, and management practices, suggesting that well-deployed smart controls can deliver consistent savings across varied conditions. For commercial and institutional buyers, these documented outcomes reduce perceived risk and strengthen the business case for upgrade cycles.
Demand-Side Behavior and the Broadening Application Base
Demand is evolving along two reinforcing paths. In agriculture, controllers are increasingly positioned as components of precision farming systems rather than standalone timing devices. The emphasis is on matching irrigation output to crop needs, soil conditions, and evapotranspiration patterns, often in concert with drip and micro-irrigation infrastructure. This application orientation favors controllers that integrate with broader agronomic data flows and can operate reliably in demanding field environments. In non-agricultural settings, demand is driven by a mix of water cost sensitivity, sustainability commitments, and regulatory compliance. Commercial property managers, municipal grounds departments, and landscape contractors are all evaluating controllers through the lens of total cost of ownership, including labor savings from remote management, reduced water billing, and eligibility for incentives. The growing share of non-agricultural applications in market revenue reflects this diversification, as does the continued strength of agricultural demand in regions where irrigation efficiency directly affects yield stability and input costs.
Supply Chain and Cost Structure Pressures
Cost dynamics are introducing both constraints and opportunities. The Irrigation Association reported that a 25 percent tariff on steel and aluminum imports announced in February 2025 will increase costs for irrigation manufacturers and components. For hardware-intensive products, these input cost pressures can affect pricing strategy, margin structure, and the economics of localized production. The impact is not uniform; companies with diversified supplier bases, flexible manufacturing footprints, or higher-value product mixes may absorb or offset cost increases more effectively than those dependent on commodity-driven assemblies. At the same time, the same cost environment is accelerating interest in design efficiencies, component standardization, and software-led value creation that can differentiate offerings without proportionally increasing bill-of-materials expense. Procurement teams are increasingly weighing total cost of ownership against upfront price, which creates room for premium, certified, and integrated solutions when they can demonstrate clear operational returns.
Smart Irrigation Controllers Market
Competitive Landscape and Leading Strategies
Established Players and Divergent Positioning
The competitive set reflects a blend of established irrigation brands, precision agriculture specialists, and software-leaning control innovators. Hunter Industries, headquartered in Tualatin, Oregon, focuses on smart Wi-Fi and internet-connected controllers, including the MCC series and Hydrawise integration. Its positioning emphasizes residential and light commercial usability, remote management, and ecosystem connectivity that lowers the barrier to adoption for contractors and end users. Rain Bird Corporation, based in Glendora, California, offers modular and weather-based smart options through the ESP-ME3, LNK WiFi, and ESP-TM2 series. Its strategy leans on modularity, serviceability, and a broad installed base that supports retrofit and upgrade cycles. The Toro Company, in Bloomington, Minnesota, provides DXi central control and Irritrol Rain Master controllers for commercial and residential applications. Toro's recent catalog release effective January 2026 underscores a focus on clear product segmentation and pricing transparency across central control and distributed controller lines, catering to projects that require scalable management across multiple zones or sites.
Netafim brings a precision agriculture orientation, with digital farming and NMC Junior Pro controllers designed for drip systems and field-level control. Its value proposition is tightly linked to yield optimization, water precision, and integration with broader agricultural management practices. Galcon, operating globally from Israel, specializes in advanced smart controllers for residential, agricultural, and golf applications, emphasizing multi-zone flexibility and application-specific programmability. HydroPoint Data Systems, based in Santa Barbara, California, develops weather-based and sensor-integrated smart controllers for commercial and agricultural use, with a positioning that blends data-driven control logic and connectivity suitable for managed properties and institutional landscapes.
Market Structure and Strategic Implications
Market concentration remains elevated, with the top three companies accounting for approximately 62.5 percent of revenue and the top five representing about 78.2 percent. This concentration indicates that scale, brand recognition, distribution relationships, and installed-base advantages still matter significantly. However, concentration also masks meaningful segmentation in product architecture, application focus, and region-specific demand. The presence of strong regional and application specialists suggests that differentiation is increasingly achieved through fit rather than sheer breadth. Manufacturers that can align certification readiness, connectivity standards, and application-specific features with local rebate and code environments are better positioned to capture share in high-growth pockets. At the same time, the pipeline of startup activity and niche product launches indicates that new entrants can find openings by targeting underserved use cases, such as off-grid power options, simplified installation profiles, or specialized integrations for municipal and institutional procurement.
The competitive trajectory is likely to feature both consolidation and continued specialization. Larger incumbents may pursue tuck-in acquisitions or partnerships to expand software capabilities, sensor integration, or regional service coverage. Specialist players may deepen application expertise and certification compliance to defend and expand niches. The key differentiator over the next several years will be the ability to deliver verified performance, interoperable connectivity, and a clear path to total cost of ownership savings for the buyer, rather than connectivity alone.
Future Trends and Commercial Opportunities
Trend One: Certification-Driven Procurement and Incentive-Linked Adoption
As WaterSense labeling and state or municipal code requirements become more embedded in procurement standards, certified controllers will increasingly function as a baseline expectation in higher-value segments. The commercial opportunity lies in aligning product portfolios, documentation, and channel enablement with certification criteria and incentive architectures. Manufacturers and distributors that can streamline the path to compliant deployment, provide clear performance evidence, and support rebate navigation will gain an advantage in municipal, institutional, and regulated residential channels. For buyers, the practical implication is that selection criteria should incorporate certification status, verified water savings ranges, and compatibility with local incentive programs as standard evaluation factors.
Trend Two: Integrated Control as a Platform for Water Management
Controllers are evolving from isolated scheduling devices into nodes within broader water and site management platforms. The trend toward sensor integration, weather-based adaptation, and centralized control broadens the scope of value that can be delivered, including pressure optimization, leak indication, and multi-site management. This creates opportunities for solutions that emphasize interoperability, data usability, and service-oriented business models. For commercial property portfolios, agricultural operators, and landscape service providers, the upside is in reducing manual oversight, improving consistency across sites, and tying control decisions to operational metrics that matter to finance and sustainability teams. The risk is that fragmented ecosystems or proprietary locks can slow adoption; buyers will increasingly favor solutions that connect to existing infrastructure and reporting workflows without demanding wholesale replacement.
Trend Three: Cost and Supply Chain Realignment shaping Product Architecture
Input cost pressures and trade policy uncertainty are likely to continue influencing product design and sourcing decisions. Over the next three to five years, expect more emphasis on modular architectures, selective localization, and design choices that reduce exposure to volatile commodities while preserving performance. This environment favors companies that can balance cost discipline with differentiation through software, usability, and certified performance. For investors and manufacturers, the strategic question is whether cost pressures will consolidate supply around a smaller set of globally scaled producers or whether regionalized, application-tuned offerings will capture meaningful share by better matching local requirements and incentive environments. The answer will vary by region and application, and both dynamics can coexist.
PW Consulting
Strategic Action Points for Decision Makers
For Manufacturers and Product Leaders
Prioritize certification readiness and total cost of ownership proof. Align product development with the latest WaterSense criteria and other relevant efficiency standards, and prepare clear documentation that supports procurement and rebate eligibility. Invest in connectivity and interoperability that reduce integration friction for contractors and end users, and ensure that field serviceability and supply chain resilience are designed into the product roadmap, not treated as afterthoughts. Where input cost pressure is acute, explore modular design and supplier diversification to protect margins without eroding performance.
For Investors and Strategic Partners
Focus on segments where regulation, incentives, and verified savings converge to create durable demand. The strongest near-term opportunities are likely in certified smart controllers for municipal and institutional procurement, precision agriculture integrations that tie control to yield and input efficiency, and service-oriented models that monetize remote management and analytics. When evaluating targets or partnerships, assess certification posture, channel access, installed-base momentum, and the ability to demonstrate water and labor savings in real-world deployments. Monitor startup activity for novel power, connectivity, and integration approaches that could redefine sub-segments or become acquisition targets.
For Procurement and Operations Leaders
Use efficiency certification and incentive availability as initial screening criteria, then evaluate total cost of ownership across water savings, labor reduction, serviceability, and interoperability. Favor solutions that can integrate with existing management workflows and provide usable data for ongoing optimization. In regions with code mandates or active rebate programs, align replacement and new-install cycles with certified options to secure compliance and financial support. Build internal evaluation standards that reflect documented savings ranges and the operational realities of your sites or portfolios, rather than relying on generic feature checklists.
Worldwide Environment Controllers Market
The irrigation controllers market is moving from a phase of incremental smartification to one where certification, integration, and verified performance determine competitive outcomes. Companies and buyers that treat controllers as part of a broader water management strategy, and that align product and procurement decisions with regulatory and incentive realities, will capture more of the value created by the next wave of adoption. For decision makers seeking deeper segmentation, region-specific dynamics, and customized scenario analysis, the full research report provides detailed breakdowns and extended data to support planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Irrigation Controllers Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


