



Iron Ore Market at $215B: 3.9% CAGR Shifts & Strategic Outlook to 2032

The Iron Ore Market at a Strategic Inflection Point: Navigating Growth, Disruption, and Value Creation
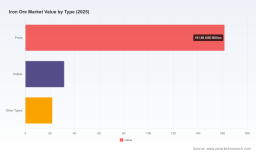
The global iron ore market is entering a phase defined by steady expansion layered with structural volatility. Valued at approximately $215.0 billion in 2025, the market has demonstrated consistent upward momentum since 2020, reflecting a compound annual growth rate of 3.9% through the 2032 forecast horizon. This trajectory projects the sector past the $340 billion threshold by the end of the decade, driven by sustained steel production, evolving metallurgical demands, and shifting trade dynamics. The numbers tell a story of durable demand, but beneath the aggregate figures lies a more complex reality: capacity expansions, regulatory shocks, price normalization, and strategic realignments are reshaping how value is captured across the supply chain. For executives, investors, and procurement leaders, the imperative is no longer simply tracking volume growth. It is understanding where margins will compress, where premium differentiation will emerge, and how supply architecture will reorganize in response to policy and technology shifts.
Market Context and the Core Challenges Defining This Cycle
The iron ore sector’s expansion from roughly $163 billion in 2020 to the $215 billion midpoint in 2025 reflects a market that has absorbed pandemic-era disruptions, supply chain recalibrations, and cyclical price swings while maintaining a clear growth path. Yet the headline trajectory masks three interconnected challenges that will dictate competitive outcomes over the next several years.
First, price normalization is compressing revenue expectations for operators that relied on elevated unit values to justify capital expenditures and margin expansion. After averaging above $112 per ton in the first nine months of 2024, global iron ore unit values declined to approximately $99 per ton in the comparable period of 2025. This pull-back matters because pricing discipline is no longer guaranteed by tight supply alone; buyers are increasingly sophisticated, alternative raw materials are gaining traction in specific metallurgical applications, and freight and logistics costs continue to introduce volatility into realized pricing. Operators and traders must now plan for a regime where volume growth, grade optimization, and cost efficiency matter more than riding a rising price cycle.
Second, regulatory interventions are fragmenting trade flows and forcing regional repositioning. The restoration and escalation of steel tariffs on imports from all countries, raised to a 50% level effective in early 2025, has reshaped the competitive calculus for exporters targeting North American markets. Tariffs of this magnitude do not merely raise costs; they alter sourcing strategies, incentivize domestic production where feasible, and compress the economics of long-distance iron ore shipments into protected markets. This creates a bifurcated landscape: regions with integrated steel ecosystems and policy support can defend share, while export-dependent operators must navigate narrower margins and more complex negotiation dynamics with steelmakers seeking to manage input costs.
Third, the structural transition toward lower-emission steelmaking is introducing both opportunity and friction. Direct reduction pathways and alternative feedstock requirements are growing, but the capital intensity of conversion, the availability of suitable iron ore grades, and the readiness of downstream infrastructure mean that demand shifts will be uneven across regions and customer segments. The market is not moving in a single direction; it is splitting into metallurgical niches where premium fines, specialized pellets, and consistent quality specifications command different pricing logic than commoditized volumes. Companies that treat iron ore as a homogeneous bulk commodity will face increasing difficulty in defending position as customers tailor input strategies to decarbonization targets and operational flexibility.
The Forces Reshaping Supply, Demand, and Competitive Positioning
The iron ore market’s evolution is being driven by a set of interlocking forces that extend beyond cyclical supply and demand. Understanding these drivers is essential for identifying where growth will be durable and where exposure will be most vulnerable.
Technology and metallurgical innovation are redefining what constitutes valuable iron ore. As steelmakers evaluate direct reduction, hydrogen-enabled pathways, and more efficient blast furnace operations, the premium attached to consistent high-grade material, low impurities, and predictable granulometry is increasing. Operations that can deliver concentrate and pellet feed with tight specification control are better positioned to capture margin resilience, particularly in segments where metallurgical performance translates directly into energy savings or emission reductions downstream. Technology-driven differentiation is not limited to the mine site; it extends to beneficiation capabilities, logistics optimization, and the ability to align product specs with customer conversion processes. In this environment, the value of a tonne is increasingly a function of what it enables rather than what it weighs.
Policy and regulatory environments are becoming a decisive competitive variable. Trade policy is no longer a background condition; it is an active determinant of routing, customer mix, and pricing power. The imposition of higher steel import tariffs has intensified the strategic importance of local and regional supply security for steel producers, while simultaneously pressuring exporters to identify alternative demand centers or negotiate terms that account for policy-driven cost structures. Regulatory trajectories around emissions, mining approvals, and indigenous or community agreements also influence the speed and cost of capacity additions. Projects that can align with clear regulatory frameworks and long-term development agreements gain a meaningful advantage in execution certainty, while operators facing shifting approval regimes or policy volatility must price that risk into their expansion plans.
Demand-side behavior is shifting as steel producers balance volume requirements with cost control and decarbonization mandates. The largest application segment for iron ore remains steel production, and that anchor demand provides the market’s underlying stability. However, buyer behavior is becoming more segmented. Large integrated steelmakers are increasingly negotiating around grade consistency, delivery reliability, and total cost of conversion rather than focusing solely on spot price movements. At the same time, direct reduction and other alternative processes are expanding their share of attention, creating incremental demand for materials suited to those pathways. The practical implication is that demand is consolidating around relationships and specifications, not just price. Suppliers that can demonstrate operational consistency and align product attributes with customer process requirements are better positioned to secure longer-term arrangement stability, even in a normalizing price environment.
Supply chain and cost structure dynamics are reshaping where and how iron ore reaches markets. Logistics remains a critical lever in realized economics, particularly for long-haul export routes. Any disruption in port capacity, rail throughput, or maritime freight introduces volatility that can erode the advantage of low-grade-cost production. At the same time, cost structures are being tested by the need to maintain output while managing inflation in energy, labor, and capital equipment. The operators that navigate this phase effectively are those treating the supply chain as an integrated system: mine planning, processing efficiency, stockpile management, and shipping coordination are increasingly evaluated as a single margin equation rather than separate functions. In a market where unit values have moderated, the ability to reduce cost per tonne and protect throughput continuity becomes a primary source of competitive advantage.
Competitive Landscape: Positioning, Differentiation, and the Evolving Structure of the Market
The iron ore market remains concentrative, with a relatively small group of large-scale operators controlling a substantial share of global supply. This concentration creates a landscape where scale, asset quality, and strategic optionality matter enormously. Yet the competitive dynamics are not static. Recent operational milestones, project developments, and regional adjustments illustrate how the leading players are actively reshaping their positions.
The major integrated producers continue to compete on the basis of tonnage reliability, ore quality, and the ability to sustain output through market cycles. Operations anchored in established mining complexes with mature infrastructure benefit from scale economics and logistics familiarity, while also facing the ongoing challenge of maintaining production levels, managing stockpile balances, and responding to cost pressures. In this context, the recent achievement of record Pilbara output by one of the leading Australian producers, alongside the first ore shipment from the Simandou high-grade project in Guinea, highlights two contrasting but complementary strategic thrusts: maximizing the productivity of long-established assets while opening new high-grade supply corridors that can shift grade mix and market access over time. The shipment of a significant cumulative volume milestone from the Pilbara region further underscores how legacy operations remain central to global supply, even as new projects begin to contribute incremental tonnage.
Worldwide Iron Ore Trade Market
In South America, a leading Brazilian producer recently reached a seven-year high in iron ore output, surpassing a key Pilbara-based peer’s volume for the first time since 2018. This reversal is strategically significant because it shows that operational reliability and capacity execution can alter the ranking of major suppliers within a single cycle. For the market, it signals that the balance of supply between established regions is not fixed; it responds to operational performance, infrastructure utilization, and the ability to keep complex mining and logistics systems running at target levels. Premium concentrate, fines, and pellet offerings from major Brazilian and South African operations continue to play a differentiated role, particularly for customers seeking material that supports specific metallurgical outcomes.
The competitive picture also includes producers with more regionally concentrated footprints. In North America, a major domestic steel and mining company’s decision to idle portions of its Minnesota operations as part of a stockpile reduction strategy reflects a more tactical approach to balancing supply, inventory, and market conditions. The resulting decline in U.S. domestic iron ore production illustrates how quickly regional supply can adjust when operators choose inventory discipline or cost management over volume retention. This kind of localized adjustment matters because it interacts directly with policy-driven demand dynamics. When import tariffs raise the cost of foreign material, domestic supply becomes more strategically valuable, but only if it is available at a competitive cost and in sufficient quantity to support steelmaking schedules.
Steelmakers with integrated mining interests add another layer to the competitive landscape. By controlling upstream supply in select assets, these companies can better align raw material availability with steel production planning, reduce exposure to spot market volatility, and support longer-term operational continuity. Recent infrastructure expansion in Liberia, including the completion of a new concentrator facility and the extension of a long-term mineral development agreement, demonstrates how integrated players are building longer-duration supply visibility in emerging regions. This type of move is not merely about adding tonnage; it is about securing a predictable input base that supports downstream strategic planning over decades rather than quarters.
Taken together, the competitive landscape is evolving along several axes. Scale remains essential, but it is no longer sufficient on its own. Differentiation is increasingly tied to grade consistency, logistical reliability, regional access, and the ability to align product specifications with evolving steelmaking requirements. At the same time, the market is not moving toward uniform consolidation. Instead, it is developing pockets of integration around key supply corridors and customer relationships, while leaving room for specialized operators that can serve premium or regionally targeted niches. New entrants and project developers face high barriers in the form of capital intensity, permitting complexity, and the need to establish reliable offtake and logistics arrangements, but targeted projects that can deliver distinctive grade profiles or open new export routes can still alter local competitive dynamics.
What the Next Three to Five Years Will Likely Bring
The iron ore market’s medium-term trajectory will be shaped by the interaction of demand durability, supply execution, policy direction, and metallurgical transition. Several trends are likely to define strategic outcomes over the next three to five years.
Trend one: volume growth will continue, but margin capture will depend on grade and specification management. The market is projected to expand steadily toward the mid-2030s, supported by ongoing steel production and incremental demand from alternative reduction pathways. However, as unit values moderate and buyers become more selective, the ability to command premium realization will increasingly hinge on product consistency, impurity control, and alignment with customer processes. Suppliers that can reliably deliver high-quality fines and pellets with predictable metallurgical behavior will be better positioned to preserve pricing leverage, while those competing primarily on volume may face greater pressure from both substitutes and more demanding procurement standards.
Trend two: trade policy and regional supply security will redraw procurement maps. Tariff structures, domestic production levels, and logistics constraints are likely to keep regional sourcing strategies in sharp focus. In markets where import costs are elevated by policy, steelmakers will continue to weigh the trade-off between domestic supply, established export relationships, and the operational implications of switching sources. This does not mean globalization retreats entirely, but it does mean that supply routing will be more deliberately engineered. Exporters with diversified destination markets, flexible logistics, and credible grade offerings will have more optionality, while those heavily exposed to a single policy-sensitive corridor will need to plan for discontinuity and negotiate accordingly.
Trend three: decarbonization-driven demand segmentation will accelerate, but unevenly. The shift toward lower-emission steelmaking will not unfold at the same pace across every region or producer. Some customers will pursue direct reduction and related pathways more aggressively, increasing interest in materials that support those processes. Others will continue to optimize blast furnace operations and look for iron ore attributes that reduce energy intensity or improve yield. The result will be a more segmented demand environment in which premium product lines, specialized pellets, and consistent concentrate supply gain relative importance. Companies that invest early in understanding customer conversion needs and align product development with those requirements will have an advantage in securing more resilient demand channels.
Carbonate Ore Market
These trends create commercial opportunity, but they also carry risk. Price volatility may persist if macroeconomic conditions, freight markets, or policy adjustments shift quickly. Capital projects can face delays from permitting, community engagement, or cost inflation, altering the timing and composition of new supply. And the pace of metallurgical transition may be slower or faster than anticipated, affecting the trajectory of demand for specific grades and product forms. Strategic planning must therefore account for multiple scenarios rather than a single linear forecast.
Strategic Actions for Decision-Makers
For steel manufacturers and integrated producers, the priority is to treat iron ore procurement as a strategic input system rather than a commodity purchasing function. That means investing in supplier relationships that deliver specification reliability, evaluating total cost of conversion rather than nominal price alone, and building sourcing flexibility that can respond to tariff changes or logistics disruptions. Where feasible, securing longer-term supply visibility through structured agreements or integrated access can reduce exposure to abrupt market shifts, particularly in policy-sensitive regions. At the same time, manufacturers should monitor how customer-facing decarbonization targets affect raw material requirements, and align internal planning with the grade and form factors that support those goals.
For investors and capital allocators, the opportunity lies in distinguishing between operators that are built for volume exposure and those that can capture value through differentiation and execution discipline. Assets with strong logistics integration, consistent high-grade output, and credible cost control are better positioned to perform across a range of price environments. Equally important is the regulatory and project execution profile of new supply. Developments that combine clear alignment with local agreements, defined export routes, and metallurgically valuable product characteristics offer more resilient upside than undifferentiated tonnage additions. Portfolio exposure should also account for regional policy risk, especially where tariff or trade policy changes can rapidly alter the attractiveness of specific supply corridors.
For procurement leaders and supply chain decision-makers, resilience should be designed into sourcing strategies before disruption forces a reaction. That includes maintaining visibility into multiple qualified suppliers, understanding the specification dependencies of internal steelmaking or fabrication processes, and stress-testing the impact of freight fluctuations and policy changes on total landed cost. Stockpile and inventory strategies should be evaluated not only for working capital implications but also for their effect on operational continuity if supply interruptions occur. In an environment where unit values can shift and trade policy can reshape relative costs quickly, the organizations that perform best will be those that combine cost discipline with optionality and deep supplier intelligence.
PW Consulting
The iron ore market is large enough to absorb disruption and flexible enough to reward precision. The winners in the next phase will be those who move beyond aggregate growth assumptions and build decisions around grade strategy, regulatory exposure, logistics resilience, and customer-aligned product value. For organizations that need granular segment data, regional cost structures, and customized scenario planning to support those choices, a full research report with detailed segmentation, competitive benchmarking, and forward-looking market modeling can provide the depth required to act with confidence.
For detailed analysis of this topic, please visit the official page: Iron Ore Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


