



Fire Pump Market to Hit $665M by 2032: Why 4.96% CAGR Signals a Strategic Shift

Global Fire Pump Market: Strategic Trends, Competitive Dynamics, and Commercial Opportunities Through 2032
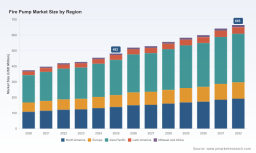
The fire pump sector has evolved from a commoditized infrastructure component into a strategically differentiated business segment where reliability, regulatory compliance, and technical integration define market positioning. Over the historical review window from 2020 through 2025, global market revenue expanded from approximately 375 million USD to 482 million USD, reflecting a compound annual growth rate of 4.96 percent. Forward projections through 2032 indicate continued expansion toward roughly 665 million USD, driven by sustained capital formation in commercial real estate, industrial facilities, and offshore energy infrastructure. The trajectory is not uniform. Growth phases are shaped by regulatory cycles, regional construction activity, raw material volatility, and the pace at which manufacturers integrate monitoring capabilities, hydraulic efficiency, and application-specific engineering into product portfolios.
The market structure remains moderately concentrated. Three leading players collectively account for approximately 45 percent of total revenue, while the top five capture around 55 percent. This concentration level indicates a sector where established manufacturers hold meaningful share through product breadth, certification expertise, and long-term service relationships, yet it also leaves meaningful room for regional specialists, project-driven integrators, and technology-enabled entrants to capture niche positions. For executive teams evaluating exposure to fire protection equipment, the landscape presents a blend of stable baseline demand, cyclical project volatility, and clear differentiation opportunities for firms that can align product development with compliance evolution and end-user operational expectations.
Core Macro Dynamics and Structural Shifts
The revenue curve over the 2020 to 2025 period demonstrates steady expansion rather than explosive growth, which is typical of essential safety equipment markets where demand is anchored to building codes, industrial capacity additions, and asset life-cycle replacement programs. The moderation in growth velocity after the early post-2020 recovery reflects a normalization phase in which supply chains adjusted to elevated input costs, lead-time variability, and workforce constraints in fabrication and testing operations. As the market moves through the 2026 to 2032 forecast horizon, growth is expected to be sustained by ongoing urban development, industrial modernization, and energy sector projects that require integrated pump skids and high-pressure fire protection systems.
Three structural challenges define the current inflection point. First, raw material cost variability, particularly in steel-intensive pump housings, casings, and skid assemblies, introduces margin pressure and pricing complexity. Recent market data indicates that US steel prices averaged approximately 1,086 USD per metric ton in May 2026, up 3.5 percent from April, with hot-rolled coil near 1,109 USD per ton in June 2026. For manufacturers, this environment demands disciplined cost management, hedging strategies, and product engineering that reduces material intensity without compromising hydraulic performance or code compliance.
Second, regulatory frameworks continue to shape procurement cycles and product qualification requirements. The NFPA 20 Standard for the Installation of Stationary Pumps for Fire Protection remains the foundational reference for selection and installation as of 2026, while ASSE 15010 water-based fire protection certification qualifications and processes are undergoing changes beginning in early 2025 for inspection and testing of fire pumps. For suppliers and specifiers, evolving certification expectations create both administrative burden and competitive advantage for organizations that can streamline compliance, documentation, and field verification.
Third, the market faces an ongoing tension between standardization and customization. End-users in commercial building sectors increasingly favor packaged pump systems and compact configurations that simplify installation and maintenance, while oil and gas, marine, and large industrial facilities require engineered solutions that address site-specific pressure, flow, and environmental conditions. Balancing these demands requires manufacturing flexibility, modular design philosophies, and service teams capable of supporting both off-the-shelf and project-engineered deployments.
Key Drivers Shaping Market Trajectory
Technology Innovation and Monitoring Integration
A defining trend in the fire pump sector is the transition from purely mechanical reliability to connected, condition-aware systems. Historically, fire pumps were evaluated primarily on flow capability, pressure performance, and durability under intermittent duty cycles. Today, manufacturers are embedding telemetry, remote status monitoring, and diagnostic interfaces that enable facility operators and service contractors to track run-hours, alarm states, and performance deviations without manual inspection alone. This shift aligns with broader operational expectations in commercial real estate and industrial facilities, where uptime assurance, predictive maintenance, and rapid response capability are increasingly tied to asset management strategies.
Product launches in recent months illustrate this direction. In January 2026, Armstrong Fluid Technology introduced a new range of Constant Speed Vertical-In-Line Fire Pumps with high-pressure ratings up to 160 PSI for both 60Hz and 50Hz markets. The expansion into higher-pressure vertical in-line configurations reflects demand for compact, high-performance solutions suitable for taller buildings, space-constrained mechanical rooms, and applications where vertical footprint limitations constrain traditional horizontal installations. Vertical in-line designs also appeal to specifiers seeking reduced installation complexity and simplified alignment, provided the hydraulic and reliability requirements are met for the intended duty point.
Regulatory Environment and Certification Evolution
Regulation is not merely a constraint in this market; it is a design parameter and a commercial gate. NFPA 20 continues to define the baseline expectations for stationary fire pump selection and installation, creating a shared technical language across manufacturers, engineering firms, authorities having jurisdiction, and service providers. At the same time, evolving certification processes such as the ASSE 15010 updates introduce new scrutiny around inspection and testing practices. For manufacturers, the practical implication is that product approval, documentation rigor, and test protocol alignment are becoming differentiators in bidding and specification capture. Firms that invest early in certification readiness and clear compliance narratives tend to reduce deployment friction and improve win rates in regulated markets.
For purchasers and engineering teams, regulatory dynamism creates the need for supplier partners who can interpret standards consistently across regions and project types. In practice, this means that product capability alone is insufficient unless accompanied by repeatable installation guidance, commissioning support, and post-installation testing documentation that satisfies jurisdictional requirements. The regulatory layer therefore reinforces the value of established brands and technically credible service networks, while also opening opportunities for manufacturers that can simplify compliance through integrated documentation packages and standardized test evidence.
Demand-Side Changes in Commercial and Industrial Sectors
Demand patterns are shaped by the interplay of construction pipelines, facility modernization programs, and risk management priorities. Commercial buildings remain a dominant application area, with fire pump demand linked to new development, code-driven renovations, and replacement cycles in aging mechanical systems. Industrial facilities represent the second major demand pillar, where fire protection requirements intersect with process safety, hazardous area considerations, and large-scale infrastructure planning. In both segments, purchasers are increasingly focused on lifecycle economics rather than lowest initial equipment cost, which advantages solutions that combine reliability, serviceability, and remote monitoring capabilities.
Water Pumps Market
In parallel, energy sector activity continues to influence demand for engineered fire pump skids and high-pressure systems. Contract awards such as Sulzer’s November 2025 win for multiple integrated pump skids for Petrobras P-84 and P-85 FPSOs, with delivery in early 2026, underscore how offshore and large industrial projects generate specialized demand for integrated packages rather than standalone pump units. These projects reward suppliers with skid integration expertise, application engineering depth, and the ability to deliver systems that meet both fire protection and broader process interface requirements.
Supply Chain Resilience and Cost Structure Adaptation
The sector’s cost structure is sensitive to steel pricing, casting lead times, machining capacity, and the availability of qualified assembly and test labor. Companies that have strengthened supply chain resilience through multi-sourcing, forward inventory positioning, and modular subassembly strategies are better positioned to maintain delivery reliability during input price spikes. Equally important is product design discipline: pumps and skid systems that optimize material usage, standardize components across product lines, and reduce rework in fabrication can absorb input cost pressure more effectively than less standardized designs.
From a commercial standpoint, this environment favors manufacturers that can offer transparent pricing mechanisms, delivery certainty, and configuration flexibility. Procurement teams are increasingly weighing supplier reliability and compliance readiness against unit price, particularly for projects where delay costs and inspection risks are significant. This dynamic reinforces the strategic value of regional manufacturing footprints, localized service capabilities, and strong relationships with distributors and installation contractors.
Competitive Landscape and Strategic Positioning
Differentiation Vectors Among Leading Players
The market’s leading participants compete across several overlapping dimensions: product range breadth, application-specific engineering, certification depth, service networks, and increasingly, digital monitoring and integration. Pentair manufactures Aurora and Fairbanks Nijhuis fire pumps in horizontal and vertical configurations for global fire protection systems, positioning itself around established brand lines and a broad configuration portfolio. Grundfos produces fire pumps within a wider pump portfolio, leveraging its broader hydraulic competence and distribution relationships. NAFFCO offers fire protection pumps and related equipment for commercial and industrial use, often competing on regional responsiveness and bundled system solutions in Middle East and broader project markets.
Flowserve supplies industrial pumps including fire pump solutions, drawing on its broader engineered pump capabilities and industrial service infrastructure. Sulzer provides integrated fire pump skids and solutions for oil and gas and general fire protection, which aligns well with project-based demand where skid-level integration and application engineering matter. Kirloskar Brothers manufactures fire pumps for municipal and industrial applications, reflecting strength in regional manufacturing and cost-competitive engineering. SPP Pumps produces specialist fire pumps for fixed and portable systems, and Peerless Pump Company designs and manufactures horizontal and vertical fire pumps, including its FireConnect monitoring system, which illustrates how traditional pump manufacturers are extending into connected diagnostics to differentiate their offerings.
Armstrong Fluid Technology offers end-suction, horizontal, vertical in-line, and multi-stage fire pumps, giving it coverage across common commercial and industrial configurations. Rosenbauer produces fire pump systems integrated into fire trucks and apparatus, representing a distinct adjacency where pump capability is embedded into mobile fire suppression platforms. Waterous has manufactured US-made fire pumps, engines, and suppression equipment since 1886, competing on legacy, domestic production, and specialized suppression system integration. CET Fire Pumps MFG Inc. produces portable fire pumps with gas and diesel engines, plus skid units and foam systems, addressing niche mobile and specialized suppression needs. Xylem provides fire pumps under the AC brand for municipal and industrial fire protection, leveraging its broader water technology and infrastructure positioning.
Filter Pump Market
Market Concentration and Evolution Patterns
With a three-firm concentration near 45 percent and a five-firm concentration near 55 percent, the market is consolidated enough that scale, certification portfolios, and global distribution matter, yet fragmented enough that specialized players can win on application fit, regional proximity, and service agility. Over the next several years, two evolutionary patterns are likely to persist. The first is selective consolidation through capability acquisition, particularly where a manufacturer seeks broader product coverage, stronger skid integration capabilities, or access to a specialized monitoring or control technology. The second is continued differentiation among regional and application-focused players who compete on responsiveness, local certification expertise, and integration with local engineering and contractor ecosystems.
New entrants face meaningful barriers in this market, including code familiarity, test and certification requirements, service network expectations, and the need for reliable production quality. However, entry opportunities exist where modular packaged systems, compact vertical configurations, and connected monitoring reduce installation complexity and improve service economics. Companies that can demonstrate consistent compliance documentation, predictable lead times, and strong field support can gain traction even in competitive bidding environments.
Forward-Looking Trends and Commercial Implications
Trend One: Connected Diagnostics as a Standard Expectation
Remote monitoring and condition awareness are likely to move from premium option to expected capability in a growing share of commercial and industrial applications. As facility operators consolidate maintenance workflows and seek earlier warning of mechanical or electrical anomalies, pumps equipped with status telemetry, fault logging, and integration-friendly interfaces will be easier to specify and retain in service. The commercial implication is that manufacturers offering genuine monitoring value—rather than superficial connectivity—will improve after-service revenue potential and strengthen customer retention. A practical risk is that monitoring features must be supported by reliable data infrastructure, cybersecurity considerations, and service processes capable of acting on the information collected.
Trend Two: High-Pressure and Compact Vertical Solutions Gaining Share
The expansion of high-pressure vertical in-line options reflects demand for space-efficient, high-performance configurations suitable for tall buildings, constrained mechanical rooms, and applications where footprint and installation simplicity matter. This trend favors manufacturers that can deliver reliable vertical designs with robust sealing, alignment, and bearing arrangements while meeting code requirements across 50Hz and 60Hz regions. For procurement teams, compact and high-pressure solutions can reduce installation cost and improve building layout flexibility, but they require careful specification to ensure duty-point suitability and long-term serviceability.
Trend Three: Integrated Skid and Application-Engineered Packages in Energy and Industrial Projects
Offshore and large industrial projects continue to create demand for integrated skid systems that combine pumps, drivers, controls, and interface engineering into coordinated packages. Contract awards in FPSO and similar large-scale energy projects demonstrate that suppliers with skid integration capability and application-specific design competence can secure high-value projects even in concentrated markets. The commercial opportunity lies in expanding from component supply to system-level value creation, where integration reduces field engineering burden and improves commissioning reliability. A key uncertainty is project timing and capital expenditure variability in energy markets, which can shift demand from steady pipelines to episodic large contracts.
Strategic Implications for Decision-Makers
For Fire Pump Manufacturers and Integrators
- Align product roadmaps with compliance evolution and monitoring expectations. Invest in certification readiness, documentation clarity, and telemetry features that deliver actionable maintenance insight rather than simple data visibility.
- Strengthen cost and supply chain resilience. Standardize key components, manage steel exposure through procurement discipline and design efficiency, and protect delivery reliability during input price volatility.
- Expand toward system-level value where appropriate. Skid integration, packaged systems, and application-specific engineering can improve project margins and differentiate offerings in industrial, energy, and complex commercial deployments.
- Build service-aligned commercial models. In a market where uptime, installation correctness, and compliance documentation matter, service responsiveness and commissioning support can be as decisive as product specifications.
For Investors and Strategic Acquirers
- Prioritize businesses with durable compliance positioning, recurring service relationships, and credible monitoring or integration capabilities. Brand heritage alone is insufficient without modern product support and service economics.
- Evaluate regional specialists for capability tuck-ins. Strong local certification knowledge, contractor relationships, and application focus can complement broader platforms and accelerate entry into specific geographies or end markets.
- Monitor steel cost exposure and margin discipline as part of due diligence. Companies with standardized designs, flexible sourcing, and transparent cost pass-through mechanisms are better positioned to preserve profitability when input prices fluctuate.
- Watch for consolidation driven by product coverage gaps and digital capability needs. Targets that add vertical configurations, packaged systems, or connected diagnostics may offer strategic leverage beyond revenue scale.
For Procurement, Engineering, and Facility Decision-Makers
- Evaluate total lifecycle value rather than initial price alone. Installation complexity, commissioning support, compliance documentation, and serviceability can materially affect operating risk and long-term cost.
- Specify with monitoring and serviceability in mind. Where uptime assurance is critical, select configurations that enable condition tracking and simpler field support, and ensure that service providers can act on the data provided.
- Confirm compliance readiness early. Verify that proposed pump systems align with NFPA 20 expectations and current inspection and testing practices, including any changes to certification processes, to avoid delays during commissioning and jurisdictional review.
- Plan for supply-side variability. Given steel price movements and project timing risk, include delivery certainty, lead-time transparency, and contingency planning in procurement decisions, especially for time-sensitive commercial and industrial projects.
The fire pump market is entering a phase in which growth is supported by steady demand fundamentals, but competitive outcomes will increasingly depend on compliance mastery, product differentiation, and the ability to deliver reliable installation and service performance. The most compelling commercial opportunities will accrue to manufacturers and integrators that combine technical breadth with execution discipline, and to buyers who specify with lifecycle performance and regulatory alignment in mind. For teams that require detailed segmentation data, regional demand patterns, type-level revenue splits, and company-level competitive profiles to support planning and investment decisions, the full research report provides expanded datasets and tailored scenarios that build on the strategic direction outlined here.
PW Consulting
For detailed analysis of this topic, please visit the official page: Fire Pump Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


