



Electric Bike Market 2026: 10.54% CAGR Trajectory and the Asia Pacific Shift

Electric Bike Market: Strategic Trends and Commercial Opportunities (2026-2032)
Market Overview and Core Challenges
The electric bike market has transitioned from a niche alternative to a mainstream mobility solution, demonstrating sustained expansion over the past five years. Between 2020 and 2025, industry revenue climbed from approximately 41.9 billion USD to 73.2 billion USD, reflecting a compound annual growth rate that underscores the sector's resilience and accelerating adoption. Forward projections indicate continued momentum, with revenue expected to reach 147.2 billion USD by 2032, translating to a CAGR of 10.54 percent across the 2026-2032 forecast horizon. This trajectory positions electric bikes as one of the fastest-growing segments within the broader micro-mobility and personal transportation landscape, driven by urbanization pressures, sustainability mandates, and evolving consumer preferences for flexible, low-emission transit options.
Despite the robust growth trajectory, the industry stands at a critical inflection point where several structural challenges threaten to reshape competitive dynamics. First, regulatory fragmentation is intensifying across key markets. Jurisdictions are diverging on speed limits, motor power thresholds, battery safety mandates, and classification frameworks, creating compliance complexity for manufacturers operating across multiple regions. Second, raw material volatility is introducing cost uncertainty, particularly in battery component pricing, which directly impacts margin structures and pricing strategies. Third, market concentration remains relatively high, with the top three players holding a substantial share of global revenue and the top five firms commanding an even larger portion, which raises barriers to entry and compresses differentiation opportunities for smaller competitors. These forces collectively demand strategic agility from market participants seeking to capture growth without exposing themselves to excessive regulatory, cost, or competitive risk.
Key Drivers Shaping Market Evolution
Technological Innovation and Performance Differentiation
Technology remains the primary engine of market expansion, with advancements in motor efficiency, battery energy density, and smart connectivity reshaping product expectations. Manufacturers are increasingly embedding proprietary control units, GPS tracking, over-the-air updates, and integrated app ecosystems into their platforms. These features extend beyond novelty; they address safety concerns, enable fleet management capabilities, and create recurring engagement loops that strengthen brand loyalty. Recent model launches illustrate this trajectory: one U.S.-based brand introduced a fat-tire model with enhanced range and a proprietary control unit supporting GPS and OTG functionality, signaling how connectivity and utility features are becoming baseline expectations rather than premium add-ons. Simultaneously, performance-oriented manufacturers are pushing torque outputs and frame materials to cater to aggressive riding styles and demanding terrain, while other players focus on step-through designs and extended range to serve senior and recreational segments. The technological arms race is widening product segmentation and forcing companies to clarify whether they compete on accessibility, performance, or integrated digital experience.
Policy and Regulatory Environment as a Market Accelerant and Constraint
Policy frameworks are actively reshaping demand patterns and compliance requirements. In the United States, reciprocal tariffs on Chinese electric bicycle imports were reduced from 55 percent to 45 percent effective November 2025, easing some cost pressures on imported finished goods while still maintaining a significant trade barrier. This adjustment alters sourcing economics and encourages regional assembly or supply chain diversification strategies. Concurrently, California implemented updated State Fire Marshal safety standards for electric bike batteries effective January 2026, requiring manufacturers to demonstrate enhanced thermal management and certification compliance. In Europe, the European Commission fully enforced the revised EN 15194 standard after August 2025, harmonizing technical requirements but also tightening conformity assessment processes. Meanwhile, the United Kingdom revoked anti-dumping duties on non-folding electric bikes of Chinese origin in February 2025, opening a pathway for cost-competitive imports in that segment. Collectively, these regulatory shifts are creating a patchwork environment where successful players must navigate divergent safety, classification, and trade rules while leveraging favorable policy windows to optimize cost structures.
Demand-Side Shifts in Urban Mobility and Commercial Utility
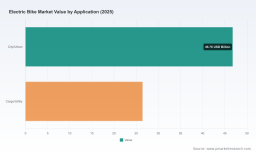
Consumer and enterprise behavior is evolving beyond recreational use toward practical, daily mobility solutions. City and urban applications continue to dominate usage patterns, reflecting the role of electric bikes in first-mile and last-mile connectivity, commute substitution, and congestion avoidance. At the same time, cargo and utility applications are gaining meaningful traction as businesses and households recognize the cost and efficiency advantages of electric cargo bikes for local deliveries, family transport, and municipal operations. This shift is reinforced by rising fuel costs, parking constraints, and corporate sustainability targets that incentivize fleet electrification at the micro-mobility level. Demand is also becoming more segmented by rider profile: high-performance models appeal to enthusiasts and trail riders, while accessible step-through designs and folding formats attract seniors, multi-modal commuters, and space-constrained urban users. These diverging demand clusters require manufacturers to align product architecture, marketing positioning, and distribution channels with specific use cases rather than relying on generic electric bike positioning.
Supply Chain and Cost Structure Dynamics
The supply chain environment is undergoing a period of recalibration as material costs, logistics constraints, and sourcing strategies interact. Lithium carbonate prices rose sharply in December 2025 and January 2026, with industrial grades increasing by double-digit percentages, placing upward pressure on battery pack costs and, by extension, finished product pricing. This volatility highlights the sensitivity of margin profiles to commodity cycles and underscores the value of long-term supplier agreements, battery chemistry diversification, and design efficiencies that reduce dependency on constrained inputs. At the same time, tariff adjustments and trade remedy decisions are prompting companies to reconsider manufacturing footprints, assembly locations, and inventory strategies. Some manufacturers are responding by emphasizing regional distribution, localized assembly partnerships, or product architectures that optimize shipping efficiency and tariff exposure. The net effect is a market where cost discipline and supply chain resilience are becoming as strategically important as product features in determining competitive outcomes.
Competitive Landscape and Leading Strategies
The competitive environment reflects a blend of regional specialists, performance-focused incumbents, and accessible-value brands, each pursuing distinct strategic positioning. Premium German manufacturers have built strong reputations around integrated drive systems, advanced battery integration, and high-end frame engineering, targeting customers who prioritize durability, ride quality, and ecosystem alignment with established component suppliers. These firms compete on engineering credibility and residual value, often anchoring their portfolios in eMTB, cargo, and city categories with sophisticated powertrain integration. U.S.-based brands occupy a broad value spectrum, ranging from budget-friendly folding and cruiser models with emphasis on quiet operation and certified electrical safety, to mid-range and premium platforms that differentiate through proprietary app controls, GPS tracking, and over-the-air update capabilities. This stratification allows American manufacturers to address price-sensitive urban riders as well as tech-conscious consumers seeking connected features. Global players such as hybrid bike leaders and Taiwanese high-end manufacturers leverage scale, alloy frame expertise, and battery option flexibility to serve commuter and performance segments with broad geographic reach. A Dutch specialist has carved out a niche in compact folding designs with efficient pedal-assist systems, targeting urban mobility users who prioritize portability and maneuverability.
Recent product activity reinforces the intensity of differentiation. A U.S. brand expanded its fat-tire lineup with enhanced range and GPS/OTG functionality, reinforcing its focus on connected adventure and urban versatility. A Taiwanese manufacturer introduced new eMTB series powered by Bosch CX motors in alloy frames, emphasizing improved affordability while maintaining performance credibility. A major global brand launched a flagship model with a carbon frame and high torque output, signaling continued investment in premium performance segments. These moves illustrate how leaders are contesting multiple battlegrounds simultaneously: range and battery endurance, motor torque and frame material, connectivity and software integration, and price-to-performance ratios across accessibility and premium tiers.
The market structure is evolving along two parallel paths. Consolidation is likely to accelerate among mid-tier players seeking scale, distribution leverage, and cost efficiencies, particularly as compliance and battery cost pressures raise the fixed-cost threshold for sustained competitiveness. At the same time, fragmentation persists in specialized niches such as cargo utility, folding urban formats, senior-focused accessibility designs, and high-performance trail categories, where targeted product architecture and community-driven branding can sustain differentiation. New entrants are most likely to succeed by focusing on underserved use cases, regional compliance advantages, or digital service ecosystems rather than attempting to compete broadly on hardware alone. Companies that combine clear segmentation, disciplined cost structures, and defensible feature sets are best positioned to navigate this environment.
Electric Bicycles Market
Strategic Trends and Outlook for 2026-2032
Several trends are likely to define the market over the next three to five years. First, connectivity and software-defined features will become increasingly central to product value propositions. As GPS tracking, app-based controls, and over-the-air updates move from differentiators to expectations, manufacturers that treat the electric bike as a platform with ongoing digital engagement will have an advantage in retention, service revenue, and fleet integration. This trend creates opportunities for brands that can build reliable software stacks, secure update pathways, and data-informed rider experiences without compromising electrical safety or user privacy.
Second, regulatory alignment and battery safety certification will increasingly shape market access and sourcing decisions. As jurisdictions tighten battery standards and harmonize technical requirements, companies with robust quality assurance processes and transparent compliance documentation will face fewer market entry frictions. The trend also opens opportunities for suppliers and assemblers that can deliver certified battery systems with traceable sourcing and consistent performance. However, the risk lies in uneven enforcement and periodic standard revisions that can disrupt product roadmaps and require rapid design adjustments.
Third, cargo and utility applications are expected to expand beyond early adopters into broader commercial and household use. Local delivery operators, municipal programs, and multi-purpose household users are likely to increase adoption as total cost of ownership advantages become more apparent and as frame, battery, and load-capacity designs improve. This trend presents opportunities for purpose-built cargo architectures, swappable battery configurations, and service networks tailored to commercial uptime requirements. The associated risk is that utility-focused models must withstand higher usage intensity, which places greater demands on component durability, warranty management, and after-sales support.
Underlying these trends are unresolved uncertainties. Commodity price swings can quickly alter margin assumptions, and tariff or trade-remedy shifts may change the cost competitiveness of imported versus regionally assembled products. Demand could also diverge by region if economic conditions affect discretionary spending or if public transport investments alter commute substitution dynamics. Manufacturers and investors should therefore treat growth as achievable but contingent on strategic choices around sourcing, compliance, segmentation, and service infrastructure.
Electric Motorcycle Market
Actionable Recommendations for Decision Makers
For manufacturers, the priority is to reinforce product architecture decisions with clear segmentation and compliance readiness. Rather than broadening portfolios indiscriminately, companies should define whether they compete on accessible value, performance credibility, or connected digital experience, and then align motor, battery, frame, and software choices accordingly. Investing in battery safety certification, traceable sourcing, and design efficiencies that reduce exposure to commodity volatility will help protect margins and ensure continuity across regulatory cycles. Manufacturers should also evaluate assembly and distribution footprints against tariff exposure and shipping efficiency, especially as trade conditions remain fluid. Building proactive after-sales and service capabilities is equally important, particularly for cargo and utility models where uptime and durability directly influence commercial adoption.
For investors, the opportunity lies in identifying players with defensible segmentation, resilient cost structures, and scalable digital or service propositions. Due diligence should extend beyond top-line growth to assess battery supply agreements, certification readiness, tariff sensitivity, and the credibility of software and connectivity roadmaps. Companies that combine clear use-case positioning with disciplined manufacturing and compliance practices are more likely to sustain margins and navigate consolidation pressures. Investors should also monitor regions where regulatory changes create temporary cost advantages or new import pathways, as these conditions can reshape competitive positioning over short to medium horizons.
PW Consulting Automotive & Machinery Research Center
For procurement and fleet decision makers, the focus should be on total cost of ownership, safety compliance, and operational fit rather than upfront price alone. Evaluating battery certification status, warranty structures, service network coverage, and load-capacity suitability for specific urban or cargo tasks will reduce operational risk and support longer asset life. Organizations deploying electric bikes at scale should consider standardized battery and component specifications where possible, while preserving enough flexibility to match different rider profiles and route requirements. Procurement teams should also track regulatory updates in their operating jurisdictions, as changing safety and classification standards can affect model availability, replacement part compatibility, and compliance timelines.
For decision makers seeking deeper granularity on regional demand patterns, segment-level sizing, pricing dynamics, and company-specific competitive benchmarks, the full research report provides detailed quantitative breakdowns and customized strategic guidance. Accessing that level of detail can help narrow strategic options, stress-test sourcing and compliance plans, and prioritize investments in the segments most aligned with specific business objectives.
For detailed analysis of this topic, please visit the official page: Electric Bike Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


