



Vinylphosphonic Acid Market: Why 8.7% CAGR Through 2032 Changes Everything

Vinylphosphonic Acid Market: Strategic Trends and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
The global market for vinylphosphonic acid (VPA) has demonstrated steady expansion over the past half-decade, moving from a valuation of approximately 10.8 million USD in 2020 to an estimated 16.4 million USD in 2025. The trajectory points toward continued growth, with the market projected to reach nearly 29.3 million USD by 2032, reflecting a compound annual growth rate of 8.7 percent. This scale places VPA in the niche specialty chemicals segment, where volume is modest but value addition through application-specific performance is substantial.
At first glance, the numbers suggest uninterrupted expansion. Closer examination reveals a market that is fragmenting around performance thresholds rather than pure capacity. The revenue distribution across grades, applications, and geographies shows that demand is not uniform. High-purity grades dominate share, while coatings and water treatment applications account for the bulk of consumption. Asia Pacific leads regional contribution, reflecting concentrated industrial activity and manufacturing capacity in the region, while mature markets in North America and Europe sustain steady, high-value demand.
PW Consulting
Despite the positive outlook, the sector faces structural challenges that complicate straightforward growth strategies.
Challenge One: Purity Thresholds and Application-Specific Performance
The market is no longer defined by generic chemical supply. Buyers in coatings, corrosion inhibition, and polymer modification increasingly require tight impurity profiles and consistent batch-to-batch performance. The shift from 80 percent grades toward 90 percent and higher purity thresholds is reshaping procurement logic. Suppliers that cannot demonstrate controlled impurity levels risk being relegated to lower-margin segments, while those that can command premium positioning and longer-term contracts.
Challenge Two: Feedstock Volatility and Cost Structure Pressure
Production economics are tightly coupled to phosphorus-based feedstock availability and pricing. Raw material price volatility affects a significant portion of global producers, placing pressure on margin forecasting and inventory planning. Facilities operating with narrow buffers or inflexible procurement arrangements face heightened exposure to cost swings, which in turn influences pricing stability for downstream buyers. This dynamic is particularly acute in regions where feedstock logistics and storage constraints amplify supply variability.
Challenge Three: Regulatory and Logistics Compliance Burden
Hazardous chemical handling introduces a compliance layer that touches production, storage, transportation, and labor practices. A meaningful share of manufacturers report increased compliance costs tied to storage regulations, while logistics providers face restrictions related to chemical transportation safety standards. Elevated labor and safety costs in production facilities further contribute to operating expense pressure. These factors are not marginal; they influence site selection, capacity expansion timing, and the cost of serving distant markets.
Key Drivers Behind Market Evolution
Growth in the VPA market is not accidental. It is being shaped by a set of reinforcing drivers that alter where value is created and how companies compete. Four forces stand out.
Technical Innovation and Purity Engineering
The most visible driver is the push toward higher purity and application-tuned specifications. Industry developments in 2024 and 2025 illustrate this direction. A high-purity 92 percent grade with 14 percent lower impurities was introduced, reflecting a strategic emphasis on impurity control as a differentiator. This matters because even modest reductions in trace contaminants can translate into improved performance in coatings, corrosion inhibition, and polymer modification. Innovation is increasingly less about new molecule discovery and more about precision manufacturing, analytical control, and specification reliability.
Phosphoric Acid Market
Policy and Regulatory Environment
Regulatory expectations around hazardous chemical storage and transportation continue to tighten. Rather than acting as a uniform brake, these requirements are reshaping competitive dynamics. Companies with mature compliance infrastructure, documented safety processes, and regional distribution capacity are better positioned to absorb regulatory friction. Conversely, organizations with fragmented logistics or limited safety investment face higher relative cost and longer time to market. In practice, compliance is becoming a selection criterion for buyers who need predictable supply and reduced operational risk in their own value chains.
Demand-Side Shifts Across Industrial and Specialty Applications
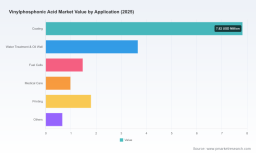
Demand is broadening but not evenly. Coatings remain a core consumption center, driven by performance needs in corrosion resistance, adhesion, and flame retardancy. Water treatment and oil well applications sustain steady demand linked to industrial infrastructure and resource extraction activity. Fuel cells represent a smaller but strategically important segment, where VPA’s functional properties support research and development pathways even if commercial scale remains nascent. Medical care and printing applications contribute niche volumes with distinct purity and handling requirements.
The common thread is not volume growth in isolation but specification sensitivity. Buyers are less interested in generic availability and more focused on whether a grade reliably meets performance thresholds in their process. This shifts purchasing decisions toward suppliers who can evidence consistency, provide technical support, and align product grades with application outcomes.
Supply Chain and Cost Structure Realignment
Supply chain design is becoming a strategic variable. Regional distribution optimization has reduced delivery lead times by 21 percent across three regional distribution centers for one manufacturer, a change that directly affects service levels and inventory planning for downstream customers. At the same time, upstream feedstock fluctuations continue to drive raw material volatility, influencing production economics. Together, these factors are pushing companies to balance proximity, redundancy, and cost efficiency more deliberately. Supply chains that can flex across regions while maintaining specification integrity are gaining a practical advantage.
Competitive Landscape and Leading Strategies
The competitive structure of the VPA market is moderately concentrated, with the top three players accounting for approximately 28.5 percent of revenue and the top five reaching roughly 35.2 percent. This level of concentration indicates that while no single company controls the market, a small group of established players sets much of the pace in specification development, regional coverage, and compliance posture. The rest of the market is dispersed among regional suppliers, specialty producers, and laboratory-focused vendors, creating a multi-layered landscape rather than a simple oligopoly.
Strategic Positioning Among Leading Companies
Several firms illustrate the different ways competition is being structured.
- One German-based producer emphasizes high-purity VPA in both 80 percent and 90 percent grades, with ISO 9001 certification and a portfolio covering monomer and polymer grades for coatings, corrosion inhibition, flame retardancy, and adhesion. Its positioning centers on specification breadth and certified quality control, which supports use across multiple industrial functions.
- A major European chemical company offers specialty VPA grades aimed at polymer modification, coatings, and water treatment. Its advantage lies in the ability to slot VPA into broader specialty chemical portfolios and leverage existing customer relationships in performance materials and water-related applications.
- A Brussels-based supplier provides VPA grades including a formulation for aluminum pretreatment and corrosion inhibition. Its differentiation is application-solving rather than generic supply, targeting a specific industrial pretreatment need with a branded grade.
- A Tokyo-headquartered chemical supplier markets VPA as a high-purity liquid for laboratory and specialty chemical synthesis. Its role is narrower, serving R&D, pilot-scale, and specialty synthesis demand where purity and traceability matter more than bulk cost.
- An Italian manufacturer focuses on VPA for industrial and pharmaceutical applications, indicating a dual-use orientation that spans conventional industrial demand and higher-specification pharmaceutical relevance.
These profiles show that leadership is not defined by a single formula. Some players win through certified quality and grade variety, others through application-specific formulation, and others through purity and technical service for specialized users.
Differentiation Levers and Recent Moves
In a market where volume is constrained and performance requirements are rising, differentiation tends to appear in three levers: purity and impurity control, application reliability, and service responsiveness. Recent industry developments reinforce this pattern. The introduction of a 92 percent high-purity grade with lower impurities reflects a purity-driven differentiation strategy. The reduction in delivery lead times through regional distribution optimization shows a service-level differentiation strategy that improves reliability for buyers. Meanwhile, upgraded polymer modification testing facilities in Asia-Pacific have increased quality assurance throughput by 25 percent, pointing to investment in process verification and application readiness.
These moves matter because they align with how buyers purchase in specialty chemicals. In coatings and water treatment, batch consistency and impurity control affect end-product performance. In polymer modification, testing throughput and quality assurance affect the speed at which new formulations can be validated. In laboratory and specialty synthesis, purity and documentation support downstream reproducibility. Companies that invest in these levers are not simply selling a chemical; they are selling predictable outcomes.
Market Structure Evolution
The market is likely to evolve along two concurrent paths: selective consolidation and continued niche segmentation. Consolidation will probably remain measured rather than aggressive. Because VPA serves multiple applications with different specification needs, scale alone does not guarantee advantage. However, companies that can combine purity control, compliance readiness, and regional distribution capacity are well placed to acquire share from smaller competitors that lack one or more of these capabilities.
At the same time, segmentation will persist. Laboratory-grade supply, industrial bulk grades, and specialized pretreatment or polymer modification grades each carry different buyer expectations, pricing logic, and service requirements. New entrants are most likely to appear in niche positions where a specific grade, regional service advantage, or technical support capability can create a defensible position without requiring dominant scale. The practical outcome is a market that becomes more tiered, with premium specification players, application-focused specialists, and cost-oriented regional suppliers coexisting.
Strategic Outlook for the Next Three to Five Years
Looking ahead to 2032, three trends are likely to shape commercial opportunity and risk.
Trend One: Purity and Specification As control Become the Default Expectation
As higher-purity grades become more widely available and application performance expectations rise, what is considered acceptable purity will shift upward across more use cases. This will compress the middle ground where generic, lower-specification supply once found a home. Suppliers will need to demonstrate tighter impurity control, stronger analytical documentation, and consistent lot performance. The commercial opportunity lies in grades and services that reduce downstream processing variability, especially in coatings and polymer modification, where small quality differences can have outsized effects on end-use performance.
Trend Two: Regional Service Networks Will Matter More Than Raw Proximity
Lead-time reduction, regional distribution optimization, and improved delivery reliability are becoming competitive differentiators. Buyers increasingly value predictable timing and service consistency as much as unit price, particularly when chemical handling and logistics constraints raise the cost of disruption. Companies that build or strengthen regional service networks will be better positioned to capture share in markets where responsiveness and safety compliance are closely linked. This trend also creates opportunities for partnerships that improve storage, transportation, and inventory buffering without requiring every producer to own the full logistics chain.
Trend Three: Regulatory Friction Will Elevate Compliant Operators
Compliance costs tied to hazardous chemical storage, transportation safety standards, and elevated labor and safety requirements are unlikely to recede. Instead, they will continue to separate operators that have built institutional capability from those that have not. Over the next few years, this will influence which producers can expand efficiently, which can serve certain regions reliably, and which can maintain stable pricing. The strategic opportunity is to treat compliance as part of the value proposition rather than a cost to minimize in isolation. Buyers in sensitive applications may prefer suppliers whose safety and transport readiness lower their own operational exposure.
Risks and Uncertainties
Several uncertainties could alter the trajectory. Feedstock volatility remains a persistent risk; if phosphorus-based feedstock supply fluctuations intensify, production economics could tighten and pricing volatility could increase. Regulatory changes could further raise storage and transportation requirements, reshaping cost structures and market access. Demand may also shift faster than expected in certain applications, particularly where alternative materials, formulation changes, or new process technologies reduce reliance on VPA in specific functions. Finally, capacity additions in Asia-Pacific and other regions could alter supply balance, intensifying competition in some segments while creating export opportunities in others.
Actions for Decision-Makers
The VPA market rewards companies that align their strategy with specification sensitivity, service reliability, and compliance readiness. The following actions are most relevant across different roles.
Phosphonate Market
For Manufacturers and Producers
- Prioritize purity engineering and analytical consistency over undifferentiated capacity expansion. In a market where higher-purity grades and lower impurity levels are gaining traction, the ability to document and replicate performance will shape pricing power and customer retention.
- Invest in regional distribution and lead-time reliability. Reducing delivery friction is not just a logistics improvement; it is a commercial differentiator that supports premium positioning and reduces the likelihood of substitution under pressure.
- Design compliance into operations as a competitive asset. Storage, transportation, and labor safety costs are real, but companies that manage them systematically can use reliability and risk reduction as part of their customer value proposition.
For Investors and Strategic Partners
- Focus on business models that combine specification control with service differentiation rather than volume alone. The strongest growth potential lies in companies that can secure long-term relationships through purity, consistency, and responsiveness, especially in coatings, water treatment, and polymer modification.
- Watch for selective consolidation opportunities where regional or specialty players lack the compliance infrastructure, analytical capability, or distribution reach to compete upward. Value creation may come more from capability alignment than from scale expansion.
- Monitor feedstock exposure and regional capacity dynamics. Margins and pricing stability will depend on how well companies manage raw material volatility and adapt to shifting supply balance across regions.
For Procurement and Supply Chain Leaders
- Evaluate suppliers on specification reliability and service consistency as well as price. In applications where impurity levels and batch consistency affect performance, the lowest headline price may not translate into the lowest total cost if variability creates processing risk.
- Build buffer and logistics strategies that account for hazardous chemical transportation constraints. Where safety standards and transport restrictions raise the cost of disruption, regional distribution capability and documented handling practices can reduce supply risk.
- Align grade selection with application outcomes. The choice between 80 percent, 90 percent, and higher-purity grades should be tied to actual performance requirements and downstream process sensitivity, not just inventory convenience.
The commercial dynamics of vinylphosphonic acid are increasingly defined by precision, service, and compliance rather than by bulk commodity logic. For companies operating in coatings, water treatment, polymer modification, fuel cells, medical care, printing, and related specialty segments, the window to strengthen positioning is now, before specification expectations and regulatory expectations become even more firmly entrenched. Detailed segmentation data, regional breakdowns, grade-level dynamics, and customized scenario analysis are available in the full PW Consulting report on the Vinylphosphonic Acid Market, which provides the deeper quantitative and strategic detail needed for planning beyond high-level trends.
For detailed analysis of this topic, please visit the official page: Vinylphosphonic Acid Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


