



Histidine Market Outlook 2026–2032: The Real Drivers Behind a 6.8% CAGR

The Histidine Market at an Inflection Point: Strategic Trends and Commercial Opportunities
The global market for L-Histidine has entered a phase of steady, compounding expansion. From 2020 through 2032, the sector is projected to advance at a compound annual growth rate of 6.8 percent, with market value climbing from roughly $163 million to over $338 million over the forecast horizon. The trajectory is not a straight line: a contraction in 2022 underscored the fragility of supply chains, while post-pandemic recovery and downstream demand acceleration pushed the market past $215 million in 2025. This growth is anchored in biology as much as economics. Histidine’s role as an essential amino acid, a buffering agent, and a precursor in specialty formulations makes it indispensable across pharmaceuticals, animal nutrition, food processing, and life sciences research. Yet the market’s maturity is uneven, and the companies that will capture disproportionate value are those that understand where production is shifting, where regulation is tightening, and where end-use demand is evolving faster than capacity.
L-Alanine Market
Market Structure and Core Challenges
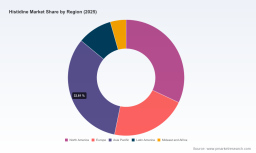
The histidine market is characterized by moderate fragmentation and a production base that leans heavily on two manufacturing paradigms. Fermentation-derived routes dominate the volume conversation, supported by steady gains in yield optimization and strain engineering. Hydrolysis-based production remains relevant where specific purity profiles or legacy supply arrangements dictate. The regional distribution of revenue reflects a geography in transition. Developed markets in North America and Europe continue to anchor high-value, regulated end markets, while Asia Pacific has emerged as both the largest consumption region and a critical production hub. Latin America and the Middle East and Africa contribute smaller but structurally important flows, often tied to feed-grade applications and emerging pharmaceutical manufacturing.
Against this backdrop, three structural challenges define the current operating environment.
PW Consulting Health Care Research Center
- Purity and regulatory divergence across applications. Pharmaceutical and biopharmaceutical demand requires GMP-grade, low-endotoxin, and low-metal specifications that are expensive to validate and qualify. Feed and food-grade applications operate on thinner margins and more price-sensitive procurement cycles. The gap between these tiers creates a bifurcated market where the same molecule carries radically different cost structures, qualification timelines, and competitive moats.
- Supply chain concentration and verification risk. A handful of large producers accounts for a modest share of total revenue, which means the market is not dominated by a single oligopoly, but it is also not broadly commoditized. Semi-concentrated supply, combined with geographic clustering of fermentation capacity, leaves downstream buyers exposed to qualification bottlenecks, logistics disruption, and batch-to-batch consistency concerns.
- Input volatility and the cost of biological production. Fermentation economics are influenced by substrate pricing, water and energy intensity, strain performance, and downstream purification costs. Hydrolysis routes face their own raw material dependencies. When energy prices or feedstock costs move sharply, margin discipline becomes a differentiator rather than a baseline expectation.
Key Drivers Reshaping the Market
The 6.8 percent growth rate is not merely an extrapolation of historical demand. It reflects a convergence of technical, regulatory, and commercial forces that are changing how histidine is produced, qualified, and deployed.
Technology and Process Innovation
Process innovation is the most direct lever for expanding margins and unlocking new use cases. In fermentation, the competitive frontier has shifted from basic titer improvements to integrated strain design, reduced impurity profiles, and more efficient downstream recovery. The practical impact is significant: higher-purity outputs lower the burden of endotoxin and metal removal, which in turn shortens qualification cycles for biopharmaceutical customers. For hydrolysis-based producers, the opportunity lies less in volume leadership and more in precise specification control where specialty grades command premium pricing.
This dynamic is visible in recent strategic moves to combine complementary capabilities. A notable example is the 2025 partnership between a major fermentation-based producer and a Chinese chemical supplier to co-develop and secure global supply of L-Histidine HCl monohydrate, explicitly aimed at expanding fermentation-derived production capacity. The significance of this move is not just incremental capacity. It signals a deliberate effort to align biological production expertise with regional supply reach, reducing lead-time risk and reinforcing supply continuity for regulated end markets. In an environment where qualification and consistency are as valuable as price, partnerships that bridge process technology and distribution are becoming a strategic necessity rather than an optional synergy.
Policy and Regulatory Environment
Regulation is quietly reshaping histidine’s cost of entry and the geography of trade. For pharmaceutical and biopharma buyers, GMP compliance, traceability, and impurity control are non-negotiable. For industrial and feed users, the regulatory burden differs, but documentation, residue limits, and regional approval pathways still shape sourcing decisions. The effect on competition is twofold: regulatory readiness functions as a barrier that rewards established, well-documented suppliers, while new entrants must invest not only in capacity but in quality systems and audit readiness.
On the trade side, export control dynamics add another layer of complexity. In early 2026, the U.S. Federal Register noted that China suspended export controls on six critical dual-use items until November 2026, with potential implications for trade in chemical intermediates used in amino acid production. Even where the direct link to histidine is indirect, the broader signal is important: the availability and pricing of intermediates, precursor chemicals, and specialty inputs can shift with regulatory calendars, not just market fundamentals. Producers and buyers that map their supply chains against such policy windows are better positioned to avoid surprise cost spikes or sourcing gaps.
Demand-Side Shifts
End-use demand is expanding along two converging paths. The first is the continued growth of biopharmaceutical manufacturing and cell-based processes, where histidine and its salts serve as excipients, buffering components, and media constituents. As biologics, cell therapies, and advanced manufacturing formats scale, the volume of high-purity amino acids required per facility increases, raising the stakes for suppliers that can deliver consistent, low-endotoxin material at commercial scale.
The second path is more traditional but structurally durable: animal feed and food-grade applications. In feed, histidine availability supports formulation flexibility and animal performance objectives, while in food and supplements it serves functional and nutritional roles. These segments are less glamorous than biopharma, but they contribute steady volume and can act as absorbers during periods when pharmaceutical demand is qualification-constrained. Importantly, the demand mix is not uniform across regions. Where animal production intensifies and where food processing modernizes, histidine consumption grows in ways that reward suppliers with reliable feed-grade and food-grade streams as well as the capability to serve regulated markets when opportunities arise.
Supply Chain and Cost Structure Evolution
The market’s cost structure is increasingly shaped by the distance between production and qualification. Fermentation scale brings advantages in unit cost, but it does not automatically solve purity, endotoxin control, or documentation. As a result, the most resilient supply chains are those that integrate fermentation output with disciplined downstream processing and strong quality systems. This integration reduces rework, shortens batch release timelines, and improves predictability for buyers who are themselves managing tight production schedules.
Logistics and geographic concentration also matter more than they appear to on a spreadsheet. A supply base that is efficient but geographically narrow can create hidden exposure: port delays, regional fuel cost fluctuations, and regulatory checks can each erode service levels. The practical response is diversification of qualified sources combined with audited quality agreements. Buyers are increasingly treating qualification as a portfolio decision, balancing cost against continuity, and favoring suppliers that can demonstrate both scale and verifiable control over critical quality attributes.
Competitive Landscape and Leading Strategies
The competitive set in histidine is geographically diverse and strategically differentiated. Japanese producers have built strong reputations in fermentation-based, high-purity supplies for pharmaceutical and biopharmaceutical use, with product profiles explicitly oriented toward cell culture media, parenteral and enteral nutrition, and biopharmaceutical applications. A leading German specialty supplier has emphasized highly purified histidine for biopharma, amino acid derivatives, and GMP-grade applications, reinforcing a positioning around purity and compliance. Another major European life sciences player has extended its brand into histidine for laboratory and biopharma use, leveraging established quality systems and broad distribution networks.
Lysine Market
In the United States, a supplier focused on high-purity, low-endotoxin, low-metal material has carved a defensible niche in biopharmaceutical formulations, where impurity control and specification consistency directly affect customer outcomes. In Asia, a Korean fermentation producer supplies histidine base for medicines, food supplements, and animal feed, reflecting a model that spans both regulated and lower-margin volume applications. China-based chemical suppliers remain active in pharmaceutical and industrial streams, often competing on responsiveness and cost while navigating the same quality expectations as global buyers.
Several patterns stand out in how leading players are positioning themselves.
- Segment specialization as a moat. The most defensible positions are not simply about volume. They are about owning a specification tier that matters to a specific customer class. High-purity, low-endotoxin material creates switching costs because re-qualification is expensive and time-consuming. Feed-grade and food-grade leadership, by contrast, requires scale, cost discipline, and reliable delivery. Few companies optimize both tiers equally, which is why specialization remains a rational strategy.
- Capacity expansion tied to partnership, not just CAPEX. The recent co-development partnership to expand fermentation-derived supply illustrates a broader trend: companies are extending reach through alliances that combine process know-how, regional access, and supply security. This reduces the capital intensity of standalone expansion while improving resilience.
- Quality systems as commercial infrastructure. In regulated segments, quality documentation, audit readiness, and impurity control are no longer back-office functions. They are commercial differentiators that determine whether a supplier is invited into a qualified vendor list in the first place.
The market structure suggests continued evolution rather than abrupt consolidation. Because concentration is moderate, the field remains open to capable new entrants with strong process or quality advantages, but the qualification barrier protects incumbents who have already invested in relationships and documentation. Over the next few years, the most likely shifts are selective integration around capability gaps—partnerships, co-development, and regional supply reinforcement—rather than broad-based mergers. At the same time, buyers are likely to keep qualifying multiple sources where possible, balancing cost and continuity, which will reinforce the value of differentiated quality and reliable service.
Future Trends and Commercial Implications
Looking ahead three to five years, three trends are likely to shape where value migrates within the histidine market.
First, the premium on high-purity, biopharma-ready material will keep rising. As biologics manufacturing and advanced cell-based processes scale, demand for low-endotoxin, low-metal, well-documented histidine will grow faster than the general market. The commercial opportunity lies in building or acquiring the process control and quality systems that make that purity reproducible at scale. Suppliers that can compress qualification timelines and reduce variability will be able to command pricing power even in an otherwise competitive category.
Second, production geography will keep rebalancing around cost, continuity, and policy. Asia remains a central production axis, but buyers are likely to seek qualified alternatives and redundancy where possible. Trade and export-control dynamics may also influence intermediate availability, which will make forward inventory planning and supplier mapping more important. Companies that treat geography as a risk variable—not just a cost variable—will be better prepared to maintain service during disruption.
Third, segmentation will sharpen rather than blur. The gap between regulated pharmaceutical grades and feed/food grades is structural, and the strategies that succeed in one segment do not automatically transfer to the other. That creates both risk and opportunity. Manufacturers that can selectively bridge high-margin, high-specification demand with stable volume streams will capture more resilient economics than those forced to compete purely on price in undifferentiated segments.
Each trend carries uncertainty. Regulatory expectations may tighten further in certain jurisdictions, raising the cost of entry for new suppliers. Energy and feedstock volatility can compress margins for fermentation producers that lack pricing power or hedging discipline. And while partnerships can extend reach, they also introduce coordination risk, especially when co-developing capacity across regions with different regulatory environments and operating norms. The most resilient strategies will account for these variables explicitly rather than assuming smooth demand growth will absorb operational shocks.
Actionable Guidance for Decision Makers
For manufacturers, the strategic question is where to invest next. If the portfolio already leans toward feed or food grades, the highest-return move may be disciplined expansion of purification capability that opens a credible path into pharmaceutical or biopharma-adjacent specifications. If the portfolio already serves regulated markets, the priority is likely to reinforce supply continuity through partnerships or regional capacity that reduces lead-time exposure, while maintaining rigorous impurity and endotoxin control. In both cases, qualification readiness should be treated as part of the product, not a separate compliance exercise.
For investors, the opportunity is less about total market size than about the distribution of value within it. Segments that require high purity, low variability, and documented compliance tend to support more durable margins and stronger customer stickiness. Capital should be assessed against the ability to scale process control, reduce batch failure and rework, and qualify sources in multiple geographies where appropriate. Projects that rely on undifferentiated volume growth without a quality or continuity advantage are more exposed to margin compression and competitive entry.
For procurement and supply chain leaders, the practical priority is to convert qualification from a one-time gate into an ongoing risk-management process. That means evaluating suppliers not only on price and lead time, but on impurity profiles, endotoxin and metal control, documentation depth, and the resilience of their production geography. Multi-sourcing qualified alternatives, even where one supplier dominates volume, can reduce exposure to disruption. Aligning inventory planning with potential policy windows and trade dynamics—such as the recent suspension of certain export controls affecting chemical intermediates—can also prevent avoidable cost shocks.
For organizations evaluating where to focus next, the histidine market rewards precision. The growth rate is healthy, but the real differentiation comes from understanding which specification tiers are expanding fastest, where supply is becoming more or less concentrated, and how regulatory and trade dynamics will alter the cost of intermediates and finished material. A detailed segmentation view—by production method, application tier, end-market requirements, and regional qualification pathways—can sharpen capacity planning, sourcing strategy, and investment prioritization in ways that aggregate market figures cannot. For teams that need segment-level sizing, region-specific supply analysis, and tailored scenarios for qualifying new sources or expanding into higher-purity grades, the full research report provides the structured data and actionable detail to support those decisions.
For detailed analysis of this topic, please visit the official page: Histidine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


