



Driving Recorder Market Set for 8.5% CAGR Growth Through 2032: Strategic Shifts Redefining Profitability

The Driving Recorder Market: Strategic Shifts and Commercial Opportunities from 2025 to 2032
The global market for driving recorders, commonly known as car dashcams, has grown from approximately US$163 million in 2020 to an estimated US$215 million in 2025. This trajectory reflects a compound annual growth rate of roughly 8.5 percent through 2032, when revenue is projected to exceed US$344 million. Behind these figures lies a sector undergoing structural transformation: what began as a consumer safety accessory is evolving into a data-rich, connectivity-enabled platform that intersects fleet management, insurance telematics, and advanced driver-assistance systems.
The market is no longer defined solely by onboard video capture. Multi-lens configurations, artificial intelligence–based event detection, and cloud-synchronized storage are reshaping product expectations across passenger cars, commercial fleets, and specialized applications. At the same time, supply chain friction, memory cost volatility, and shifting regulatory frameworks are introducing both constraints and differentiation opportunities. The following analysis maps the forces reshaping the driving recorder landscape and outlines where strategic value is likely to accrue over the next three to five years.
Market Snapshot and Core Challenges Facing the Industry
Revenue across the global driving recorder market reached US$215 million in 2025 and is projected to expand to US$344 million by 2032, supported by an 8.5 percent CAGR over the 2026–2032 period. The segment has demonstrated resilience through recent macroeconomic volatility, with year-over-year growth resuming after a brief contraction in 2022.
PW Consulting
Two structural challenges are defining the near-term operating environment. First, cost pressure from memory and semiconductor inputs is compressing margins for hardware-first players. Memory chip prices used in dashcams have risen 80 to 90 percent since late 2025, driven by surging AI data storage demand and allocation-only procurement practices among leading suppliers. Semiconductor lead times have been climbing for a full year and spiked dramatically in early 2026, with top-component lead times reaching 40 weeks. These dynamics create inventory planning complexity, lengthen time-to-market for new model iterations, and favor companies with stronger supplier relationships or differentiated bill-of-materials strategies.
Second, the market is navigating a maturity inflection in the consumer segment while simultaneously opening a higher-value pathway in commercial and connected-vehicle applications. Single-lens dashcams continue to anchor a substantial share of revenue, but multi-lens and AI-enabled configurations are expanding as fleet operators, insurers, and OEMs seek richer data sets. The strategic question is no longer whether to add connectivity or analytics, but how to do so without triggering a margin squeeze from raw-material inflation or exposing the product to cyber and data-privacy vulnerabilities that accompany cloud-based architectures.
A third, more geopolitical challenge is emerging around export controls and hardware provenance. Policy activity, including the April 2026 House Foreign Affairs Committee markup of national security-focused bills such as the Stop Stealing Our Chips Act, signals a more active regulatory posture around semiconductor and electronics supply chains. For manufacturers that rely on cross-border component sourcing or assemble in specialized hubs, this trend introduces planning uncertainty and may accelerate regional sourcing shifts or dual-supplier strategies.
Key Drivers Shaping the Driving Recorder Market
Technological Innovation and the Shift Toward AI-Enabled Recording
The most consequential technological shift is the migration from passive recording to intelligent event detection and post-incident analytics. Recent product introductions illustrate this direction. In April 2026, Thinkware introduced its flagship U3000 dash cam with 4K/2K resolution, built-in front and rear RADAR sensors, Sony STARVIS 2 image sensors, ADAS alerts, and mobile-app connectivity. In March 2026, BlackVue released the DR770X Box triple-camera cloud-compatible system with a separate secure recording unit designed for enhanced parking surveillance in fleet applications. These launches reflect a broader industry move toward higher resolution, sensor fusion, and dedicated storage architectures that preserve evidence even when primary systems are offline.
The practical implication for manufacturers and fleet operators is that video is increasingly treated as one input within a larger safety and compliance data stack. AI-based event classification, driver behavior scoring, and voice alerts are reducing reliance on manual footage review. Geotab’s September 2025 launch of the GO Focus Plus AI dashcam, which incorporates voice alerts and a video intelligence platform reported to reduce risky driving behaviors by up to 95 percent in fleet pilots, is an early indicator of how analytics can translate directly into measurable safety outcomes. For companies evaluating product roadmaps, the opportunity lies in pairing reliable image capture with differentiated analytics, low-latency alerts, and integration-friendly data outputs.
Policy and Regulatory Dynamics Supporting Adoption
Regulatory and compliance trajectories are creating tailwinds for higher-quality recording solutions, particularly in commercial and fleet environments. Although the specific content and timing of regulations vary by jurisdiction, the broader direction favors evidence-grade documentation, driver safety accountability, and telematics integration. At the same time, policy activity around semiconductors and electronics adds a layer of operational complexity. The April 2026 markup of export-control-related bills and ongoing scrutiny of chip supply chains suggest that companies should treat supply chain resilience and component traceability as strategic priorities rather than back-office concerns.
The commercial opportunity here is twofold. First, fleet operators and insurance-linked programs increasingly prefer dashcam solutions that can demonstrate consistent functionality, clean data handling, and integration with existing compliance workflows. Second, OEMs and tier-one suppliers are exploring ways to embed recording capabilities more tightly into vehicle architectures. In February 2025, Magna International advanced next-generation front camera systems for OEMs that integrate higher-resolution imaging with onboard video recording capabilities within a single ADAS module. This type of integration suggests a future in which aftermarket and OEM recording functions converge, expanding the addressable opportunity while also raising the competitive bar for standalone hardware.
Demand-Side Evolution Across Passenger Cars and Commercial Fleets
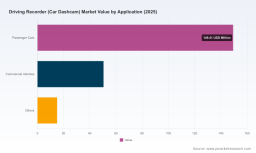
Consumer demand continues to be driven by safety concerns, insurance incentives, and a growing expectation that vehicles should document incidents clearly and reliably. Passenger cars remain the largest application category, reflecting broad adoption of dashcams as both a protection tool and a driver-assistance aid. However, the most dynamic growth is occurring where recording intersects with operational value: fleet safety programs, driver coaching, claim verification, and parking-mode protection.
Commercial vehicles represent a smaller but strategically important segment. Fleet operators are drawn to multi-channel systems and cloud-compatible architectures that support centralized monitoring, evidence preservation, and integration with broader telematics platforms. The appeal of separate secure recording units for parking surveillance, as seen in recent BlackVue fleet-oriented offerings, underscores a practical need: commercial users want continuity of protection when vehicles are unattended, plus administrative simplicity when incidents occur. As parking-mode features and ADAS alerts become standard expectations in premium segments, products that fail to offer robust post-event capture or seamless mobile connectivity risk losing share in higher-margin applications.
Supply Chain and Cost Structure Pressures
The cost environment is a defining constraint for the sector. The sharp rise in memory chip prices and extended semiconductor lead times mean that hardware planners must balance performance upgrades against input-cost volatility. Suppliers and integrators that can secure allocation, diversify sources, or design around memory-intensive architectures will have an advantage in maintaining price competitiveness. At the same time, the trend reinforces the case for software and service margins, subscription-linked features, and analytics offerings that can generate recurring revenue independent of component cost cycles.
This dynamic also favors consolidation and partnership. Companies with established supplier relationships, regional manufacturing flexibility, or strong logistics capabilities are better positioned to manage lead-time volatility. Conversely, smaller hardware-only entrants may find it increasingly difficult to compete on both speed-to-market and cost discipline without a clear software, integration, or brand differentiation.
Competitive Landscape and Leading Strategies
The driving recorder market remains moderately fragmented, with five companies accounting for roughly 48 percent of revenue and three firms representing about 32 percent. This concentration suggests that leading players have meaningful brand and distribution advantages, yet the sector still leaves room for specialized entrants that address fleet, premium consumer, or OEM-adjacent use cases.
Dashboard Camera Market
Viofo, based in Shenzhen, has built a reputation around professional-grade dash cameras featuring Sony STARVIS 2 IMX sensors, 4K ultra-high-definition recording, and advanced multi-channel recording. Its positioning reflects a clear focus on image quality and multi-channel capture, which appeals to users who prioritize evidence-grade footage. BlackVue, headquartered in Seongnam-si, South Korea, competes in the premium segment with 4K UHD dash cams, cloud features, parking mode protection, and triple-camera cloud-compatible systems. BlackVue’s strategy leans toward connectivity and continuous protection, particularly in scenarios where vehicles are parked and unattended.
70mai, based in Shanghai, has positioned itself as an innovator in smart car electronics with intelligent dash cams that combine AI features, 4K recording, and safety enhancements. Its approach emphasizes intelligent functionality and broader vehicle-electronics integration, aligning with consumer expectations for connected devices. In North America, Garmin contributes an automotive portfolio that includes wireless backup cameras, voice-controlled models, and GPS integration, giving it an advantage in ecosystems where navigation and vehicle electronics are purchased together. Thinkware, based in Coquitlam, British Columbia, is recognized as a global leader in premium dash cams with 4K UHD, AI parking surveillance, ADAS alerts, and mobile-app connectivity. Thinkware’s advantage lies in bundling high-resolution recording with radar-based sensing and app-level interaction, which supports both consumer and fleet-oriented positioning.
Vantrue operates in the United States with a premium high-end lineup focused on 4K ultra-HD recording and multi-channel options for automobile security, reinforcing a niche for users who want comprehensive coverage in a single device. Nextbase, based in the United Kingdom, has built an award-winning portfolio around high-resolution recording, fleet-optimized solutions, and proven safety features, giving it a strong narrative in markets where fleet safety and image quality are deciding factors. Pittasoft, also headquartered in Seongnam-si, South Korea, is associated with BlackVue premium dash cams and emphasized capabilities in cloud security, parking surveillance, and advanced video analytics, underscoring how software and data-management value can complement hardware.
Recent developments suggest the competitive edge is shifting toward integration and analytics. Geotab’s September 2025 launch of the GO Focus Plus AI dashcam with voice alerts and a video intelligence platform, which reportedly cut risky driving behaviors by up to 95 percent in fleet pilots, highlights how behavior-reduction messaging and video analytics can become differentiating value propositions in fleet environments. Thinkware’s April 2026 U3000 launch and BlackVue’s March 2026 DR770X Box release reinforce a premiumization trend in which multi-camera setups, secure storage units, and sensor-enhanced ADAS alerts are becoming standard features in higher-tier products. Magna’s February 2025 work on OEM-integrated front camera systems with onboard video recording indicates that the boundary between aftermarket and factory-installed recording is beginning to blur, a development that could reshape channel dynamics over time.
The strategic takeaway is that winning products are increasingly defined by more than resolution or channel count. Differentiation is coming from cloud compatibility, parking-mode resilience, ADAS-linked alerts, behavior analytics, and integration with fleet or telematics platforms. Companies that can combine reliable capture with actionable data outputs and robust supply-chain execution are best positioned to defend margins and capture share in the next phase of growth.
Forward-Looking Trends and Commercial Implications
Trend 1: AI and Video Intelligence Become Baseline Expectations
Over the next three to five years, AI-based detection and video intelligence are likely to move from premium differentiators to baseline expectations, especially in commercial and fleet applications. Voice alerts, event classification, and behavior scoring will increasingly be expected alongside high-resolution capture. This shift creates opportunities for products that can translate video into measurable safety improvements and for service models that help operators act on footage without large manual review teams. It also raises the importance of algorithm reliability, false-positive management, and data governance, since poorly tuned analytics can erode trust quickly.
Trend 2: Convergence of Aftermarket and OEM-Embedded Recording
The integration of recording capabilities into ADAS-related modules, as signaled by Magna’s next-generation front camera systems, points toward a future where onboard recording is more tightly embedded in vehicle architecture. This convergence could expand adoption through factory channels while increasing competition for standalone aftermarket devices. Manufacturers that can offer complementary aftermarket products, retrofit solutions, or strong integration interfaces may be able to serve customers who choose either path. The risk is that purely hardware-focused aftermarket products lose relevance if OEMs make recording a standard part of the vehicle package.
Worldwide Car Video Monitors Market
Trend 3: Supply-Chain Resilience and Component Cost Management as Strategic Capabilities
With memory chip prices up significantly since late 2025 and semiconductor lead times extending toward 40 weeks for key components, supply-chain management is becoming a strategic capability rather than a procurement exercise. Companies that diversify memory sourcing, optimize storage architectures, and build allocation resilience will be better able to sustain product launches and pricing. There is also an opportunity to shift some value toward software, cloud analytics, and subscription-linked features that are less exposed to component cost swings. The primary risk is that cost pressure forces broad price increases before consumers or fleet buyers are ready to absorb them, potentially slowing volume growth in price-sensitive segments.
Strategic Recommendations for Decision-Makers
For Manufacturers and Product Leaders
- Prioritize sensor quality, multi-channel reliability, and ADAS-linked alert features as core product pillars, since these are becoming table stakes in premium consumer and fleet segments.
- Invest in analytics, cloud compatibility, and parking-mode resilience that deliver measurable operational value, rather than competing only on resolution or channel count.
- Strengthen memory and semiconductor sourcing strategies now, including supplier diversification and storage-architecture optimization, to reduce exposure to lead-time spikes and component-price inflation.
- Prepare for OEM adjacency by designing products that can complement factory-installed recording or serve retrofit and aftermarket niches with clear differentiation.
For Investors and Capital Allocators
- Look for companies that have credible analytics roadmaps, cloud integration capabilities, and evidence of fleet or insurance-linked demand, since these areas are where margin expansion and recurring revenue are most plausible.
- Evaluate supply-chain resilience as part of the investment thesis, especially for hardware-heavy models that may face margin volatility from memory and semiconductor costs.
- Monitor convergence signals between aftermarket and OEM-embedded recording, as these can reshape channel economics, competitive moats, and long-term growth trajectories.
For Fleet Operators, Procurement Teams, and Insurance-Aligned Buyers
- Prioritize solutions that combine high-quality capture with cloud-synchronized storage, parking-mode protection, and ADAS alerts, since these features reduce risk exposure and simplify incident response.
- Evaluate integration with existing telematics or safety platforms before procurement, because the operational value of a dashcam often depends on how easily footage and analytics can be used in daily workflows.
- Consider total cost of ownership in the context of memory and hardware cost trends, and weigh products that offer differentiated analytics or behavior-reduction features against straightforward recording-only options.
The driving recorder market is moving beyond simple onboard video capture into a space where image quality, AI analytics, cloud connectivity, and supply-chain discipline jointly determine competitive outcomes. For companies and investors seeking to navigate this shift with confidence, detailed segmentation data, company-level revenue estimates, and region-specific demand dynamics can sharpen planning considerably. PW Consulting maintains a dedicated research practice covering this sector, and the full Driving Recorder market report provides deeper breakdowns and customized scenarios for manufacturers, investors, and procurement teams evaluating entry, expansion, or sourcing decisions.
For detailed analysis of this topic, please visit the official page: Driving Recorder (Car Dashcam) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


