



Organic Elemental Analyzer Market: What the 6.98% 2032 Growth Path Really Means

Strategic Shifts and Commercial Opportunities in the Organic Elemental Analyzer Market
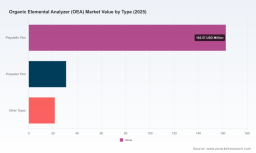
The global market for Organic Elemental Analyzers (OEA) has entered a phase of sustained, structurally driven expansion. Valued at approximately USD 215.0 million in 2025, the sector has demonstrated consistent upward momentum over the past half-decade, building from a baseline of USD 163.15 million in 2020. The trajectory is projected to accelerate through the forecast horizon, reaching an estimated USD 344.8 million by 2032. This translates to a compound annual growth rate of 6.98 percent, a figure that places the market above the broader analytical instrumentation sector average. Growth is not merely cyclical; it reflects a fundamental recalibration in how laboratories, manufacturers, and regulatory bodies approach material characterization, quality assurance, and environmental compliance.
The expansion narrative, however, cannot be reduced to aggregate numbers. The market is navigating a complex landscape where technological capabilities, supply chain realities, and end-user expectations are intersecting. Below the headline growth rate lies a competitive environment shaped by consolidation pressures, regional demand divergence, and rapid innovation in combustion and detection methodologies. Stakeholders who understand the underlying mechanics of this expansion will be better positioned to allocate capital, design product roadmaps, and negotiate procurement strategies with confidence.
Market Architecture and the Friction Points Defining the Next Cycle
The current market architecture is characterized by a moderate degree of concentration. The three largest players collectively account for roughly 24.6 percent of total revenue, while the top five firms control approximately 26.2 percent. This distribution suggests a market that remains sufficiently fragmented to allow specialized entrants and regional champions to compete on niche capabilities, yet consolidated enough that incumbents hold meaningful pricing power, distribution leverage, and service network advantages. The gap between the top three and top five is notably narrow, indicating that mid-tier competitors are increasingly closing the performance and commercial coverage gap through targeted product development rather than broad-spectrum expansion.
Several structural challenges are simultaneously acting as inflection points. First, the cost and complexity of analytical workflows continue to pressure end-user budgets, particularly in mid-sized laboratories and contract research organizations operating under tight capital expenditure constraints. High-caliber OEA systems require robust sample preparation protocols, calibrated reference materials, and specialized maintenance routines. When total cost of ownership rises faster than budget allocations, procurement cycles elongate and buyers increasingly scrutinize return on investment at the application level rather than the instrument level.
Total Organic Carbon (TOC) Analyzer Market
Second, the industry is grappling with a skills and operational expertise gap. Modern elemental analyzers integrate sophisticated combustion chambers, automated gas handling, and advanced detection optics. While automation has reduced manual intervention, operators still require training in method validation, baseline drift management, and cross-application method transfer. Institutions that cannot staff adequately or upskill existing personnel face throughput bottlenecks, which in turn dampen the perceived utility of higher-throughput systems and slow replacement cycles for legacy assets.
Third, supply chain volatility for high-purity reagents, specialized catalysts, and precision-machined components has introduced uncertainty into both manufacturing lead times and service-level commitments. Even as logistics networks normalize following earlier disruptions, the underlying dependency on tightly specified consumables and calibration standards means that any regional constraint or pricing shift can ripple through deployment schedules and affect near-term revenue recognition for manufacturers.
These challenges are not merely obstacles; they are forcing functions that are reshaping competitive priorities. Manufacturers that can decouple performance from consumables consumption, streamline software-driven calibration, and offer application-specific validation packages are gaining traction. Buyers that internalize total cost of ownership calculations and align instrument selection with validated workflow requirements are reducing unexpected downtime and improving analytical consistency across campaigns.
Key Drivers Accelerating Market Trajectory
Technical Innovation as the Primary Growth Engine
The most consequential driver of market expansion is the steady progression of combustion and detection technologies. Contemporary OEA platforms increasingly deliver simultaneous determination of carbon, hydrogen, nitrogen, sulfur, and oxygen within unified analytical runs, reducing the need for sequential testing and minimizing sample consumption. This capability is particularly valuable in environments where throughput, repeatability, and sample scarcity intersect. High-throughput modules, automated sample introduction, and software-assisted method selection have lowered the operational burden for routine analyses while expanding the range of matrices that can be processed reliably.
A notable example of this direction is found in the FlashSmart Elemental Analyzer and the FLASH 2000 Series, which are engineered to provide simultaneous CHNS/O determination tailored for pharmaceutical workflows and analytical laboratories. These systems illustrate how modern architectures prioritize streamlined sample handling, integrated data processing, and robust baseline stability to meet the documentation and reproducibility standards expected in regulated environments. By compressing the time between sample loading and validated output, such platforms directly address the throughput and consistency pressures that laboratories face when scaling analytical operations.
Policy and Regulatory Mandates Expanding the Addressable Base
Regulatory frameworks and compliance requirements continue to broaden the applications for which elemental analysis is indispensable. In pharmaceutical and fine chemical manufacturing, stringent impurity profiling, identity confirmation, and batch consistency checks depend on reliable carbon, nitrogen, and sulfur determinations. Environmental testing and waste characterization protocols similarly require accurate organic composition data to support reporting, risk assessment, and remediation planning. As jurisdictions tighten reporting standards and enforcement diligence, laboratories and industrial quality teams are compelled to formalize their analytical capabilities rather than rely on ad hoc testing or outsourced services.
This regulatory tailwind does not simply increase volume; it changes the purchasing calculus. Buyers seek instruments with traceable method documentation, validated performance characteristics, and service support that can withstand audit scrutiny. The compliance dimension elevates the importance of vendor reputation, application support, and long-term availability of consumables and software updates. In many procurement scenarios, the decision to standardize on a particular platform is as much about risk management and audit readiness as it is about analytical performance.
Demand-Side Shifts in Quality Assurance and Advanced Materials
Demand patterns are evolving as end-users place greater emphasis on predictive quality and material consistency. Semiconductor-related manufacturing and advanced packaging workflows, for example, require rigorous control over organic residues, process contaminants, and material purity indicators. While the OEA category spans diverse end uses, the semiconductor wafer manufacturing segment has emerged as a substantial demand driver, reflecting the industry's need for precise characterization of materials that influence device yield and reliability. IC packaging activities also contribute meaningfully, as miniaturization and heterogeneous integration increase the sensitivity of final device performance to surface chemistry and organic contamination profiles.
Beyond electronics, food, feed, and organic matrix testing remain significant application areas where carbon, hydrogen, nitrogen, and protein determinations underpin nutritional labeling, authenticity verification, and quality control. The 828 Series macro combustion analyzer, focused on carbon, hydrogen, nitrogen, and protein in food, feeds, and organic matrices, reflects how instrument design is being adapted to application-specific throughput and sample-scale requirements. When analytical platforms align closely with the sample type, throughput expectations, and reporting formats of a given industry, adoption friction decreases and replacement cycles accelerate.
Supply Chain and Cost Structure Dynamics
Cost structures are being reshaped by the interplay between instrument capability, consumables intensity, and regional service economics. Manufacturers are increasingly differentiating on the basis of how efficiently their systems consume reagents and reference materials, how predictable maintenance intervals are, and how quickly field service can restore operational status. In parallel, regional service density and local technical support availability have become decisive factors for buyers in markets where downtime carries high cost. Companies that build or partner into responsive service networks, localize consumable supply where feasible, and provide remote diagnostics and software-based troubleshooting are strengthening their commercial resilience.
The vario EL cube platform, which offers simultaneous CHNS with oxygen, chlorine, and total inorganic carbon determination across micro to macro sample ranges, demonstrates how expanded parameter coverage and flexible sample handling can command premium positioning. By consolidating multiple analytical objectives into a single workflow, such systems reduce fragmentation in laboratory inventories and simplify method management. This value proposition is especially relevant for organizations that seek to standardize instrumentation across multiple sites or consolidate legacy platforms onto a modern, software-integrated architecture.
Competitive Landscape and the Logic of Differentiation
Incumbent Positioning and Capability Mapping
The competitive field is anchored by a group of established manufacturers with distinct strategic orientations. Thermo Fisher Scientific, based in Waltham, Massachusetts, competes through integrated analytical portfolios that emphasize simultaneous CHNS/O determination and laboratory workflow compatibility, particularly in pharmaceutical and analytical lab settings. The company's positioning leverages broad commercial coverage, established service infrastructure, and the ability to embed elemental analysis into wider laboratory information and quality management ecosystems.
LECO Corporation, headquartered in St. Joseph, Michigan, has built recognition around macro combustion analysis for carbon, hydrogen, nitrogen, and protein applications in food, feeds, and organic matrices. Its strategic emphasis reflects deep application focus, robust engineering tradition in combustion analysis, and a commercial approach that prioritizes method reliability and throughput for high-volume routine testing. This application specialization enables the firm to serve buyers whose primary concern is consistency across large sample populations rather than maximally broad elemental coverage.
Elementar Analysensysteme, located in Langenselbold, Germany, addresses the market with platforms that combine simultaneous CHNS capability with oxygen, chlorine, and total inorganic carbon determination for micro to macro sample analysis. The strategic logic here centers on analytical flexibility, parameter expansion within a single instrument, and the ability to serve laboratories that need to consolidate multiple characterization tasks. European manufacturing heritage, precise engineering, and configurable sample handling contribute to a value proposition that appeals to organizations seeking method consolidation and enhanced data continuity.
OEA Laboratories, based in Exeter, United Kingdom, occupies a complementary position by focusing on supplies and products designed for use with OEA and EA-IRMS instruments. Rather than competing directly on complete instrument platforms, the company supports the consumables, accessories, and application ecosystem that surround elemental analysis workflows. This positioning can be strategically valuable for buyers that prioritize supply reliability, application-specific consumables optimization, and ecosystem compatibility across different instrument brands.
PerkinElmer, also headquartered in Waltham, Massachusetts, competes through established analytical instrumentation offerings such as the 2400 CHNS/O Organic Elemental Analyzer for total carbon, nitrogen, hydrogen, and sulfur determination. Its market presence benefits from a broad instrument portfolio, longstanding relationships in analytical laboratories, and integration pathways that connect elemental analysis with other characterization and quality control functions within laboratory environments.
Strategic Patterns in a Consolidating yet Accessible Market
The market is not trending toward extreme concentration; instead, it is evolving toward functional specialization and ecosystem-based competition. The relatively narrow gap between the top three and top five firms suggests that competitive advantage is increasingly derived from application-specific validation, software-enabled workflow simplification, service responsiveness, and consumables efficiency rather than from sheer scale alone. Incumbents with broad portfolios can leverage cross-selling and service density, while focused competitors can gain share by solving a narrowly defined problem exceptionally well and building reference installations that propagate through industry networks.
New entrants and regional specialists continue to find viable niches, particularly where local service expectations, language and compliance requirements, or application-specific sample types create friction for global platforms that are not sufficiently localized. At the same time, acquisition activity and partnership strategies are quietly reshaping the landscape. Larger players seek to strengthen application coverage, consumables supply chains, and geographic service reach, while mid-tier firms explore agreements that expand their parameter coverage or software capabilities without undertaking full-platform development programs.
For procurement leaders and investors, the strategic implication is that vendor evaluation should extend beyond headline specifications. The durability of a purchasing decision depends on the alignment between instrument architecture and validated workflows, the predictability of consumables and service costs, the availability of method support for the specific matrices in use, and the likelihood that the platform can evolve as application requirements change. Competitors that invest in these dimensions are building switching costs that are based on operational reliability and data continuity rather than on lock-in alone.
PW Consulting
Forward Outlook: Trends Shaping the Next Three to Five Years
Trend One: Workflow Consolidation and Software-Defined Analysis
Over the next several years, the market is likely to reward platforms that reduce the complexity of method selection, calibration management, and data interpretation. Software-defined workflows that guide users from sample preparation through validated result reporting will become more important as laboratories seek to standardize operations across sites and reduce dependence on highly specialized operators. The commercial opportunity lies not only in instrument sales but in the recurring value of software subscriptions, method libraries, remote configuration support, and training ecosystems that lower the operational burden for buyers. Organizations that can demonstrate measurable reductions in setup time, method transfer errors, and result variability will capture disproportionate share in regulated and high-throughput environments.
A risk to monitor is the potential for software complexity to outpace user readiness. If interface design and validation tools are not intuitive, the promised efficiency gains may be undermined by longer adoption cycles and increased reliance on external support. Vendors that invest in user experience, documentation clarity, and role-based access will differentiate themselves in a segment where operational simplicity is becoming a competitive requirement.
Trend Two: Regional Demand Divergence and Service-Led Growth
Demand is expected to continue diverging by region, with Asia Pacific representing a substantial share of market expansion, North America sustaining strong adoption driven by pharmaceutical, analytical, and advanced manufacturing demand, and Europe maintaining robust activity shaped by regulatory and industrial testing requirements. Latin America and the Middle East and Africa will likely grow from smaller bases, with adoption shaped by the pace of laboratory modernization, regulatory formalization, and the availability of localized service support. The commercial opportunity for manufacturers is to align regional go-to-market strategies with local application priorities, establish service density where downtime is costly, and offer financing or managed-service models that reduce upfront capital barriers for mid-sized buyers.
A key uncertainty is the degree to which macroeconomic fluctuations and currency volatility affect procurement timing in emerging markets. Even when underlying demand is strong, budget cycles and foreign exchange dynamics can delay deployment. Companies that build flexible commercial terms and maintain reliable local consumables availability will be better positioned to convert demand into installed base over time.
Trend Three: Application Convergence and Cross-Industry Method Transfer
As analytical requirements become more tightly integrated into quality systems, there will be increasing interest in platforms capable of supporting method transfer across applications and sites with minimal revalidation burden. Laboratories that serve multiple industries or that operate shared analytical facilities will favor instruments that can accommodate diverse matrices while maintaining consistent performance characteristics. This trend creates opportunities for vendors that provide robust application libraries, cross-method validation guidance, and consumables configurations optimized for multi-application environments. The strategic benefit will accrue to organizations that can reduce the friction of moving methods between development, quality control, and contracted testing workflows.
The primary risk is that application diversity can also fragment demand if instruments are perceived as too specialized or too generalized. Vendors must strike a balance between parameter coverage, sample-scale flexibility, and the clarity of application-specific support. Overreach into configurations that dilute ease of use or inflate consumables overhead can weaken adoption, while overly narrow designs may miss cross-selling opportunities in laboratories with expanding analytical portfolios.
Strategic Actions for Decision Makers
For Manufacturers and Product Leaders
Product strategy should prioritize the intersection of analytical performance and operational simplicity. Investments in simultaneous multi-parameter determination, predictable consumables consumption, and software-assisted method management are likely to yield the strongest competitive returns. Equally important is the development of application-specific validation packages and service models that reduce total cost of ownership for buyers in regulated and high-throughput environments. Manufacturers that can articulate measurable improvements in throughput, repeatability, and method transfer efficiency will strengthen their positioning against both broad-portfolio incumbents and focused niche competitors.
Commercial strategy should emphasize regional service density and local application support where downtime and compliance scrutiny are significant concerns. Aligning consumables supply, calibration standards, and remote diagnostics with the realities of local procurement cycles can improve both win rates and long-term retention. For organizations considering portfolio expansion, targeted acquisitions or partnerships that add parameter coverage or software capabilities may deliver faster market impact than full-platform development programs.
For Investors and Strategic Allocators
Investment theses should account for the market's moderate concentration and the enduring role of application specialization. Recurring revenue streams tied to consumables, service agreements, and software support are valuable complements to instrument sales, particularly where buyers prioritize predictable operating costs and rapid issue resolution. When evaluating opportunities, diligence should examine not only technological specifications but also the depth of application validation, the reliability of consumables supply, and the credibility of regional service networks. Companies that can demonstrate durable customer relationships in regulated or high-volume applications are better positioned to sustain growth through procurement cycles and regional volatility.
Portfolio diversification across application areas and regions can reduce exposure to localized demand shocks, but only if the underlying commercial model supports effective service delivery and consumables management. Investors should also monitor the pace of consolidation and partnership activity, as these dynamics can reshape competitive advantages in parameter coverage, service reach, and software ecosystems faster than organic product roadmaps alone.
For Procurement Leaders and Laboratory Managers
Procurement decisions should be anchored in validated workflow fit rather than nominal specification comparisons. Evaluate platforms against the specific matrices, throughput requirements, documentation standards, and reporting formats that your operations demand. Assess total cost of ownership with explicit consideration of consumables consumption, calibration frequency, maintenance intervals, and the availability of local service and remote diagnostics. Where possible, structure evaluations around method transfer scenarios and multi-application use cases to ensure that the selected platform can support evolving analytical needs without excessive revalidation burden.
Worldwide Automatic Elemental Analyzer Market
Negotiation strategies should account for software support, training, and consumables predictability as value levers alongside hardware pricing. Establishing clear expectations for service response times, software update continuity, and application support can reduce operational risk and improve long-term return on investment. In multi-site organizations, standardizing on platforms that simplify method management and deliver consistent performance across locations can yield operational savings that exceed the apparent price differential between alternatives.
Why Detailed Market Intelligence Remains Essential
The Organic Elemental Analyzer market is expanding along a credible growth trajectory, but the most consequential decisions will be made at the level of application fit, service economics, and workflow integration rather than at the level of aggregate demand. The segmentation of demand across regions, instrument types, and application contexts matters because it determines where competitive advantage is created and where procurement risk is concentrated. Detailed breakdowns of regional dynamics, product-type adoption patterns, and application-level volume distribution provide the granularity needed to calibrate product strategy, service investments, and purchasing decisions with precision.
Executive teams, strategic planners, and investors who require that level of granularity can benefit from the full research report, which provides comprehensive segmentation data, company profiles, and forward-looking scenario analysis. Access to detailed submarket data and tailored strategic recommendations enables more disciplined capital allocation, more confident procurement negotiations, and more targeted product development priorities. For organizations seeking to act on the trends outlined here with specificity and speed, the complete research resource offers the depth required to translate market intelligence into executable strategy.
For detailed analysis of this topic, please visit the official page: Organic Elemental Analyzer (OEA) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


