



Management Consulting Services Market: Why 5.63% CAGR Redefines Competitive Dynamics

Management Consulting Services Market: Strategic Shifts and Commercial Opportunities in an AI-Reshaped Landscape
The global management consulting services market has entered a period of structural acceleration, with total revenue expanding from approximately $302.15 billion in 2020 to an estimated $391.68 billion in 2025. Projections indicate continued growth through 2032, with the market expected to reach $572.38 billion, sustaining a compound annual growth rate of 5.63 percent across the 2026 to 2032 forecast period. The trajectory reflects more than cyclical demand recovery; it signals a fundamental recalibration of how organizations procure, deploy, and measure advisory services. Growth is being concentrated in regions and segments where digital transformation, operational resilience, and regulatory complexity intersect, while traditional retainer-based engagements face mounting scrutiny over measurable outcomes. For executives and investors, the market is no longer simply expanding; it is reorganizing around new capability requirements, pricing models, and delivery architectures.
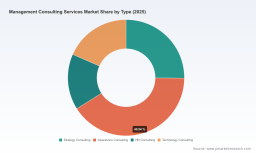
The expansion has been uneven across functional and industry dimensions, with operations-focused advisory and technology-adjacent consulting capturing disproportionate shares of incremental spend. At the same time, the market remains moderately concentrated, with the top three firms commanding roughly 52 percent of total revenue and the top five accounting for approximately 68 percent. This concentration masks a deeper fragmentation at the practice and sub-sector level, where specialized boutiques, technology-enabled delivery units, and cross-industry alliances are steadily redefining competitive boundaries. The persistence of concentration alongside rising specialization suggests that scale alone is no longer the primary competitive moat; instead, firms that can combine domain depth, implementation capacity, and technology integration are capturing the most durable growth.
1. Market Current State and Core Challenges
Redefining Value in a High-Expectation Environment
The consulting market is operating under a dual pressure: clients demand faster, more measurable impact while simultaneously questioning whether traditional advisory fare delivers sufficient differentiation. Several macroeconomic and structural forces have hardened this expectation. Organizations are navigating persistent cost discipline, supply chain reconfiguration, and a heightened focus on operational execution rather than purely strategic diagnosis. As a result, advisory engagements are increasingly judged against implementation readiness, technology integration, and the ability to embed change within legacy operating models. The consequence is a shift from episodic strategy projects to multi-year transformation partnerships, where value is measured in throughput gains, cost-to-serve improvements, and time-to-market for new products and channels.
This shift is colliding with a volatile cost environment for specialized talent. Specialized human labor costs within the sector have risen by an estimated 15 to 20 percent annually in 2025 and 2026, driven by demand for professionals who can combine domain expertise with AI-augmented advisory capabilities. Projected labor costs are anticipated to rise another 10 percent in 2026, reflecting shortages of skilled AI and digital transformation professionals. For consulting firms, this creates a margin equation that cannot be solved by headcount alone; productivity gains, automation of analytical workflows, and new delivery models are becoming essential to protect profitability while meeting rising client expectations.
Regulatory and Data-Privacy Complexity as a Delivery Constraint
Regulatory exposure is intensifying across multiple jurisdictions, with compliance requirements expanding around data privacy, algorithmic transparency, and the governance of technology-enabled advisory services. Recent assessments from US agencies and international bodies emphasize that management consulting services are increasingly subject to scrutiny when they intersect with sensitive client data, quantitative decision models, and AI-assisted recommendations. This adds a layer of operational complexity to engagement design, requiring stronger data handling protocols, auditability of analytical methods, and clearer boundaries between advisory input and client-controlled implementation. In practice, compliance costs are rising not only as a legal expense but as a design constraint that influences how engagements are scoped, delivered, and priced.
Concentration, Specialization, and the Hybridization of Delivery Models
While the market remains concentrated at the top, the competitive frontier is diversifying. Firms are blending strategy, operations, and technology advisory in ways that blur traditional category boundaries, while specialized players are gaining traction by focusing on high-complexity niches such as risk analytics, actuarial integration, and AI-enabled process redesign. The result is a market in which scale provides distribution and client access, but differentiation is increasingly driven by proprietary tools, implementation partnerships, and the ability to stand up large-scale transformation programs. New entrants and alliances are exploiting gaps where incumbents are either too broad to move quickly or too narrow to support end-to-end change. This hybridization is reshaping buyer behavior: organizations increasingly assemble portfolios of providers rather than relying on a single lead advisor, which rewards firms that can demonstrate interoperability, repeatability, and clear handoff to execution.
2. Key Drivers of Market Change
Technology Innovation and the Shift Toward Agentic AI
Technology is no longer a standalone consulting vertical; it is becoming the delivery backbone for strategy and operations alike. The integration of generative and agentic AI into advisory workflows is changing the economics of analysis, synthesis, and recommendation development. Rather than relying solely on manual research and bespoke modeling, firms are deploying AI agents to accelerate scenario analysis, benchmark extraction, process mapping, and unstructured data interpretation. This does not eliminate the need for senior judgment; it elevates it. The premium is moving toward professionals who can define the right problem frames, validate AI-generated outputs, and design human-in-the-loop processes that preserve accountability. The most consequential shift is operational: engagements are increasingly designed to leave behind reusable models, decision tools, and capability building rather than static decks.
Recent developments indicate that this transition is already at scale within leading firms. McKinsey & Company, for example, announced in January 2026 that it is deploying approximately 25,000 AI agents alongside roughly 40,000 human consultants to enhance productivity and client delivery. This combination signals a structural bet on blended delivery, where AI supports volume-intensive analytical tasks while human consultants concentrate on client interaction, synthesis, and implementation design. Similarly, Capgemini launched its Resonance AI Framework in July 2025 to help clients implement agentic AI at scale with human-AI collaboration for measurable business impact. These moves collectively suggest that AI is transitioning from an experimentation topic to a production-focused capability, with implications for pricing, staffing, and engagement timelines across the market.
Regulatory and Policy Environment as a Catalyst and Constraint
Policy dynamics are reshaping demand patterns in two directions. On one hand, emerging compliance obligations around data privacy, algorithmic accountability, and technology governance are prompting organizations to seek advisory support for risk assessment, control design, and transformation roadmaps. On the other hand, these same obligations constrain how consulting firms can collect, process, and reuse data across engagements. The July 2025 USITC report highlights that management consulting services face rising compliance requirements tied to data privacy and technological advancements, underscoring the regulatory weight now attached to advisory activities that involve sensitive information or automated decision support.
This environment favors firms with robust data governance, clear methodologies, and the ability to translate regulatory complexity into operational design. Sectors such as financial services, healthcare, and public-sector adjacent services are particularly exposed, which in turn shapes where demand is most resilient. For buyers, regulatory pressure is also changing procurement behavior: engagements increasingly require demonstrable compliance with data handling standards, clearer separation of advisory from implementation liability, and documented methodological rigor. The net effect is a market in which regulation is simultaneously expanding demand for advisory services and raising the bar for what qualifies as a credible engagement.
Demand-Side Shifts in Enterprise and Consumer Behavior
Client organizations are reevaluating what they expect from advisory relationships. There is growing skepticism toward generic strategy narratives, especially in environments where execution capacity is constrained by talent shortages or cost pressure. Buyers are increasingly prioritizing engagements that are tied to specific operating improvements, customer value creation, and technology-enabled change. This is reflected in a broader shift toward outcome-oriented commercial models, where pricing and success metrics are linked to measurable business impact rather than time and materials alone. In parallel, consumer-facing industries are pushing firms to integrate experience design, channel optimization, and data-driven personalization into their transformation agendas, while industrial and service sectors are focusing on productivity, asset utilization, and supply chain resilience.
This demand-side evolution is also driving fragmentation in spend patterns. Organizations are allocating more budget to capabilities that directly support execution, including process redesign, workforce change management, and digital operating model design. At the same time, the appetite for pure diagnostic work is becoming more selective, reserved for moments of strategic redirection, market entry, or major capital allocation decisions. For consulting providers, the implication is that durable demand will come from firms that can connect upstream insight to downstream execution, rather than from those offering isolated point solutions.
Cost Structure and Supply Dynamics in a Talent-Constrained Market
The supply side of the market is being reshaped by talent scarcity and cost escalation. The rising premium for professionals with AI, digital transformation, and domain-specific expertise is altering the cost structure of advisory delivery. With specialized labor costs rising sharply, firms are under pressure to improve throughput without diluting quality. This has accelerated interest in labor-mixing strategies, where routine analytical tasks are delegated to automation or lower-cost pools while senior professionals focus on high-leverage decisions and client relationships. It has also intensified the search for repeatable methodologies, modular deliverables, and knowledge assets that can be reused across clients to reduce marginal cost.
On the supply frontier, geography and capability availability are increasingly intertwined. Regional demand is growing in areas where industrial transformation, digital adoption, and regulatory change converge, but the ability to deliver depends on access to skilled talent and implementation partners. This is creating a two-sided constraint: demand is strong where transformation is urgent, but execution capacity is uneven. Firms that can mobilize blended teams, leverage alliances, and scale delivery through standardized toolkits are gaining an advantage, while those dependent on bespoke, high-cost teams risk margin compression and slower responsiveness.
3. Competitive Landscape and Leading Strategies
Strategic Positioning Across Different Firm Archetypes
The competitive map is defined less by uniform scale than by differentiated positioning along strategy, operations, technology, and industry depth. At one end are global strategy-oriented firms that compete on thought leadership, senior client access, and cross-functional problem framing. These firms typically build their reputations on high-stakes decisions, corporate strategy, and transformation direction-setting. At another end are firms with strong implementation credentials, where consulting is integrated with technology services, systems integration, or outsourcing capabilities. These players compete on end-to-end delivery, scale, and the ability to transition recommendations into operational reality. A third archetype includes specialized boutiques that win through depth in narrow domains, such as private equity value creation, risk and actuarial advisory, or growth strategy in particular industries.
The largest players illustrate these strategic choices clearly. McKinsey & Company positions around strategy, digital transformation, and operations advisory, and is actively reinforcing that model with large-scale AI deployment to improve productivity and client delivery. Boston Consulting Group emphasizes strategy, corporate finance, and digital innovation, with a focus on business and government clients, suggesting a balanced orientation toward high-level problem formulation and digital execution. Bain & Company leans into strategy, private equity, and operations, aligning its brand with value creation and performance-focused engagements. Accenture differentiates through the integration of consulting with technology and digital transformation solutions, making implementation capacity a core part of its advisory proposition. Deloitte, PwC, EY, and KPMG each offer management consulting within broader professional services portfolios, allowing them to connect advisory work with audit, tax, technology, and risk capabilities. Oliver Wyman, Booz Allen Hamilton, Capgemini, L.E.K. Consulting, and Kearney further diversify the landscape through specialized strengths in risk management, government and technology solutions, AI-enabled operations, growth advisory, and strategy-operations integration.
Business Management Consulting Service Market
Differentiation Through Capability, Alliance, and Delivery Models
The most sustainable advantages in this market are emerging from three sources. The first is proprietary capability that can be scaled, including AI-enabled analysis, decision-support tools, and reusable transformation frameworks. The second is ecosystem positioning, where alliances and partnerships extend a firm’s reach into adjacent domains such as actuarial risk, systems integration, or industry-specific implementation. The third is delivery architecture, where firms design engagements to leave behind capabilities, governance, and measurement systems rather than one-off recommendations. These advantages matter because clients increasingly evaluate providers on repeatability, speed, and the ability to transfer knowledge into the organization.
Recent moves highlight how these differentiators are being operationalized. Oliver Wyman’s April 2026 strategic partnership with Actuarial teams under Marsh McLennan is an example of extending strategy and risk advisory capabilities through specialized integration, strengthening the firm’s position where financial, operational, and risk considerations intersect. Such alliances reflect a broader trend in which consulting firms expand credibility and coverage by partnering with domain specialists rather than building every competency internally. This pattern is likely to accelerate where complexity is high and where the cost of building proprietary depth in every niche would be prohibitive.
Toward Consolidation, Fragmentation, and Selective New Entry
Market structure is evolving along multiple axes at once. Concentration at the top remains significant, which implies that scale, brand, and global client access continue to confer advantages in large enterprise accounts and multi-year transformation programs. At the same time, the front edge of competition is fragmenting as practice-level specialization, regional capability centers, and technology-led delivery models create new competitive dynamics. New entrants and mid-tier challengers are gaining relevance where they can offer speed, niche depth, or more flexible commercial terms, particularly in engagements that require rapid mobilization or deep operational involvement.
The likely trajectory is not simple consolidation or fragmentation, but selective combination. Larger firms will continue to acquire reach and cross-functional breadth, but they will also face pressure to modularize services and improve delivery economics. Specialized players will seek to scale through partnerships, productized offerings, or targeted expansion into adjacent capabilities. Meanwhile, technology providers and implementation-centric firms will continue to blur the line between consulting and execution, creating hybrid competition that traditional strategy firms must either match or complement through alliances. For buyers, this means that provider selection is becoming more multidimensional, with evaluation criteria that include capability depth, delivery model, technology enablement, and the ability to integrate with internal teams.
4. Future Trends and Commercial Implications
Trend One: AI-Augmented Advisory Becomes the Delivery Default
Over the next three to five years, AI-augmented advisory is expected to shift from a differentiator to a baseline expectation. The combination of agentic AI, advanced analytics, and human judgment will become embedded in problem definition, scenario design, benchmarking, and implementation planning. The commercial implication is significant: engagements that rely solely on manual analysis will face growing cost and speed disadvantages, while firms that can operationalize AI safely and effectively will be able to scale insight generation and improve throughput. The opportunity lies not in replacing consultants, but in reconfiguring the value chain so that human expertise concentrates on judgment, client alignment, and implementation design while AI supports volume-intensive analytical tasks. The risk is execution discipline: firms that deploy AI without strong governance, validation, and client-ready explainability may expose themselves to quality and trust issues, especially in regulated or high-stakes contexts.
Trend Two: Outcome-Oriented Commercial Models Gain Ground
Commercial models are likely to continue shifting toward measurable outcomes, with pricing and incentives tied more closely to business impact, adoption metrics, and sustained operating improvements. This trend will be reinforced by rising labor costs and client demand for greater accountability. Advisory engagements will increasingly need to define success in operational terms, such as improved throughput, reduced cost-to-serve, faster decision cycles, or stronger customer outcomes. For providers, this creates both opportunity and risk. The opportunity is to build repeatable frameworks that connect strategy to execution and to develop measurement systems that demonstrate value over time. The risk is that outcome-based models require deeper client integration, stronger change management, and the ability to navigate implementation complexity, which may not suit all engagement types or all buyers.
Trend Three: Regulatory and Compliance Complexity Drives Demand for Governance-Led Transformation
Regulatory and compliance complexity is expected to remain a structural driver of demand, particularly in sectors where data usage, technology deployment, and decision automation are accelerating. Organizations will increasingly seek advisory support not only for growth and efficiency, but for governance design, risk integration, and compliance-ready operating models. This opens commercial opportunities for firms that can connect strategy, operations, and technology with clear accountability and auditability. At the same time, it introduces uncertainty: regulatory trajectories differ across regions, and expectations around data privacy and technology governance may evolve quickly. Firms that can maintain methodological rigor while adapting to local requirements will be better positioned than those relying on one-size-fits-all frameworks. A further uncertainty is the potential for regulatory fragmentation to slow cross-border delivery models or increase the cost of data reuse across engagements.
Uncertainty and Risk Factors to Monitor
Several factors could alter the trajectory of growth and competitive dynamics. Continued escalation in specialized labor costs may compress margins for firms that cannot offset them through productivity improvements or delivery redesign. Talent shortages in AI and digital transformation could constrain the speed at which firms scale new capabilities, particularly in regions where skilled professionals are scarce. Regulatory developments may raise compliance costs or limit the reuse of data and models across engagements, affecting both economics and speed. In addition, client budget discipline could shift spend toward a smaller number of higher-conviction initiatives, intensifying competition for large mandates while reducing appetite for exploratory work. These risks do not negate growth, but they suggest that the market will reward firms that manage cost, compliance, and capability deployment with discipline.
5. Strategic Actions for Decision Makers
For Transformation Leaders and Operating Executives
Treat advisory selection as an execution decision, not just a strategy purchase. When evaluating providers, prioritize those that can demonstrate how insight will translate into operating change, including clear handoff to implementation, reusable tools, and measurable success criteria. Favor engagements that are designed to build internal capability and leave behind decision-support assets rather than static deliverables. Given rising labor costs and talent constraints, also assess whether a provider’s delivery model uses automation, knowledge reuse, and blended teams in ways that protect speed and quality without inflating cost.
For Investors and Portfolio Managers
Evaluate consulting exposure with attention to delivery economics and positioning, not only revenue scale. Firms that combine domain depth with AI-enabled productivity, implementation alliances, and outcome-oriented commercial models are better placed to sustain margins in a cost-escalating environment. Monitor concentration carefully, but also watch the specialized and hybrid players that are gaining traction in high-complexity niches. The most useful signals will come from evidence of repeatable delivery, credible governance around data and AI, and the ability to win engagements where execution—not just diagnosis—is the primary value driver.
PW Consulting
For Procurement and Commercial Teams
Use the shifting supply landscape to improve commercial terms and risk allocation. Expect greater variation in pricing models, delivery approaches, and liability structures, which creates room to negotiate outcome-linked components, clearer data-handling obligations, and stronger handoff arrangements. Where possible, assemble multi-provider portfolios that separate strategy, implementation, and specialist risk or technology work, allowing each partner to play to its strengths. Ensure that procurement criteria include governance standards, methodological transparency, and evidence of capability transfer, since these will increasingly determine whether an engagement creates durable value or remains a short-term intervention.
Computer Consulting Services Market
The trajectory of the management consulting services market is being shaped by the convergence of technology-enabled delivery, regulatory complexity, rising talent costs, and a client base that is more demanding in return for its spend. These forces are not simply expanding the market; they are redefining where value is created and how competitive advantage is earned. For decision makers seeking to act with precision—whether in provider selection, investment allocation, or transformation planning—the value of detailed segment-level data, competitive mapping, and customized scenario analysis is substantial. A comprehensive research report can provide deeper visibility into regional and functional splits, company-level positioning, and forward scenarios that support more targeted execution.
For detailed analysis of this topic, please visit the official page: Management Consulting Services Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


