



Sugar Centrifugal Screens Market 2032: Beyond 6.5% CAGR, What Drives $275M Growth

Sugar Centrifugal Screens Market: Strategic Trends and Commercial Opportunities for the Next Decade
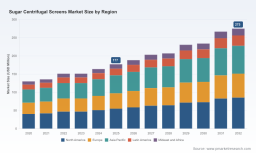
The global sugar centrifugal screens market has established itself as a critical niche within industrial processing equipment, with total revenue reaching approximately $177.0 million in 2025 and an expected trajectory toward $275.0 million by 2032. This growth path reflects a compound annual growth rate of 6.5 percent across the forecast horizon through 2032, building on a recovery from the pandemic-era contraction seen between 2020 and 2021. The market's expansion is not merely a function of volume but of structural shifts in processing efficiency, material science adoption, and regional demand recalibration. For executives and investors evaluating industrial consumables and processing components, understanding the centrifugal screen segment requires looking beyond headline growth rates to the operational and competitive dynamics that shape margin realization and market access.
The sector's trajectory over the historical window from 2020 to 2025 demonstrates resilience and selective acceleration. Revenue moved from $130.0 million in 2020 to $135.6 million in 2021, followed by a pronounced step-up to $151.09 million in 2022 and a plateau near $151.18 million in 2023 before pushing to $163.96 million in 2024. The 2025 baseline of $177.0 million signals that the post-pandemic normalization has given way to sustained demand expansion. Forecasts project $188.41 million in 2026, $203.3 million in 2027, $207.03 million in 2028, $230.69 million in 2029, $234.03 million in 2030, $266.71 million in 2031, and $275.0 million in 2032. This progression suggests that the market is entering a phase where incremental efficiency gains and replacement cycles, rather than first-time capacity additions alone, will drive recurring revenue streams.
Centrifugal Pump Market
Market Conditions and Key Challenges
The centrifugal screen market operates at the intersection of heavy processing equipment renewal cycles and consumable component replacement dynamics. Screens function as critical separation elements within batch and continuous centrifuges, directly influencing crystal purity, throughput consistency, and downstream refining quality. Because these components interface with high-stress operational environments — abrasive sugar crystals, acidic or alkaline process liquors, and mechanical vibration — their performance dictates both production uptime and product specification compliance. The market's modest size relative to broader processing equipment categories belies its strategic importance, as screen performance can influence overall plant efficiency far beyond the component's standalone cost.
PW Consulting Automotive & Machinery Research Center
Three structural challenges currently shape the market environment. First, the tension between replacement frequency and total cost of ownership remains unresolved for many operators. Lower upfront cost options often impose higher downtime and more frequent change-outs, while premium materials carry higher initial pricing but extend service life. This calculus varies significantly by application intensity, plant scale, and regional labor cost structures, creating fragmented purchasing behavior rather than uniform specification standards. Second, procurement complexity is rising as end-users increasingly demand documented quality assurance, material traceability, and compatibility verification across multiple centrifuge brands and generations. Screens are not interchangeable commodities; dimensional tolerances, surface finish, and perforation geometry affect separation efficiency, which means specification errors can cascade into throughput losses or product quality deviations. Third, supply chain volatility for specialty materials — particularly high-purity nickel for electroformed screens and specific stainless steel grades for stamped or laser-drilled alternatives — introduces cost unpredictability that suppliers and buyers must actively manage through inventory strategy and long-cycle ordering.
The competitive structure reflects moderate concentration, with the top three participants accounting for roughly 45 percent of revenue and the top five capturing approximately 55 percent. This concentration level suggests a market where established suppliers hold meaningful share but where specialized performers can still compete on technical differentiation, regional service capability, and application-specific engineering support. The presence of both screen-only specialists and integrated centrifuge manufacturers creates a dual-channel dynamic: some buyers source screens directly from component specialists seeking maximum material performance, while others obtain screens through original equipment channels that emphasize compatibility assurance and unified maintenance support.
Core Growth Drivers and Influence Points
Several interdependent factors are shaping demand trajectories and supplier strategy in this market. The most consequential is the ongoing shift in material specification philosophy, moving from a narrow focus on initial purchase price toward lifecycle economics. Electroformed nickel screens have gained recognition for their corrosion resistance across a broad pH range, dimensional stability, and smooth surface characteristics that reduce crystal breakage during separation. These attributes matter in applications where sugar purity, particle integrity, and consistent flow rates are prioritized. At the same time, stainless steel and brass alternatives continue to serve segments where cost sensitivity is higher or where process conditions are less aggressive. The result is a bifurcated specification environment in which material selection is becoming more application-engineered rather than standardized across all use cases.
A second driver is the increasing emphasis on processing uptime and maintenance predictability. Screen failure in a centrifuge can interrupt batch cycles, force unscheduled cleaning, and disrupt downstream scheduling. Suppliers that can demonstrate extended service life under matched operating conditions, combined with predictable replacement intervals, are able to position their products as part of broader operational reliability programs rather than isolated component purchases. This framing aligns with operator priorities in environments where labor for unplanned maintenance carries significant cost and where throughput consistency is tied to contractual supply commitments. The practical implication is that screen suppliers with strong application data, installation guidance, and field performance documentation are gaining advantage in specification decisions, especially where multiple technically acceptable options exist.
A third factor is the regulatory and quality assurance environment surrounding export and compliance. Screens used in international sugar processing supply chains increasingly require documented test certificates aligned with recognized standards for corrosion resistance and dimensional stability. This requirement affects both suppliers and buyers: manufacturers must maintain certified quality systems and reproducible manufacturing processes, while end-users must verify that imported screens meet the specifications needed for their process chemistry and centrifuge design. Compliance is not merely a customs or procurement formality; it reduces the risk of performance deviations and supports consistent batch quality, which is especially relevant for exporters of refined sugar products subject to stringent customer specifications.
A fourth influence comes from regional demand recalibration and processing modernization. While mature markets continue to drive replacement and upgrade activity, emerging processing regions are expanding capacity and improving filtration and separation standards as part of broader quality and efficiency initiatives. This dynamic broadens the addressable base for screen suppliers, but it also introduces variation in technical requirements, procurement maturity, and service expectations. Suppliers that can adapt specification packages, provide application engineering support, and maintain reliable logistics to diverse markets are better positioned to capture growth without overextending into regions where service infrastructure is insufficient to protect performance claims.
Recent field activity reinforces these dynamics. In September 2024, a laser-drilled centrifugal screen deployment was documented at a major British sugar operation to address high-wear screen life issues. This case illustrates how customized perforation technology and targeted material application can resolve persistent wear problems in demanding operating environments, and it signals growing interest in solution-oriented screen configurations rather than generic catalog orders. Such deployments matter because they demonstrate that screen specification can be optimized to specific wear patterns, flow conditions, and maintenance constraints — reinforcing the trend toward application-tailored procurement.
Competitive Landscape and Strategic Positioning
The competitive field includes a mix of screen specialists, precision perforation manufacturers, and centrifuge OEMs that also supply compatible screens. This diversity creates a market where differentiation hinges on material expertise, perforation capability, application compatibility, and service responsiveness rather than on price alone. The most visible strategic positions cluster around three archetypes.
The first archetype is the electroformed nickel specialist. Manufacturers focused on high-purity nickel screens emphasize mirror-smooth surfaces, broad chemical resistance, and dimensional accuracy suitable for continuous and batch centrifuges across multiple major equipment brands. Their value proposition rests on performance durability, filtration consistency, and compatibility with internationally recognized specification frameworks. For operators running aggressive process chemistries or prioritizing minimal crystal damage, this positioning directly addresses lifecycle outcomes rather than initial unit cost. The export orientation of these suppliers also reflects an understanding that compliance documentation and repeatable manufacturing quality are prerequisites for serving dispersed global buyer bases.
The second archetype is the precision perforation and laser-drilling specialist. These suppliers focus on hole geometry control, slotted and round hole configurations, and wear mitigation through engineered perforation patterns. Their relevance grows in environments where standard perforation approaches have proven insufficient for screen life targets or where specific flow and retention characteristics are needed. Laser-drilled and precision-perforated screens can be particularly compelling where wear patterns are uneven or where crystal size distribution and throughput targets require tailored separation characteristics. The British Sugar case illustrates how this archetype can move from generic supply to problem-solving engagement.
The third archetype is the integrated centrifuge manufacturer or equipment supplier offering compatible screens as part of a broader system solution. For some buyers, this channel reduces specification risk, simplifies procurement, and aligns screen replacement with equipment maintenance planning. The strategic trade-off is between the convenience and compatibility assurance of an integrated supply channel and the potential performance optimization available through specialized screen suppliers. In practice, many larger operators maintain relationships across both channels, selecting component specialists for specific high-wear or high-specification applications while relying on equipment channels for standardization and service coordination.
The market is evolving along several structural lines. One is the gradual elevation of technical service and documentation as competitive requirements. Suppliers that can provide application engineering support, installation guidance, and performance data aligned to specific centrifuge types and process conditions are better positioned to defend share against lower-cost alternatives. Another is the continued relevance of multi-brand compatibility. Screens that can be specified across BMA, FCB, and other major centrifuge platforms reduce buyer friction and expand the addressable installed base, which is why compatibility claims appear prominently among leading screen suppliers. A third evolution is the potential for selective consolidation or partnership activity, as screen specialists seek broader geographic reach or as equipment manufacturers look to strengthen component supply reliability. New entry remains possible, particularly where a supplier brings a distinct perforation technology, a cost-advantaged manufacturing process, or a strong regional service model, but the barrier to meaningful share capture lies in demonstrating durable performance and building trust with specifying engineers and maintenance teams.
Forward Outlook: Three to Five-Year Trends
Looking ahead, three trends are likely to shape market outcomes through the late 2020s and into the early 2030s. The first is the continued migration toward specification based on total operating cost rather than initial price. As operators accumulate field experience comparing screen life, failure modes, and maintenance labor, the economic case for higher-durability materials in high-stress applications becomes more persuasive. This does not imply universal premiumization; rather, it implies more deliberate matching of material and perforation choice to application intensity. For suppliers, this trend rewards the ability to quantify performance differences, provide installation and maintenance guidance, and maintain consistency across production batches.
The second trend is growing emphasis on wear-optimized and application-specific screen configurations. As plants seek to reduce unplanned downtime and extend run lengths between change-outs, customized perforation geometry, material grade selection, and backing screen combinations are likely to receive more attention. The practical effect is a shift from catalogue purchasing toward engineered solutions in a meaningful subset of orders, especially where wear issues have already prompted operational frustration. This trend opens opportunities for suppliers with strong laser-drilling, precision perforation, or electroforming capabilities to engage earlier in specification discussions and to build reference installations that support broader adoption.
Centrifugal Separator Market
The third trend is the widening of geographic opportunity sets alongside increased buyer sophistication. As processing modernization continues across multiple regions, more facilities are adopting higher separation and filtration standards, which expands demand for screens that meet stricter quality and compatibility expectations. At the same time, buyers in these markets are increasingly aware of documentation, certification, and aftermarket support requirements. Suppliers that can combine product quality with reliable export compliance, technical support, and logistics resilience will be better positioned to convert regional growth into sustained account relationships.
These trends carry inherent uncertainties. Material cost volatility can compress margins for manufacturers and complicate pricing commitments for buyers, particularly when specialty nickel or specific steel grades are involved. Exchange rate movements can affect export competitiveness and import cost structures for screen procurement in different regions. On the demand side, sugar processing economics are influenced by raw material availability, energy costs, and end-market pricing, which can shift the pace of capacity expansion and the timing of equipment and component renewal. There is also the risk that overly aggressive standardization could understate application-specific needs, leading to premature wear or performance shortfalls that damage confidence in otherwise suitable technologies.
Strategic Implications for Decision Makers
Manufacturers and component suppliers should prioritize two areas. First, strengthen the evidence base that connects material and perforation choices to measurable operational outcomes. Field data on service life, wear patterns, and maintenance intervals — presented in a way that maps to specific centrifuge types and process conditions — is increasingly valuable in specification discussions. Second, invest in compatibility breadth and documentation rigor. Suppliers that can demonstrate multi-brand fit, maintain certified quality processes, and provide export-compliant test documentation reduce friction for international buyers and strengthen their position in markets where procurement teams are under pressure to de-risk supplier selection.
Investors evaluating participation in this market should focus on the durability of differentiation rather than on headline growth alone. Because the market is specialized and moderately concentrated, competitive advantage tends to come from manufacturing precision, material expertise, application engineering, and service responsiveness. Businesses that rely primarily on commoditized supply without technical differentiation face greater vulnerability to price competition and substitution. Conversely, suppliers with demonstrated field performance, strong reference installations, and the ability to serve demanding applications are better positioned to defend margins and grow share. Due diligence should therefore examine not only order books and capacity but also technical service capability, customer retention in high-specification segments, and exposure to material cost and export compliance risk.
Buyers and procurement leaders should approach screen specification as a lifecycle decision rather than a transactional purchase. The most effective procurement strategy matches material and perforation choice to actual operating intensity, establishes clear compatibility and documentation requirements before ordering, and balances standardization benefits against the performance gains available from application-tailored solutions. Where wear or downtime has been a recurring issue, engaging suppliers with precision perforation or high-durability material capabilities earlier in the specification process can reduce the cycle of trial and error. Where standardization and service simplicity are paramount, integrated supply channels can still play a valuable role, particularly when backed by reliable compatibility assurance and maintenance planning support.
For stakeholders seeking a more detailed view of regional demand structures, application-level splits, type-based revenue distribution, and company-by-company positioning, the full research report provides the granular segmentation and customized scenario analysis needed for planning. The commercial logic of the centrifugal screen market is increasingly defined by specification discipline, lifecycle economics, and the ability to deliver consistent performance across diverse processing environments. Organizations that align procurement, supply, and investment decisions with these realities are better placed to capture the value embedded in the market's projected growth path through 2032.
For detailed analysis of this topic, please visit the official page: Sugar Centrifugal Screens Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


