



EPDM Market 2026–2032: The 5% CAGR Growth Path and Strategic Shifts

Strategic Trends and Commercial Opportunities in the EPDM Market: A 2025–2032 Outlook
Market Landscape and Core Challenges
The Ethylene Propylene Diene Monomer (EPDM) market has demonstrated consistent expansion over the past five years, evolving from a baseline of approximately 4,000.0 million USD in 2020 to an estimated 5,000.0 million USD in 2025. This trajectory reflects a compound annual growth rate of 5.0 percent, with projections indicating the market will reach 7,029.12 million USD by 2032. The growth pattern is not merely a function of incremental demand but rather a reflection of deepening integration across automotive manufacturing, infrastructure development, and industrial electrical systems. EPDM's unique combination of weather resistance, thermal stability, and chemical compatibility has cemented its position as a foundational elastomer in sectors where material failure carries significant operational or safety costs.
Ethylene Propylene Diene Rubber (EPDM) Market
Despite this favorable trajectory, the industry faces structural challenges that will shape competitive dynamics in the coming years. First, regulatory and fiscal scrutiny is intensifying around chemical substances used in large volumes. A petition filed in mid-2025 requesting that EPDM rubber be included in the Superfund Tax on Chemical Substances in the United States introduces uncertainty around cost structures and compliance burdens. While the outcome remains unresolved, the petition signals a broader shift in how policymakers evaluate polymer-based supply chains, particularly those with significant environmental persistence or complex disposal pathways.
Second, the push toward circularity is reshaping material expectations across end-use industries. The European Union's revised Directive on Packaging and Packaging Waste, which mandates 30 percent recycled content by 2030, has created regulatory pressure that extends well beyond packaging. Automotive and industrial sectors are now facing similar expectations to incorporate recycled or bio-derived content into elastomer applications. This creates a tension for EPDM producers and downstream formulators, who must balance performance requirements with sustainability targets that were not originally designed into the material's chemical architecture.
Third, supply chain resilience remains a critical vulnerability. Regional disparities in feedstock availability, energy costs, and manufacturing infrastructure mean that demand shocks or policy shifts in one geography can cascade through global pricing. The market's concentration, with the top three players holding approximately 45 percent of revenue and the top five accounting for 55 percent, reduces competitive fragmentation but also concentrates supply risk. Companies outside these tiers must navigate pricing power dynamics carefully, while leading firms must manage the operational and reputational implications of supply disruptions.
Key Drivers Shaping Market Trajectory
Technological Innovation and Material Performance
Advancements in EPDM formulation and compounding are expanding the material's addressable use cases beyond traditional sealing and roofing applications. Manufacturers are developing grades with improved resistance to ozone, UV degradation, and steam exposure, which directly benefits automotive cooling systems, outdoor building envelopes, and wire insulation in harsh environments. At the same time, innovations in processing technology are reducing cycle times and enabling more precise control over cross-link density, which improves consistency for high-volume industrial buyers. These technical improvements are not incremental; they are enabling EPDM to compete more effectively against alternative elastomers in applications where cost-performance trade-offs previously favored other materials.
The implications for commercial strategy are significant. Producers that can offer differentiated grades tailored to specific environmental or mechanical requirements create pricing premiums and deeper customer lock-in. Conversely, commoditized EPDM offerings face margin pressure as buyers gain access to broader supplier options. The trend favors firms that invest in application-specific R&D and maintain closer technical collaboration with downstream manufacturers.
Policy and Regulatory Environment
Regulatory developments are acting as both a constraint and a catalyst. The potential inclusion of EPDM in chemical tax frameworks raises the cost baseline for producers and can influence sourcing decisions, particularly in price-sensitive segments. At the same time, sustainability mandates are pushing innovation in recyclable and recycled-content elastomers. Companies that proactively align their formulations with emerging regulatory expectations position themselves to capture demand from customers facing compliance deadlines. In Europe, where regulatory leadership is most pronounced, early movers in sustainable EPDM variants stand to gain preferential access to automotive and construction supply chains that are under pressure to demonstrate credible environmental progress.
For decision-makers, the regulatory dimension requires scenario planning. A single policy shift can alter the economics of a product line or trigger requalification processes that take months. Engaging with regulatory trends early, rather than reacting after mandates take effect, reduces the risk of stranded inventory or lost contracts.
Demand-Side Shifts in Automotive and Construction
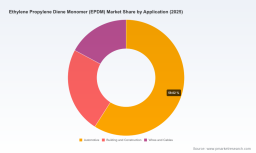
Automotive demand remains the largest application driver for EPDM, driven by the material's role in sealing systems, vibration damping, and weatherproofing components. As vehicle platforms evolve, EPDM continues to find relevance in both internal combustion and electrified architectures, though the specific component mix is shifting. Building and construction applications provide a second robust demand pillar, particularly in roofing membranes, window seals, and waterproofing systems where long service life and low maintenance requirements justify material selection. Growth in infrastructure investment across emerging economies, combined with renovation activity in mature markets, sustains steady consumption in this segment.
The Wire and Cable sector adds a complementary growth channel, especially where electrical systems must operate in outdoor or chemically aggressive environments. As industrial automation, renewable energy installations, and grid modernization expand, demand for durable insulation materials increases. These demand-side dynamics do not operate in isolation; they interact with energy prices, labor availability, and project financing cycles. Understanding where demand is most inelastic versus where it is sensitive to macro conditions helps buyers and sellers anticipate volume volatility.
Supply Chain and Cost Structure Evolution
Feedstock pricing, energy costs, and manufacturing scale are the core levers shaping EPDM economics. Regional production footprints determine exposure to logistical friction and local energy markets. Recent capacity announcements illustrate how producers are attempting to rebalance supply geography and reduce vulnerability. For example, in mid-2025, Dow Inc. announced plans to increase EPDM rubber production in the United States by restarting additional capacity at its Plaquemine, Louisiana site. This move reflects a broader industry pattern of reevaluating domestic manufacturing footprints to improve responsiveness, reduce exposure to trade disruptions, and align capacity with regional demand clusters.
Cost structure evolution is not only about raw material prices. It also encompasses the operational efficiency of polymerization and compounding processes, logistics optimization, and the ability to absorb regulatory or tax impacts without eroding competitiveness. Producers with integrated operations or long-term feedstock agreements tend to navigate cost volatility more effectively than those reliant on spot-market inputs. For downstream buyers, supplier stability and transparent cost drivers are becoming as important as unit price when qualifying long-term supply agreements.
Competitive Landscape and Leading Strategies
The EPDM market is characterized by a mix of global chemical majors and specialized elastomer producers, each pursuing distinct strategic positioning. ExxonMobil has established a strong presence through its Vistalon™ EPDM elastomers, emphasizing formulation consistency and broad application coverage that appeals to large industrial buyers seeking reliable supply across multiple end-use categories. Dow Inc. continues to compete aggressively with its NORDEL™ and NORDEL™ REN EPDM grades, differentiating through a combination of performance versatility and geographic manufacturing reach, including recent capacity reinforcement in North America.
Lanxess AG and ARLANXEO represent the European-centric strength in the market. Lanxess focuses on Buna®EP EPDM elastomers, leveraging technical service and specialty formulations that serve automotive and industrial customers with demanding performance criteria. ARLANXEO's Star™ EPDM products similarly emphasize application reliability and grade flexibility, supporting customers that require consistent properties across varied processing conditions. These European players benefit from proximity to automotive and construction hubs with stringent quality and sustainability expectations, and they often compete on technical support and qualification speed as much as on price.
Asian suppliers are expanding their influence through scale, cost competitiveness, and increasingly sophisticated product portfolios. SK Geo Centric Co., Ltd. and Kumho Polychem Co., Ltd. in South Korea, along with Mitsui Chemicals, Inc. in Japan, offer EPDM elastomers and rubber products that serve both domestic demand and export markets. PetroChina Company Limited brings substantial feedstock and production scale advantages in China, while Lotte Versalies Elastomers contributes specialized EPDM rubber offerings from its Seosan operations. These players are increasingly important in a market where regional demand growth in Asia Pacific outpaces many other geographies and where cost-conscious buyers prioritize value and delivery reliability.
PW Consulting Health Care Research Center
Versalis S.p.A. rounds out the competitive set with its own EPDM product lines, reflecting the continuing role of integrated petrochemical platforms in supplying elastomer intermediates and finished grades. Together, these companies illustrate a market where scale, technical differentiation, and regional presence determine competitive outcomes.
The strategic dynamics among these leaders are shifting in several ways. Integration and portfolio rationalization are leading some producers to concentrate on high-margin specialty grades, while others pursue capacity additions to capture volume growth in core segments. Differentiation is increasingly tied to sustainability credentials, application-specific performance, and supply reliability rather than price alone. New entrants face high barriers due to the technical qualification requirements of automotive and construction customers, but indirect competition can emerge from alternative elastomers or recycled-content substitutes if performance gaps narrow. Market fragmentation is unlikely in the near term given the concentration structure, but pressure from regulatory compliance costs and regional capacity shifts will test the margins of producers that lack scale or specialized application capabilities.
Future Trends and Commercial Implications (2026–2032)
Trend 1: Sustainability-Linked Product Architectures Gain Commercial Relevance
Over the next three to five years, EPDM offerings will increasingly be evaluated not only on mechanical performance but also on lifecycle attributes. The regulatory direction in Europe, combined with customer sustainability targets in automotive and construction, will accelerate demand for grades that can demonstrate recycled content, improved recyclability, or lower carbon intensity in production. Producers that develop credible sustainability narratives backed by verifiable data will find more opportunities to enter qualified supplier lists and negotiate favorable terms. This trend creates commercial openings for formulators who can blend performance with compliance, but it also raises the risk of greenwashing scrutiny if claims are not substantiated. Market participants should expect qualification processes to become more rigorous and documentation requirements to expand.
Trend 2: Regional Capacity Realignment and Supply Chain Localization
Capacity decisions announced in recent periods are likely to be followed by further adjustments as manufacturers respond to energy economics, trade policy, and demand geography. North American and European producers are likely to maintain or expand capacity where feedstock advantages and customer proximity justify investment, while Asian producers will continue to scale to serve regional demand growth and export opportunities. This realignment can reduce lead times and logistics exposure for some buyers, but it can also create pockets of tight supply if demand accelerates faster than capacity comes online. Commercial strategies that rely on single-source suppliers in vulnerable geographies will face greater risk, making multi-region sourcing and inventory buffering more attractive for critical applications.
Trend 3: Application Convergence and Material Substitution Pressures
As EPDM grades improve and alternative elastomers advance, the boundaries between material choices will continue to shift. In some automotive and industrial applications, performance gains in EPDM will expand its share of demanding use cases. In others, substitution pressure may increase where cost or sustainability targets favor competing materials. The net effect is that EPDM's growth will be driven less by universal expansion and more by targeted wins in applications where its weather resistance, thermal stability, and durability provide clear value. This dynamic rewards suppliers and buyers who understand application-specific trade-offs rather than treating EPDM as a uniform commodity. Companies that map where EPDM is structurally favored versus where it is vulnerable to substitution will make better sourcing and product development decisions.
Strategic Recommendations for Decision-Makers
For EPDM producers and compounders, the priority is to protect margins while building defensible differentiation. This means investing in application-linked grade development, strengthening technical service capabilities, and preparing for regulatory scenarios that could affect cost structures. Capacity decisions should be evaluated against regional demand trajectories and feedstock economics, with an emphasis on flexibility to adjust product mix as customer requirements evolve. Companies that can demonstrate consistent quality, transparent sustainability data, and reliable delivery will be better positioned to retain key accounts and expand into higher-value segments.
For investors and corporate development teams, the market offers opportunities tied to scale, specialization, and regional realignment. Interest should focus on producers with strong positions in automotive and construction demand centers, credible plans for sustainability-related product development, and supply chain configurations that reduce exposure to policy or logistical shocks. Valuation considerations should account for the impact of potential tax or regulatory changes on cost bases, as well as the upside from capacity additions that align with confirmed demand growth. Diversification across geographies and application segments can mitigate concentration risk, while exposure to highly commoditized segments without differentiation may limit return potential.
For procurement and supply chain leaders, the emphasis should be on resilience and qualification agility. Qualifying multiple suppliers across regions, understanding the cost drivers behind quoted prices, and maintaining visibility into regulatory developments can reduce disruption risk. Building collaborative relationships with suppliers on sustainability and performance expectations can shorten requalification cycles when material changes are needed. Procurement strategies that balance cost optimization with supply security and compliance readiness will be more durable as regulatory and market conditions evolve.
Conclusion and Next Steps for Deeper Market Intelligence
The EPDM market is entering a period where growth is supported by broad demand fundamentals but shaped decisively by regulatory pressure, sustainability expectations, and regional capacity decisions. The combination of steady compound annual growth, concentrated competitive structures, and evolving application requirements creates a market that rewards strategic foresight and detailed operational intelligence. Organizations that act on these dynamics early can secure supply advantages, align product portfolios with emerging demand, and manage cost and compliance risks more effectively.
Deeper segmentation data, granular regional forecasts, competitor benchmarking, and customized sourcing or investment scenarios can sharpen decision-making further. For readers seeking a more detailed view of volume dynamics, price trends, and segment-specific opportunities, the full PW Consulting research report provides an expanded dataset and proprietary analysis designed to support executive planning, investment evaluation, and supply chain strategy.
Isoprene Monomer Market
For detailed analysis of this topic, please visit the official page: Ethylene Propylene Diene Monomer (EPDM) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


