



Electric Submeter Market: Why the 6.98% CAGR Path to 2032 Changes Everything

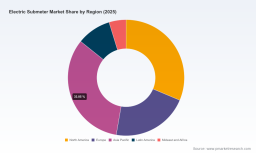
Electric Submeter Market: Strategic Trends and Commercial Opportunities Through 2032
The electric submeter market has moved from a niche utility-billing adjunct to a core component of energy management, regulatory compliance, and operational efficiency across commercial, industrial, and residential sectors. Over the past half-decade, the sector has demonstrated steady expansion, with revenue climbing from approximately 163.15 million USD in 2020 to an estimated 215.0 million USD in 2025. The trajectory points toward a forecast period of 2026 through 2032, during which the market is projected to grow at a CAGR of 6.98 percent, reaching roughly 344.8 million USD by 2032. These figures reflect more than incremental hardware sales; they signal a structural shift in how facilities track, allocate, and optimize electricity consumption at a granular level.
For executives, strategists, and investors, the numbers provide a baseline, but the real value lies in understanding what is accelerating adoption, where friction points are accumulating, and which strategic moves will separate leaders from laggards. The following analysis maps the current market landscape, the forces reshaping demand and supply, the competitive dynamics among established and emerging players, and the trajectory likely to define the next several years.
Market Landscape and Core Challenges
The electric submeter market today sits at the intersection of regulatory mandates, building modernization cycles, and a growing appetite for data-driven energy accountability. Revenue growth over the historical period from 2020 to 2025 has been consistent, with the market surpassing the 200 million USD threshold as institutions and property operators increasingly treat submetering as a compliance and cost-management necessity rather than an optional upgrade. The forecast window through 2032 suggests continued expansion, though the pace will be shaped by how quickly standards, installation economics, and integration capabilities align across regions and building types.
Key Challenges and Inflection Points
Despite the upward trajectory, the market faces several structural challenges that will determine which segments scale efficiently and which encounter bottlenecks.
- Regulatory heterogeneity and compliance complexity. Submetering requirements are no longer uniform. Jurisdictions are introducing building-specific mandates, submetered-party inquiry procedures, and updated performance criteria that vary by application and geography. For technology providers and end users alike, navigating a patchwork of rules increases deployment risk, slows procurement cycles, and raises the cost of ensuring that installed systems remain compliant as regulations evolve.
- Installation economics and retrofit friction. Hardware cost is only one component of total cost of ownership. Retrofit installation expenses, which vary with building age, panel configuration, and labor availability, can materially affect project ROI. In older buildings, limited access to distribution panels and the need for customized routing can stretch timelines and budgets, making submetering less attractive unless the payback case is clearly quantified.
- Standardization and performance expectations. As submetering moves into revenue-grade and portfolio-level monitoring contexts, expectations around accuracy, interoperability, and data quality are rising. Updated metering codes and performance criteria are pushing vendors to demonstrate that devices can meet both operational monitoring needs and stricter billing-grade requirements. Companies that cannot align with evolving standards risk losing eligibility for public-sector evaluations and commercial contracts that increasingly reference recognized performance benchmarks.
These challenges are not stagnant barriers; they are inflection points. Markets that can reduce installation complexity, clarify compliance pathways, and demonstrate credible performance under updated standards will capture disproportionate share as procurement teams seek lower-risk deployments.
Core Drivers Reshaping the Market
The growth profile of the electric submeter market is being shaped by a combination of technology evolution, regulatory pressure, demand-side behavior shifts, and changing cost structures. Each driver reinforces the others, creating a feedback loop that is accelerating adoption in specific application areas while also raising the bar for product and service maturity.
Technology Innovation and Breakthroughs
Submetering technology is increasingly defined by real-time data capture, wireless deployment flexibility, and integration with analytics platforms. Devices that can deliver circuit-level visibility, tenant billing data, and portfolio energy monitoring are moving beyond simple consumption tracking to become operational tools for fault detection, load management, and energy reporting. The shift toward hardware-software bundles is particularly significant: organizations are looking for systems that not only measure electricity but also translate measurements into actionable insights, automated reporting, and centralized monitoring across multiple buildings.
This trend is visible in the growing emphasis on low-cost and revenue-grade options. Public-sector evaluations have highlighted submetering points at approximately 200 USD for standard accuracy and around 250 USD for revenue-grade accuracy, signaling that cost thresholds are becoming more defined and that competitive devices must balance affordability with performance. At the same time, installation cost benchmarks for retrofits—often ranging from 250 to 500 USD per unit depending on building age and panel configuration—mean that hardware price alone does not determine adoption. Solutions that reduce installation time, simplify wiring, or enable wireless architectures are gaining relevance because they lower the total friction of deployment.
Policy and Regulatory Environment
Policy is one of the strongest catalysts for submeter adoption. Mandates that require submeter installation in larger commercial spaces, along with updated rules for electricity and natural gas submetering, are expanding the addressable base of buildings that must measure consumption at a more granular level. In parallel, regulatory bodies are refining procedures related to submetered-party inquiries and system approvals, which increases transparency but also raises administrative expectations for metering providers and building operators.
Standard-setting activity is equally important. Updated codes for electricity metering that establish performance criteria for AC watthour meters, smart meters, and auxiliary devices are raising the baseline for what qualifies as a dependable metering solution. For commercial and public-sector buyers, alignment with recognized standards is increasingly a prerequisite rather than a differentiator. This regulatory momentum favors vendors that can document compliance, support auditable reporting, and adapt device performance to evolving test requirements.
Demand-Side Shifts in Consumer and Enterprise Behavior
End-user expectations are changing on two fronts. First, building owners and property operators are under greater pressure to manage operating expenses, allocate utility costs fairly, and demonstrate energy accountability to tenants and stakeholders. Submetering supports tenant billing, portfolio monitoring, and identification of inefficient loads, which makes it a practical tool for both cost control and sustainability narratives.
Second, the industrial and commercial sectors are demanding more circuit-level and system-level visibility. Facilities are not just asking whether total consumption is rising or falling; they want to know which circuits, tenants, or processes are driving usage. This demand is pushing submetering beyond aggregate measurement into diagnostic and operational use cases. In multifamily and commercial properties, the need for accurate billing and transparent usage data is particularly acute, while in industrial settings the focus is often on operational efficiency, load balancing, and integration with broader energy monitoring programs.
Supply Chain and Cost Structure Dynamics
Cost structures are being reshaped by the interplay of hardware pricing, labor costs, and the growing availability of low-cost metering options for public and commercial use. As reference points for submeter hardware prices become more established, procurement teams are increasingly able to benchmark offers and challenge vendors on total cost. This environment rewards providers that can deliver transparent pricing, predictable installation workflows, and bundled services that reduce hidden deployment expenses.
Labor and installation complexity remain sensitive variables. Retrofit projects in older buildings can incur higher costs because of panel access issues and customization requirements, while newer constructions may allow more streamlined deployments. The market is therefore seeing a divergence in adoption ease across building vintages and configurations. Suppliers that offer flexible installation models, clearer scopes of work, and services that minimize on-site disruption are better positioned to convert interest into completed projects.
Competitive Landscape and Leading Strategies
The electric submeter market is not dominated by a single archetype of competitor. Instead, it contains a mix of analytics-oriented providers, wireless and low-cost hardware specialists, circuit-level metering firms, established commercial utility submetering brands, and service-focused billing and installation companies. This diversity reflects the fact that buyers have different priorities: some want strong analytics and tenant billing integration, others prioritize low-cost wireless deployment, and still others value installation services or billing consultation.
Strategic Positioning and Differentiation
A few patterns stand out among the companies shaping the market.
- Real-time analytics and tenant billing focus. Some providers concentrate on real-time electrical submetering for tenant billing, portfolio energy monitoring, and data analytics in multifamily and commercial buildings. Their differentiation lies in turning meter data into billing-ready outputs and ongoing energy visibility, which appeals to property operators seeking both compliance and operational insight.
- Low-cost wireless and energy monitoring systems. Other companies emphasize low-cost wireless electrical submeters and energy monitoring for commercial and residential applications. This positioning targets cost-sensitive deployments and faster installation cycles, making it relevant for large-scale rollouts where hardware affordability and ease of deployment are decisive.
- Circuit-level and multi-utility measurement. A third group focuses on circuit-level electric submetering along with water, gas, and BTU meters, often with wireless deployment for commercial, industrial, and institutional facilities. This broader measurement scope supports facilities that want unified visibility across utilities rather than electricity alone.
- Hardware-plus-SaaS monitoring platforms. Some vendors combine submetering hardware with SaaS platforms for granular electricity, gas, and water monitoring, including automated reporting. The strategic advantage here is reduced manual reporting burden and continuous data availability, which is especially valuable for portfolios with many metered points.
- Commercial utility submetering and compliance-oriented product lines. Established suppliers with commercial utility submetering solutions and dedicated series for accurate energy monitoring in multifamily and commercial properties often compete on reliability, brand recognition, and documented compliance support.
- Service and billing-oriented models. Several companies focus on electric submetering solutions paired with utility billing services, custom system design, installation, maintenance, and consultation for multifamily and commercial facilities. In these cases, the value proposition is not just hardware but the operational support that keeps submetering programs functioning smoothly.
These positions are not mutually exclusive, but they illustrate how the market is segmenting around analytics, affordability, multi-utility coverage, platform integration, and service delivery. Companies that clearly define their target deployment context—and align product, pricing, and support accordingly—are more likely to win repeat business and public-sector evaluation interest.
Market Structure Evolution: Consolidation, Fragmentation, and New Entrants
The market structure appears moderately fragmented, with no single concentration dominance. This fragmentation creates room for specialized players to thrive in focused niches, but it also encourages consolidation pressure over time as buyers prefer fewer, more capable partners who can cover multiple building types, utilities, and reporting needs.
Several forces are likely to shape this evolution. Public-sector evaluations that assess device performance for federal facilities can accelerate preference for vendors with proven, documented results, effectively narrowing the field for certain procurement categories. Regulatory updates that standardize performance expectations and submetering procedures can raise entry barriers for products that cannot meet updated criteria, while also giving compliant incumbents a stronger footing. At the same time, new entrants may emerge from adjacent markets—energy analytics, wireless sensor networks, or building automation—bringing fresh capabilities but also facing the challenge of demonstrating metering-grade credibility.
Worldwide Distribution Meter Market
In this environment, differentiation is increasingly tied to three questions: Can the solution meet current accuracy and performance expectations? Can it be deployed without excessive installation friction? And can it deliver usable data outputs for billing, reporting, and operational decisions? Providers that answer all three convincingly will be best positioned as the market matures.
Worldwide Prepayment Meter Market
Future Trends and Commercial Opportunities
Looking ahead through the forecast period, several trends are likely to define the electric submeter market and create distinct commercial opportunities.
Trend 1: Standardization as a Market Filter
Updated metering codes and evolving regulatory requirements will increasingly act as a filter rather than a mere technical footnote. Devices and systems that align with recognized performance criteria will gain access to a wider set of commercial and public-sector opportunities, while those that lag may face procurement exclusion or higher scrutiny. The commercial opportunity here lies in building compliance documentation, test alignment, and auditable performance reporting into product strategy early, rather than treating them as after-the-fact certifications.
Trend 2: Lower-Friction Deployment Models
As installation economics remain a major determinant of project viability, the market will likely reward approaches that reduce onsite complexity. Wireless architectures, streamlined retrofit methods, and bundled service offerings can lower the total cost and time required to deploy submetering across multiple points or buildings. For manufacturers and service providers, this creates an opportunity to differentiate not just on device features but on deployment workflow, labor efficiency, and predictable project outcomes.
Trend 3: From Measurement to Operational Intelligence
Submetering is increasingly valued for what happens after measurement. Real-time monitoring, automated reporting, circuit-level diagnostics, and tenant or portfolio-level analytics are becoming part of the core purchase rationale. The commercial opportunity is to move beyond selling metering points toward selling outcomes: clearer billing, faster issue detection, better load visibility, and reduced manual reporting effort. Providers that integrate hardware with software workflows and demonstrate tangible operational benefits will have stronger leverage in competitive evaluations.
Risks and Uncertainties
These trends are not without risk. Regulatory divergence across jurisdictions can complicate product planning and slow multi-region rollouts. Installation cost variability can undermine projected ROI in older or complex buildings, especially if labor or access constraints are underestimated. In addition, as standards tighten, some existing devices may require updates or replacements to remain eligible for revenue-grade or compliance-sensitive applications. Buyers and vendors alike should treat submetering investments as part of a longer-term program, with attention to future-proofing, documentation, and service continuity.
PW Consulting
Actionable Guidance for Decision Makers
The electric submeter market offers meaningful opportunities, but capturing them requires decisions that are aligned with deployment context, compliance expectations, and total cost rather than hardware price alone. The following guidance is oriented toward three common stakeholder perspectives.
For Manufacturers and Technology Providers
- Prioritize compliance readiness and documentation. With updated metering codes and regulatory procedures gaining prominence, clear evidence of performance alignment can become a decisive advantage in commercial and public-sector evaluations.
- Reduce deployment friction. Hardware specifications matter, but installation efficiency can be equally important. Designing for easier retrofits, flexible wiring, or wireless deployment can expand addressable projects and improve win rates in cost-conscious segments.
- Bundle measurement with usable data workflows. Solutions that connect submetering to automated reporting, tenant billing support, or portfolio monitoring are better positioned to compete on outcomes rather than on points alone.
For Investors and Strategic planners
- Focus on segments where regulatory momentum and operational demand reinforce each other. Commercial, industrial, and multifamily settings with compliance drivers and cost-allocation needs are likely to sustain demand more reliably than purely optional installations.
- Evaluate total cost of deployment, not just device pricing. Installation variability, labor exposure, and service requirements can materially affect margin and scalability, especially in retrofit-heavy portfolios.
- Watch for consolidation signals. As buyers seek fewer, more capable partners, companies that can cover multiple utilities, building types, and reporting needs may gain strategic value, while narrow specialists may face pressure unless they maintain a strong niche advantage.
For Procurement and Operational Buyers
- Define the use case before evaluating hardware. Tenant billing, circuit-level diagnostics, portfolio monitoring, and compliance documentation have different requirements. Clear objectives help avoid over-specifying or under-specifying the system.
- Ask for total project economics. Include installation variability, labor exposure, and ongoing reporting or maintenance needs in the comparison, not just per-point hardware cost.
- Verify compliance and performance documentation early. Where regulations, standards, or public-sector evaluation criteria apply, confirm that proposed devices and processes align before committing to deployment timelines.
Closing Perspective
The electric submeter market is expanding within a context that rewards clarity, credibility, and operational usefulness. Growth is supported by regulatory mandates, rising demand for granular energy accountability, and a technology base that is increasingly capable of delivering real-time monitoring and actionable reporting. At the same time, the market is being shaped by installation economics, standardization pressure, and a competitive landscape that ranges from low-cost wireless specialists to analytics-driven platforms and service-oriented billing providers.
For organizations looking to act with confidence, the next step is to connect market-level direction with segment-specific detail: the relevant application context, regional regulatory nuances, pricing benchmarks, and vendor capabilities that matter for a particular deployment. Detailed segmentation data, company profiles, recent developments, and compliance-related updates provide the granularity needed to translate broad trends into concrete decisions. For decision makers seeking a deeper, data-backed view of submarket sizes, competitive positioning, and forward-looking scenarios, a comprehensive research report can offer the structured detail required to support planning, sourcing, and investment choices.
For detailed analysis of this topic, please visit the official page: Electric Submeter Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


