



Rail Market Insights: Why 6.47% CAGR Through 2032 Signals a Structural Shift

Rail Market Strategic Trends and Commercial Opportunities Through 2032
The global rail market has entered a decisive growth phase, expanding from $142.5 billion in 2020 to an estimated $193.76 billion in 2025, with projections indicating continued acceleration toward $300.51 billion by 2032. This trajectory reflects a compound annual growth rate of 6.47% across the forecast period, positioning rail infrastructure and rolling stock as one of the more resilient segments within heavy industrial markets. The expansion is not merely cyclical recovery but structural growth driven by transportation decarbonization mandates, urban mobility shifts, and substantial infrastructure investment programs across multiple geographies. For executives and investors evaluating exposure to this sector, the question has shifted from whether rail markets will grow to how value will be distributed across the supply chain and which capabilities will capture disproportionate returns.
Understanding the current market architecture requires looking beyond headline figures to examine where capital is flowing, which segments are absorbing investment, and what structural constraints are shaping competitive dynamics. The market composition reveals a concentrated landscape where scale, technical certification, and regional presence create meaningful barriers, while simultaneously leaving openings for specialized players who can address niche performance requirements or integrate emerging technologies into legacy systems.
Market Architecture and Structural Challenges
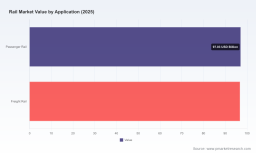
The rail market operates across multiple interconnected layers, from foundational track infrastructure and electrification systems to signaling architectures and rolling stock manufacturing. Revenue distribution across these components reflects both historical investment patterns and emerging priorities. Track systems continue to represent the largest share of market activity, followed by rolling stock and signaling infrastructure, with electrification and power supply representing a smaller but rapidly evolving segment. Application demand splits between passenger and freight operations, with both segments showing sustained capital deployment rather than one dominating at the expense of the other.
Three structural challenges define the current inflection point and will shape competitive outcomes over the next several years.
Supply Chain Fragmentation and Lead Time Volatility
Rail manufacturing remains heavily dependent on specialized steel production, precision casting, and complex assembly processes that span multiple jurisdictions. The industry has experienced recurring pressure from raw material pricing fluctuations, constrained capacity for long rail production, and uneven availability of certified components. These dynamics create execution risk for large infrastructure programs and compress margins for manufacturers who cannot optimize inventory positioning or secure forward commitments on critical inputs. The challenge is particularly acute for operators managing multi-year deployment schedules where supply interruptions cascade into operational delays and cost overruns.
Aging Infrastructure Versus Modernization Mandates
Much of the existing rail infrastructure in mature markets requires significant rehabilitation, while emerging markets are simultaneously expanding networks to support economic development. This dual pressure creates a complex investment environment where capital must be allocated between maintenance of legacy systems and deployment of next-generation components. The tension is especially visible in signaling and electrification, where upgrading existing corridors requires compatibility with operational continuity while meeting newer safety and capacity standards. Organizations that can deliver modular upgrade pathways rather than full corridor shutdowns gain a distinct advantage in winning procurement competitions.
Regulatory Alignment and Certification Complexity
Rail systems operate under stringent safety and interoperability requirements that vary across jurisdictions. While harmonization efforts continue, certification processes remain time-intensive and can delay market entry for new technologies or cross-border deployments. The regulatory environment is also evolving to accommodate automated operations, data-driven maintenance, and cybersecurity requirements for signaling and control systems. Companies navigating this landscape must balance innovation speed with compliance rigor, and those able to establish recognized certification pathways early position themselves to shape procurement specifications rather than react to them.
Key Demand Drivers Reshaping the Market
The market trajectory is being pulled by several reinforcing forces that extend beyond cyclical infrastructure spending. Understanding how these drivers interact helps identify where growth will concentrate and which capabilities will be most valued by buyers.
Technology Innovation and Operational Integration
Rail technology is moving from isolated component improvements toward integrated system performance. Automation, advanced diagnostics, and data analytics are increasingly embedded into both rolling stock and infrastructure management. Recent developments illustrate this shift clearly. Hitachi Rail opened a new advanced manufacturing facility in Hagerstown, Maryland, delivering railcars equipped with AI-powered video analytics for metro systems, including the D.C. Metro and Baltimore. This reflects a broader move toward smart fleet deployment where onboard intelligence supports maintenance forecasting, passenger safety monitoring, and operational efficiency. In parallel, Hitachi Rail partnered with DB Cargo to launch Europe’s first automated freight locomotive equipped with ATO and RTO technology, signaling that automation is expanding beyond passenger corridors into freight operations where labor constraints and throughput targets are intensifying interest in assisted and autonomous running.
For manufacturers and technology providers, the commercial implication is that value is shifting toward integrated solutions rather than standalone hardware. Companies that can combine physical components with software-enabled performance, predictive maintenance, and remote monitoring are better positioned to command premium positioning and longer-term service relationships.
Policy Momentum and Infrastructure Funding Cycles
Government investment programs and transportation policy frameworks continue to serve as powerful demand catalysts. Rail benefits from its alignment with decarbonization goals, congestion reduction targets, and supply chain reliability objectives. Public funding is increasingly tied to performance criteria, interoperability standards, and domestic manufacturing content, which shapes not only the volume of demand but also the composition of eligible suppliers. The policy environment also influences technology adoption, as procurement specifications increasingly reflect next-generation track circuit capabilities aimed at improving occupancy detection and broken rail identification, replacing legacy systems with more resilient monitoring architectures.
For industry participants, policy cycles create both opportunity and planning complexity. Multi-year funding commitments support capacity expansion and technology investment, but shifting regulatory emphasis and qualification requirements can alter competitive dynamics mid-cycle. Organizations that maintain active engagement with standards development and procurement evolution are better equipped to anticipate specification changes and align product roadmaps accordingly.
Demand-Side Shifts in Mobility and Freight Logistics
Passenger mobility patterns and freight logistics strategies are reshaping where rail demand emerges. Urban and regional passenger rail continues to attract investment as cities manage congestion and aim to expand mass transit capacity. At the same time, freight operators are evaluating rail as a component of broader logistics resilience, particularly where consistent volume movement and lower emissions intensity provide competitive advantage. The balance between passenger and freight investment suggests that both segments will remain significant demand centers, but with different procurement rhythms and specification priorities. Passenger projects tend to emphasize capacity, comfort, and integrated transit features, while freight procurement prioritizes durability, throughput, and total cost of ownership across heavy-use cycles.
This divergence matters for suppliers because it affects product mix, service models, and go-to-market strategy. Companies that can tailor solutions to distinct operating profiles, rather than offering uniform specifications across applications, are more likely to win segmented contracts and build repeat engagement.
Cost Structure Evolution and Manufacturing Efficiency
Cost competitiveness in rail increasingly depends on production scale, material efficiency, and process innovation. The ability to produce longer rail lengths with consistent dimensional quality reduces joint-related maintenance and improves installation efficiency, which directly affects lifecycle cost for operators. In North America, manufacturers are supplying hot-rolled finished rails in lengths up to 320 feet with strong dimensional consistency and surface finish, reflecting process maturity that supports both freight and industrial applications. At the same time, broader labor economics and event-driven industry engagement, such as large-scale rail exhibitions expected to draw thousands of attendees from dozens of countries, illustrate the continued importance of relationship networks, technical exchange, and supply chain coordination in this market.
Cost structure advantages are not limited to raw material pricing. They also emerge from design standardization, reduced assembly complexity, and the ability to serve multiple rail environments with adaptable components. Suppliers that can demonstrate lower installed cost, faster deployment, and reduced maintenance burden are increasingly competitive, especially in procurement environments where total lifecycle economics outweigh upfront price comparisons.
PW Consulting
Competitive Landscape and Strategic Positioning
The rail market features a mix of established multinational suppliers, regional specialists, and technology-forward operators expanding their manufacturing and service footprint. Market concentration remains meaningful, with the top three competitors holding approximately 52% of market share and the top five reaching around 58%. This concentration reflects the importance of scale, certification breadth, and long-standing customer relationships in winning major infrastructure and rolling stock programs. At the same time, the presence of focused specialists indicates that specialized capability and regional responsiveness continue to matter, particularly in complex trackwork, fastening systems, and tailored material solutions.
Railway Equipment Market
Several leading companies illustrate different strategic angles within the market. Pandrol operates as a global leader in rail fastening systems, aluminothermic welding, track construction equipment, electrification solutions, and resilient track infrastructure components, with deployments across more than 100 countries. Its breadth across mainline, heavy-haul, and urban applications demonstrates how a component-focused supplier can achieve scale by standardizing high-performance interfaces while adapting to varied operating environments. Vossloh AG supplies rails, turnouts, concrete sleepers, fastening systems, and rail and turnout maintenance solutions for freight, high-speed, and urban rail, positioning itself across both infrastructure and maintenance segments. This dual exposure allows the company to engage customers across the asset lifecycle rather than only at initial installation.
In North America, voestalpine Railway Systems Nortrak specializes in design, innovation, and manufacturing of special trackwork, turnouts, frogs, crossings, switches, concrete and turnout ties, castings, and mouldings for Class I, passenger transit, and industrial rail sectors. Its recent acquisition of Unitrac Railroad Materials assets from Wabtec to expand special trackwork capacity illustrates a consolidation strategy aimed at strengthening regional manufacturing footprint and broadening material offerings. Steel Dynamics Inc. operates as a North American manufacturer of hot-rolled steel rails, joint and splice bars, guard bars, and mine ties, with continuous welded rail production extending to 320-foot lengths. Its profile underscores the continuing importance of domestic steel production capability and long-rail manufacturing in serving freight and industrial demand.
Differentiation Paths in a Concentrated Market
Leading competitors generally pursue one or more of the following differentiation strategies.
-
Lifecycle coverage: Expanding from product supply into maintenance, monitoring, and service integration to deepen customer relationships and capture recurring revenue.
-
Regional scale and responsiveness: Investing in local manufacturing and material capacity to reduce lead times, simplify logistics, and meet content or sourcing preferences in key markets.
-
Technical specialization: Concentrating on high-complexity components such as special trackwork, fastening systems, or custom castings where certification, engineering support, and application expertise create barriers to substitution.
-
Technology-enabled performance: Embedding analytics, automation, and advanced diagnostics into rolling stock and infrastructure solutions to improve operational outcomes and differentiate on total system value.
The competitive landscape is evolving through both consolidation and targeted expansion. Asset acquisitions are being used to secure capacity, broaden portfolios, and enter adjacent specialties, while established players with manufacturing footprint and technology capabilities are extending into automation and smart system integration. At the same time, new entrants and technology providers are finding openings in software-driven maintenance, analytics, and automation layers where traditional hardware dominance is less absolute. The likely direction is a market in which large suppliers continue to hold substantial share, but competitive advantage increasingly depends on the ability to combine physical manufacturing strength with technology integration, regional execution, and lifecycle service models.
Forward Trends and Commercial Implications
Looking toward 2026 through 2032, several trends are likely to define where value is created and how competitive dynamics shift.
Trend 1: Integrated Automation and Smart Operations Become Procurement Norms
Automation and data-driven operation are moving from pilot programs to broader deployment across both passenger and freight rail. The launch of automated freight locomotives and AI-enabled metro railcars indicates that operational intelligence is becoming part of the core product proposition rather than an add-on. Over the next several years, procurement specifications will increasingly expect compatibility with remote monitoring, predictive maintenance, and assisted operation. Commercial opportunity will favor suppliers that can deliver not only hardware but also the sensing, software, and integration capabilities needed to support smarter operations. The risk is that organizations underestimating the operational change, training, and cybersecurity requirements associated with automated systems may face adoption friction or delay.
Trend 2: Lifecycle Value and Service Integration Outweigh Pure Equipment Pricing
As infrastructure ages and modernization programs expand, buyers will place greater weight on total cost of ownership, maintenance burden, and uptime performance. This favors suppliers that can offer durable components, easier replacement pathways, and service models that reduce operational disruption. The trend also supports business models where recurring service revenue becomes a larger share of supplier economics. Companies that remain strictly transactional in their engagement may find margin pressure intensifying, while those that build long-term performance accountability can secure more stable relationships. A key uncertainty is the pace at which operators are willing to transition from legacy maintenance practices to new monitoring and replacement regimes, which will affect the speed of adoption.
Trend 3: Regional Manufacturing and Supply Chain Resilience Shape Sourcing Decisions
Supply chain reliability, lead time predictability, and regional content expectations will continue to influence procurement decisions. The ability to produce long rail lengths with consistent quality, maintain local inventory of critical components, and respond quickly to project-specific requirements will remain valuable, particularly in large markets where infrastructure programs are scaling. This trend supports continued investment in regional manufacturing assets and may encourage further consolidation among suppliers seeking to achieve scale and coverage. The uncertainty lies in how raw material availability, energy costs, and trade dynamics evolve, since these factors can alter the economics of localized production versus broader supply networks.
Strategic Considerations for Decision Makers
Different stakeholders face distinct priorities, but several actionable themes apply across the board.
For Rail Manufacturers and Component Suppliers
-
Prioritize lifecycle capability alongside product performance. Engineering strength in a single component category remains important, but customers increasingly value suppliers who can support installation, maintenance, and performance monitoring across the asset life.
Worldwide Rail Components Market -
Invest in technology integration where it strengthens competitive positioning. Automation-compatible hardware, diagnostic interfaces, and analytics-ready designs can differentiate offerings and support higher-value contracts.
-
Use targeted acquisitions or capacity expansion to secure regional manufacturing presence and specialty material capabilities, especially where special trackwork, fastening systems, or long-rail production are strategically important.
For Investors Evaluating Rail Exposure
-
Focus on companies with diversified revenue across components, applications, or service layers, since reliance on a single product cycle can increase volatility in a market where procurement timing and specification changes matter.
-
Assess exposure to automation, maintenance services, and regional manufacturing scale as indicators of future margin resilience, rather than looking only at top-line growth potential.
-
Monitor consolidation activity and capacity moves as signals of where competitive concentration is increasing and where niche specialists may be gaining or losing ground.
For Procurement Leaders and Rail Operators
-
Evaluate suppliers on total lifecycle performance and integration capability, not only upfront unit cost. Compatibility with monitoring, maintenance, and automation roadmaps can materially affect long-term operating economics.
-
Plan upgrade pathways that maintain operational continuity while adopting next-generation signaling and track monitoring capabilities, since full corridor shutdowns can create cost and scheduling risk that outweighs technical benefits if not managed carefully.
-
Balance multi-source strategies with the need for technical coherence, ensuring that component interfaces, certification standards, and service support align across the system rather than optimizing individual purchases in isolation.
Closing Perspective
The rail market is entering a period in which growth is increasingly tied to technological integration, lifecycle performance, and supply chain reliability rather than simple capacity expansion. The projected path from $193.76 billion in 2025 toward $300.51 billion by 2032 reflects a market where demand is broadening across passenger and freight applications, where automation and analytics are becoming embedded in core offerings, and where scale and specialization coexist as viable competitive models. The organizations that will capture the most durable value are those that can align product capabilities with evolving procurement priorities, maintain regional execution strength, and integrate service and technology into their market positioning.
For decision makers navigating this environment, the most useful intelligence is not broad market sizing alone but detailed visibility into segment dynamics, competitive moves, technology adoption patterns, and region-specific procurement behavior. PW Consulting’s comprehensive rail market research report provides deeper segmentation data, competitive profiling, and customized strategic guidance to support execution planning across manufacturing, investment, and procurement decisions. Readers seeking a fuller view of market splits, regional nuances, and forward scenario detail can explore the complete report for a more granular basis to evaluate opportunities and risks in the rail sector.
For detailed analysis of this topic, please visit the official page: Rail Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


