



Coronary Stents Market: How 6.5% CAGR and Drug-Eluting Dominance Redefine Growth

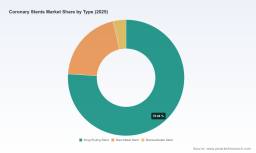
Beyond the Catheter Lab: Strategic Shifts Reshaping the Coronary Stents Market
The coronary stents market has evolved from a volume-driven business into a precision-driven arena where clinical differentiation, reimbursement architecture, and regional procurement behavior intersect. With the global market reaching approximately USD 6,920 million in 2025 and projected to expand at a 6.5% CAGR through 2032, the industry is not merely scaling—it is restructuring around performance metrics, procedural economics, and patient stratification. This transformation carries distinct implications for manufacturers navigating R&D pipelines, investors evaluating portfolio risk, and health systems optimizing interventional cardiology programs. The following analysis maps the structural dynamics, competitive maneuvers, and forward-looking opportunities that will define the next phase of value creation in coronary stenting.
Market Landscape and Defining Challenges
The market's trajectory over the past half-decade reflects steady expansion with notable inflection points. From a base of roughly USD 5,800 million in 2020, revenue progression has been characterized by moderate annual growth, with accelerated movement in recent years as newer-generation platforms and procedural complexity drove uptake. The forecast horizon through 2032 points toward a market approaching the USD 10.7 billion range, sustained by procedural volume growth, technology upgrades, and shifting clinical protocols. This growth, however, is not uniform across segments; it is increasingly concentrated among manufacturers that can demonstrate improved deliverability, reduced late-stage complications, and alignment with reimbursement incentives.
PW Consulting Health Care Research Center
Three interlocking challenges are redefining strategic priorities:
- Clinical differentiation is narrowing the window for me-too launches. Operators now expect stents that perform predictably in complex anatomy, support rapid endothelialization, and minimize long-term inflammatory exposure. Devices that do not articulate a clear clinical or procedural advantage face intensifying scrutiny during formulary reviews and procurement tenders.
- Reimbursement architecture is shaping procedural economics. Pricing and coverage for stent placement are being influenced by procedural coding adjustments, bundled payment pressures, and payer attention to total cost of care. As coding structures evolve to recognize complexity, manufacturers must align product attributes with the economic signals that drive procedure selection and site-of-care decisions.
- Supply chain resilience and input cost volatility are reshaping margins. Material sourcing, manufacturing precision, and global logistics continue to introduce variability. Companies that can stabilize input costs while preserving quality and delivery timelines gain a structural advantage in both price negotiations and product availability.
These dynamics create a market where scale alone is insufficient. The ability to demonstrate differentiated clinical value, navigate reimbursement signals, and maintain cost discipline determines who captures share as the market moves toward the next billion-dollar milestone.
Core Drivers Shaping Value Creation
Technological Innovation and Clinical Performance
Innovation in coronary stents is increasingly focused on polymer science, scaffold architecture, and deliverability in complex lesions. The emphasis has shifted from simply maintaining vessel patency to reducing long-term inflammatory responses, accelerating endothelial healing, and improving trackability through tortuous anatomy. Recent product milestones underscore this direction. In early 2025, Medtronic secured regulatory clearance for an upgraded Resolute Onyx drug-eluting stent featuring an improved polymer designed to accelerate endothelial healing and lower thrombosis risk. Shortly thereafter, Boston Scientific received FDA approval for the SYNERGY XD bioabsorbable polymer stent, positioned to reduce long-term inflammation and thrombosis risks. Abbott followed with the launch of the XIENCE Sierra Flex, a newer-generation platform engineered for complex lesions with enhanced flexibility, improved deliverability, and faster endothelial healing.
These developments signal a broader industry pivot: the next wave of value will accrue to platforms that combine favorable acute procedural performance with durable long-term safety. For manufacturers, the implication is clear—R&D must prioritize endpoints that matter to operators and payers, including deliverability in challenging anatomy, healing profiles, and compatibility with complex percutaneous coronary intervention techniques. For investors, this environment rewards companies with credible pipelines and demonstrated regulatory execution rather than those relying on incremental feature sets.
Cardiac Stent Market
Policy and Regulatory Environment
Regulatory pathways continue to shape the pace and cost of market entry. Coronary drug-eluting stents classified as Class III devices require premarket approval submissions to the FDA Office of Cardiovascular Devices, reinforcing the importance of robust clinical data packages and predictable approval timelines. The regulatory environment also interacts with reimbursement structures in ways that influence adoption. For example, percutaneous transcatheter placement of intracoronary drug-eluting stent(s), with or without other therapeutic intervention, any method; single vessel is assigned to APC 0656 under CMS classification. Meanwhile, a new complex PCI code introduced for 2026 provides notably higher RVU credits for procedures involving two or more distinct lesions or bifurcation treatment. These coding and coverage dynamics create economic incentives that can accelerate the use of advanced platforms in higher-complexity cases, provided the devices and procedural workflows align with the intended indications and documentation requirements.
For companies, regulatory predictability and reimbursement alignment are strategic assets. Early engagement with regulatory expectations, combined with clear understanding of how procedural codes affect site economics, can reduce time-to-market friction and support smoother adoption trajectories. Conversely, misalignment in either dimension can slow uptake regardless of clinical promise.
Demand-Side Shifts in Clinical Practice
Cardiology practice patterns are evolving toward risk-tailored interventions, increased attention to high-bleeding-risk populations, and broader adoption of techniques that address complex lesion sets. Clinical teams are increasingly evaluating devices not only for acute results but also for their contribution to long-term outcomes and procedural efficiency. This shift is reinforcing demand for platforms that support reliable deployment across a spectrum of anatomies and patient profiles, including de novo lesions and patients with elevated bleeding risk where stent selection and adjunct therapy must be carefully balanced.
Demand is also being influenced by the growing importance of procedural complexity as a driver of value. As coding frameworks increasingly recognize multi-lesion and bifurcation work, operators are incentivized to select tools that can manage these scenarios effectively. The commercial consequence is a market where flexibility, deliverability, and procedural control are becoming central purchasing considerations, especially in centers that handle higher-acuity case mixes.
Supply Chain and Cost Structure Dynamics
Cost structures in stent manufacturing remain sensitive to material availability, quality control requirements, and the economics of global distribution. Polymer-based and metal-based scaffolds each carry distinct sourcing and processing considerations, and disruptions in either channel can affect lead times and margin profiles. At the same time, procurement teams in health systems and group purchasing organizations are placing greater emphasis on total cost of ownership, including device performance, procedural efficiency, and downstream complication risk. This environment favors manufacturers that can deliver consistent quality, predictable availability, and demonstrable value in complex procedures, rather than competing solely on unit price.
Strategic management of supply chain resilience, combined with clear communication of value propositions tied to procedural outcomes, is becoming a differentiator. Companies that can balance cost discipline with clinical credibility are better positioned to navigate both tender processes and direct hospital negotiations.
Competitive Landscape and Leadership Strategies
The coronary stents market is characterized by significant concentration, with a handful of global leaders commanding the majority of share. This structure places a premium on differentiated platforms, disciplined commercial execution, and strategic clarity around target patient populations. Abbott, Boston Scientific, and Medtronic remain central to the competitive conversation, each advancing distinct value propositions and recent product milestones that reflect differing strategic focal points.
Abbott continues to emphasize newer-generation drug-eluting systems, exemplified by the March 2025 launch of the XIENCE Sierra Flex designed for complex lesions with enhanced flexibility and improved deliverability. The company's focus on deliverability and endothelial healing underscores an approach that connects acute procedural performance with longer-term outcomes. Boston Scientific has been advancing platforms for complex lesions and in-stent restenosis, including the February 2025 FDA approval of SYNERGY XD bioabsorbable polymer stent aimed at reducing long-term inflammation and thrombosis risks. This reflects a strategy oriented toward addressing residual risks associated with long-term polymer exposure and expanding applicability in challenging clinical scenarios. Medtronic's trajectory centers on durable performance in de novo lesions and high-bleeding-risk patients, highlighted by the January 2025 CE clearance of an upgraded Resolute Onyx platform with an improved polymer intended to speed endothelial healing and lower thrombosis risk. Together, these three players illustrate how leaders are competing on the intersection of polymer technology, procedural handling, and patient stratification.
Beyond the largest players, a competitive tier of specialists and regional champions is shaping the market from different angles. Terumo and Biotronik continue to advance bioresorbable polymer and sirolimus-eluting platforms, reinforcing interest in healing-oriented designs. MicroPort, with its drug-eluting portfolio, reflects the growing influence of regional manufacturing strength and expanding commercial footprints in Asia and beyond. Smaller innovators such as Elixir Medical and Hexacath are exploring bioadaptor and bio-active approaches, while Cook Medical's covered stent systems underscore the continued relevance of specialized applications. These players demonstrate that differentiation can emerge from novel scaffold concepts, niche clinical use cases, or regional distribution advantages, even within a concentrated market.
Market structure is evolving in two complementary directions. Consolidation pressures remain present as larger platforms seek to broaden indication coverage and streamline portfolios, while differentiation pressures create space for targeted entrants that can address specific clinical gaps or regional procurement dynamics. The likely trajectory is not a simple shakeout but a layered landscape: dominant platforms competing on broad clinical credibility and procedural versatility, alongside focused innovators pursuing distinct mechanisms or regional advantages. For companies operating in this environment, strategy must address both ends—protecting broad footprint value while identifying where a specialized proposition can command premium positioning.
Forward-Looking Trends and Commercial Implications
Trend 1: Polymer and Scaffold Design as the New Battleground
The most consequential differentiation in the near term will likely come from polymer chemistry, scaffold architecture, and the balance between durability and bioabsorbability. As platforms demonstrate improved endothelial healing and reduced long-term inflammatory exposure, clinical teams will increasingly weigh these attributes in device selection, particularly for patients where late complications carry disproportionate risk. Commercially, this trend rewards manufacturers with credible data packages and clear narratives around healing profiles, and it creates opportunities for partnerships and licensing in polymer science. The risk side lies in the possibility that head-to-head clinical evidence narrows perceived differences, shifting competition toward cost and availability unless performance advantages remain clinically meaningful.
Trend 2: Coding and Reimbursement as Adoption Accelerators
Procedural coding and coverage decisions are becoming more influential in shaping adoption patterns, especially where complexity-based incentives are introduced. New complex PCI coding frameworks that provide higher RVU credits for multi-lesion or bifurcation procedures can make advanced platforms more economically attractive in high-acuity settings. Manufacturers that align their indications, training, and documentation support with these coding realities can benefit from faster integration into complex case workflows. The uncertainty lies in the pace and consistency of payer responses across regions, and in the potential for future adjustments that alter the economic calculus. Companies should monitor reimbursement signals as closely as clinical data, because economics can accelerate or constrain uptake regardless of device performance.
Trend 3: Complexity-Led Growth and Regional Divergence
Growth in the coming years is expected to be shaped by procedural complexity, patient risk profiles, and regional differences in access, procurement, and clinical practice. Markets with expanding interventional capacity and increasing treatment of complex lesion sets are likely to drive demand for flexible, deliverable platforms. At the same time, regional procurement models and health system economics will continue to influence the pace of adoption for premium-priced devices. This divergence creates opportunities for companies to tailor value propositions by setting, focusing on deliverability and procedural efficiency where complexity is rising, while emphasizing total value and consistency where procurement is price-sensitive. The main risk is that regional variability can slow global portfolio scaling if value narratives are not adapted to local economic and clinical priorities.
Strategic Recommendations for Decision-Makers
Manufacturers should prioritize platforms that connect acute deliverability with durable safety profiles, while investing in evidence generation that speaks to operator priorities and reimbursement realities. Portfolio decisions should be guided by the ability to address complex lesions and higher-risk patient groups, supported by clear training and procedural support that helps sites capture the value of new coding incentives. Supply chain stability and consistent quality should be treated as commercial advantages, not just operational concerns, because availability and reliability increasingly influence purchasing decisions alongside clinical features.
Investors should evaluate pipelines against regulatory execution, reimbursement alignment, and the credibility of differentiation claims. The market appears most rewarding for companies that can demonstrate meaningful clinical or procedural advantages and navigate approval pathways efficiently. Portfolio risk should be assessed with attention to concentration dynamics, the durability of polymer-related innovation claims, and exposure to regional procurement variability. Companies with broad footprint value and credible complexity-focused platforms are better positioned to sustain share as coding and clinical practice evolve.
Stent Grafts Market
Procurement leaders and health system decision-makers should focus on total value rather than unit price alone, weighing device performance in complex cases, procedural efficiency, and downstream complication risk. Engaging clinical teams early to identify the features that most affect outcomes in local case mixes can improve formulary decisions and tender positioning. Monitoring reimbursement updates and coding changes is equally important, because these signals can reshape the economics of procedure selection and the relative attractiveness of different device categories.
The coronary stents market is entering a phase where clinical nuance, procedural economics, and supply discipline jointly determine competitive outcomes. The leaders who capture the next wave of growth will be those who translate innovation into measurable value at the point of care, align with reimbursement architecture, and maintain reliable execution across global demand cycles. For organizations seeking more granular segmentation data, regional procurement patterns, and tailored scenario analysis, the full PW Consulting report provides a deeper quantitative and strategic foundation, including detailed market sizing, segmentation breakdowns, and company-level competitive assessments designed to support planning and investment decisions.
For detailed analysis of this topic, please visit the official page: Coronary Stents Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


