



PW Consulting Video Intercom Devices Market: Why 12.4% CAGR Redefines Growth

Video Intercom Devices Market: Strategic Trends and Commercial Opportunities Through 2032
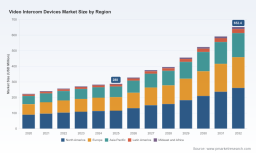
The video intercom devices market has evolved from a niche access control accessory to a critical node in the broader smart security and building automation ecosystem. Valued at approximately US$288 million in 2025, the sector has grown steadily from US$223.62 million in 2020, reflecting a compound annual growth rate of 12.45% over the 2020 to 2025 period. Forward projections indicate the market will expand to roughly US$652.4 million by 2032, driven by accelerating deployment in residential complexes, commercial facilities, and industrial sites that increasingly treat secure communication as a baseline operational requirement rather than a luxury upgrade. This trajectory signals a structural shift in how organizations approach entry points, visitor management, and remote connectivity.
At its core, the market is defined by a tension between legacy infrastructure and next-generation IP-based architectures. Wired systems still command the majority of revenue, but wireless and hybrid solutions are gaining share as installers and end users prioritize deployment flexibility, reduced cabling costs, and easier retrofits in older buildings. The customer base spans private homeowners, property managers, enterprise facilities, and institutional operators, each with distinct security thresholds, integration requirements, and budget cycles. In a moderately concentrated landscape, the leading three players hold roughly 40% of total revenue, while the top five account for about 50%, leaving meaningful headroom for specialized vendors, regional integrators, and technology-forward entrants that can differentiate through software, interoperability, and service models.
The strategic significance of these figures lies not in the absolute size of the market, but in what they reveal about adoption maturity. The double-digit growth pace indicates that video intercoms are crossing a threshold from fragmented, project-based sales to more standardized, multi-site rollouts. At the same time, the concentration pattern suggests that incumbents retain strong advantages in brand trust, installed base compatibility, and channel relationships. For decision-makers, this combination creates both opportunity and friction: growth is real and durable, but capturing it requires navigating a competitive field where hardware specifications alone no longer determine victory.
Vehicle Intercom System Market
Market Snapshot and Core Challenges
The market's current shape reflects a midpoint between early adoption and broader normalization. Revenue growth between 2020 and 2025 has been consistent, with notable acceleration implied by the forward forecast through 2032. This expansion is not merely a function of more units sold; it reflects a qualitative shift in what video intercom systems are expected to do. Modern deployments increasingly function as access gateways, communication hubs, and data touchpoints that connect building security with property management software, mobile applications, and remote monitoring workflows. As a result, the commercial value of the device itself is rising, but so are expectations around reliability, cybersecurity, and integration depth.
PW Consulting
Three challenges stand out as particularly consequential for the next planning cycle. First, the installed base of legacy intercoms remains large, especially in residential and institutional settings, and many organizations face a difficult decision between full replacement, hybrid retrofitting, and phased upgrades. This creates a complex demand pattern in which buyers evaluate not just features, but downtime risk, installation disruption, and long-term maintainability. Second, integration complexity is rising faster than the comfort level of many procurement teams. Video intercoms must increasingly interoperate with access control, CCTV, door locks, elevator dispatch, and cloud-based management platforms, which means that compatibility and API openness can matter as much as camera resolution or audio quality. Third, the market is encountering pressure from component supply dynamics and export controls that have heightened uncertainty around certain electronic materials and related subsystems. This does not halt growth, but it does change the cost and risk calculus for manufacturers, especially those depending on globally distributed supply chains with concentrated exposure to specific minerals and processing capacity.
These challenges are not isolated. The legacy infrastructure question influences upgrade timing; integration demands shape purchasing criteria; and supply constraints reshape pricing and product roadmaps. For executives evaluating this market, the practical implication is that success depends less on a single specification advantage and more on a coherent strategy that addresses installation practicality, system interoperability, and supply resilience at the same time.
Key Drivers and Recent Market Dynamics
Technology Innovation and Differentiation
The most visible driver of market momentum is the shift toward IP-based, cloud-connected video intercom platforms. Modern devices increasingly combine high-resolution imaging, bidirectional audio with noise handling, mobile app support, and remote management features that allow property managers and security teams to view, authenticate, and record interactions without being physically present. Recent product activity illustrates this trajectory. In October 2025, Siedle Access Release 7.5 introduced full video concierge functions through its app and added status display integration aimed at barrier-free communication, reflecting a broader push to reposition intercoms as communication platforms rather than simple door stations. Around the same period, other manufacturers have showcased touchscreen door stations with QR code entry, dual-door control, and Power over Ethernet support, pointing toward a market where convenience and access flexibility are becoming baseline differentiators.
Another layer of innovation is coming from the convergence of intercom technology with broader building communication standards. Products with ONVIF compatibility, SIP-based communication, and flexible audio processing are increasingly attractive in settings where video intercoms must coexist with surveillance cameras, enterprise telephony, and centralized management consoles. The recent delivery of a video intercom system for a community workshop project demonstrates how these devices are being used in mixed-use and semi-public environments where access control must be both secure and user-friendly. This trend matters because it expands the addressable use cases beyond traditional multi-family residential and into workplaces, collaborative spaces, and institutional facilities that value auditable access and remote authorization.
The strategic implication is clear: hardware is no longer the sole battleground. Organizations that can couple device reliability with usable software, remote diagnostics, and predictable upgrade paths are positioned to capture more value per installation and to reduce long-term support friction.
Video Intercom Devices and Equipment Market
Policy, Regulation, and Supply Chain Pressure
A second major driver is the regulatory and material environment, which has grown more complex in ways that directly affect product planning. Export controls on certain medium and heavy rare earth elements and related compounds have introduced supply concentration risk for components used in electronic devices, including those embedded in video intercom hardware. The situation escalated in October 2025 with measures extending license requirements to internationally made products containing Chinese-sourced rare earth materials or relying on Chinese technologies. A particularly notable element is the 0.1 percent threshold rule, which requires foreign companies to obtain a license for products made in China that contain any Chinese-origin rare earth materials. This level of granularity changes the compliance burden for manufacturers and assemblers, especially where traceability across components and subassemblies is incomplete.
These controls build on an earlier wave of material export restrictions. By December 2024, prohibitions on gallium, germanium, antimony, and superhard materials exports to the United States contributed to a steep drop in Chinese antimony exports and a sharp increase in global prices. The effects have rippled through the wider electronics supply chain, creating cost volatility and procurement caution. For the video intercom market, the key takeaway is not that production is becoming impossible, but that sourcing strategies, bill-of-materials design, and regional manufacturing footprints now carry more strategic weight than they did a few years ago. Companies with diversified supplier bases, clearer material traceability, and buffer inventory strategies are better positioned to manage pricing shocks and compliance complexity.
This environment is also reshaping negotiation dynamics between OEMs and their suppliers, as well as between manufacturers and channel partners. Cost structures are less predictable, and lead times can be more sensitive to regulatory developments. In that context, a product roadmap that assumes stable input costs or seamless cross-border sourcing can become a liability. The market is rewarding organizations that treat supply chain resilience as a design parameter rather than a back-office concern.
Demand-Side Shifts and Operating Model Changes
Demand is being reshaped by changing expectations around security, convenience, and remote management. In residential contexts, property managers and developers increasingly see video intercoms as part of a broader value proposition that includes visitor verification, delivery handling, and resident communication. In commercial settings, facilities are looking for devices that reduce front-desk bottlenecks, support after-hours access protocols, and integrate with existing security operations centers. Industrial and institutional users are prioritizing ruggedness, clear audio, and compatibility with access control regimes that must satisfy both security and operational continuity requirements. Across these segments, there is a common thread: the device must be easy to use for visitors and residents, and easy to manage for operators.
This demand shift is also altering purchasing behavior. Buyers are paying more attention to total cost of ownership, including installation effort, software licensing, maintenance contracts, and the likelihood of future upgrades. As a result, vendors that bundle hardware with clearer deployment models, remote configuration, and ongoing support are gaining an advantage in evaluations where multiple solutions appear technically comparable. The commercial opportunity lies in aligning product design with these operational priorities, rather than selling devices as standalone specifications.
Competitive Landscape and Leading Strategies
The competitive field combines established multinational players with specialized manufacturers and regional integrators. Aiphone Corporation, based in Japan, emphasizes scalable video intercom and access control solutions across multiple series for commercial real estate, offices, healthcare, education, and multi-tenant buildings, with cloud integration available through its platform. Panasonic Corporation offers highly expandable video intercom systems with wireless options and multi-room monitoring for residential and commercial applications, appealing to customers who value familiarity, expansion capability, and integrated home or building ecosystems. Dahua Technology provides IP, Wi-Fi, and analog video intercoms with CCTV integration and mobile app support, a combination that resonates in housing, small apartment, and larger residential community settings where surveillance linkage is a priority. Honeywell International offers LCD touch-screen IP video door phones and integrated access control systems that fit commercial and residential security applications, leveraging its broader building technologies reputation.
In Europe, several manufacturers demonstrate strong positioning around architecture, building communication quality, and cloud-enabled management. Siedle & Sohne OHG from Germany manufactures IP-based video intercom systems with app-enabled concierge functions and cloud integration, and has been active in expanding digital building management features. Comelit Group S.p.A. from Italy supplies scalable video door entry and building access control systems aimed at property managers, while Legrand Holding Inc. from France provides home and commercial intercom systems covering broadcast and selective call video and voice solutions. Zenitel Group from Norway focuses on IP and SIP video intercom devices with automatic noise cancellation and ONVIF compatibility, particularly relevant in critical communication applications where clarity and interoperability matter. 2N TELEKOMUNIKACE from the Czech Republic develops robust video intercoms with high-resolution cameras, QR code access, and advanced noise cancellation, and TCS AG from Germany specializes in video door intercoms and building communication systems for functional and public buildings.
The differentiation among these players is rarely about a single feature. Instead, the market is sorting along several strategic lines. Some vendors compete on brand trust and installed base compatibility, relying on long-standing relationships with integrators, electricians, and property managers. Others compete on software depth, emphasizing mobile apps, remote management, concierge functions, and integration with cloud building platforms. Still others compete on interoperability and standards alignment, particularly in settings where video intercoms must work alongside existing cameras, access control hardware, and security operations tools. A further group competes on deployment practicality, including wireless options, touchscreen interfaces, QR-based entry, and PoE support that can simplify installation and reduce retrofit costs.
The recent developments in the market reinforce these strategic directions. Siedle's October 2025 release focused on video concierge capability and barrier-free communication, while its January 2026 launch emphasized a touch door station for large residential complexes and cloud-based digital building management. Mircom's October 2025 unveiling of a 10-inch touchscreen video intercom with QR entry, PoE, and dual door control reflects the growing appeal of larger displays, flexible access methods, and simplified wiring. These announcements point toward a market in which product launches are increasingly tied to workflows, not just hardware capabilities.
Looking forward, competitive dynamics are likely to evolve through both consolidation and fragmentation. Consolidation may occur where large building technology players see advantages in folding video intercoms into broader portfolios, especially when customers prefer fewer vendors and integrated service relationships. Fragmentation may persist where regional integrators, niche manufacturers, and software-centric entrants carve out positions by serving specific building types, compliance needs, or deployment constraints. The most vulnerable competitors are likely to be those that depend on hardware commoditization without offering meaningful differentiation in integration, support, or user experience. The most resilient competitors will treat video intercoms as part of a larger service and software value proposition, with device quality as one element of a broader system.
Future Trends and Strategic Implications
Trend One: From Devices to Connected Access Platforms
Over the next three to five years, video intercoms are likely to be judged less as isolated door stations and more as components of connected access platforms. This means growth will increasingly favor solutions that combine reliable hardware with software layers for remote verification, visitor management, audit logs, and integration with property or facility management tools. The business opportunity here is not simply higher device prices; it is the expansion of recurring and service-related value tied to management, upgrades, and compatibility. Organizations that build these capabilities early can create switching costs through workflow integration, while those that remain focused on hardware-only value may face margin and differentiation pressure.
Trend Two: Supply Strategy as a Competitive Advantage
The second trend is that supply chain resilience will move from operational concern to strategic differentiator. With ongoing export controls and material restrictions raising the cost and complexity of certain electronic components, companies that invest in traceability, diversified sourcing, and cautious product design will be better positioned to maintain pricing stability and delivery predictability. This trend creates an opportunity for manufacturers and channel partners to market reliability as part of the value proposition, especially in large multi-site deployments where downtime or delayed rollout carries real operational consequences. It also creates a risk for over-centralized supply strategies that appear efficient in the short term but expose the business to regulatory and cost shocks.
Trend Three: Wider Use Cases and Integration-Led Purchasing
The third trend is the widening of use cases beyond traditional residential and commercial entry points. Community workshops, mixed-use buildings, and institutional facilities are adopting video intercoms where access needs to be both secure and visitor-friendly. As these deployments grow, purchasing decisions are likely to become more integration-led, with success measured by how well the solution fits into existing cameras, access control systems, and management software. This trend favors vendors and integrators that can demonstrate compatibility, clear deployment models, and practical support for multi-stakeholder environments. It also introduces a risk: organizations that overpromise interoperability without robust testing and ongoing compatibility management may face post-deployment friction that erodes trust.
Together, these trends suggest a market where growth is durable but increasingly selective. Buyers will continue to invest, but they will expect more evidence of usability, integration, supply reliability, and long-term manageability. The opportunity lies in aligning product and service design with those expectations, rather than assuming that market growth automatically translates into easy commercial gains.
Actionable Guidance for Decision-Makers
For Manufacturers and Product Leaders
- Treat software, interoperability, and remote management as core product components rather than afterthoughts. The most defensible positions will come from combining reliable hardware with usable workflows, clear integration paths, and predictable upgrade options.
- Design supply strategies with material and regulatory risk in mind. Diversify sourcing where possible, strengthen traceability for affected components, and evaluate regional or alternative manufacturing pathways to reduce exposure to export control uncertainty.
- Align product roadmaps with the practical needs of installers and operators. Touchscreen interfaces, QR entry, PoE support, and flexible communication options can reduce installation friction and increase adoption in retrofit-heavy environments.
For Investors and Corporate Strategists
- Focus on business models that extend value beyond the device sale. Recurring service, software-enabled management, and integration support can create more durable revenue streams in a market where hardware differentiation is increasingly crowded.
- Assess supply chain exposure as part of investment diligence. Companies with concentrated dependence on constrained materials or opaque sourcing may face pricing and delivery volatility that affects margins and deployment timelines.
- Watch for consolidation opportunities where building technology portfolios can absorb video intercoms into broader security, access, and automation offerings, especially if end users prefer fewer vendor relationships and integrated support.
For Procurement and Facilities Decision-Makers
- Evaluate total cost of ownership with installation, integration, training, and support in mind. A lower upfront device cost can be offset by difficult retrofitting, limited interoperability, or weaker remote management capabilities.
- Prioritize compatibility with existing security, camera, and building management systems. Where multi-site rollout is planned, ask for clear evidence of integration, maintainability, and upgrade paths before committing to a standard platform.
- Build resilience into procurement planning. Given supply and regulatory volatility, consider sourcing strategies, lead-time buffers, and vendor support commitments as part of the purchasing decision rather than as secondary concerns.
The video intercom devices market is moving into a phase where growth is supported by structural demand, but commercial success will depend on how well organizations navigate integration, supply risk, and user-facing value. For leaders who need a more detailed view of segment dynamics, regional patterns, and competitive positioning, the full PW Consulting research report provides the deeper segmentation data and tailored recommendations needed to translate these trends into concrete strategy.
For detailed analysis of this topic, please visit the official page: Video Intercom Devices Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


