



Durable Juvenile Products Market: 7.4% CAGR, 2026–2032 Growth Drivers

The Durable Juvenile Products Market: Strategic Trends and Commercial Opportunities Through 2032
The durable juvenile products market has entered a phase of disciplined expansion, shaped by evolving safety expectations, material innovation, and shifting family consumption patterns. Valued at approximately USD 12.22 billion in 2025, the sector has grown steadily from USD 8.55 billion in 2020, reflecting a compound annual growth rate of 7.4 percent through 2032. By the end of the forecast window, revenue is projected to approach USD 20.14 billion, signaling sustained demand rather than a temporary cycle. This trajectory is not uniform across categories or geographies, and the underlying dynamics warrant careful strategic attention for executives planning product portfolios, capital allocation, and market entry.
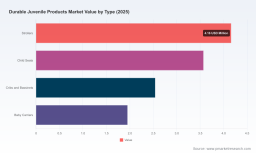
The growth story is anchored in the structural reality that durable juvenile products—strollers, child seats, cribs and bassinets, and baby carriers—represent long-lifecycle purchases where safety, ergonomics, and durability command premium positioning. While the overall market expands, the composition of growth is shifting toward integrated solutions that combine travel systems, convertible safety seats, and multi-functional furniture. At the same time, the industry is navigating cost pressures, regulatory recalibration, and a competitive landscape that rewards differentiation in safety credentials and sustainability. Understanding these forces is essential for players seeking to convert market expansion into durable competitive advantage.
Market Landscape and Core Challenges
The market’s scale and momentum are clear, but several structural challenges define the current inflection point. First, consumer expectations around safety and transparency have intensified, elevating verification and certification from compliance tasks to brand differentiators. Second, input cost volatility and supply chain complexity continue to pressure margins, particularly for manufacturers balancing material upgrades with affordable price points. Third, the sector is experiencing a convergence of product categories and usage scenarios, as families increasingly seek modular, multi-stage solutions that reduce the total cost of ownership across infancy and early childhood. These challenges are not deterrents; they are reshaping competitive requirements and rewarding companies that can integrate safety, design, and operational efficiency.
Concentration patterns indicate a moderately fragmented landscape, with the top three players holding roughly 28 percent of revenue and the top five capturing approximately 35 percent. This dispersion suggests room for specialist positioning, regional strength, and category leadership, while also highlighting the relevance of scale advantages in compliance, distribution, and brand investment. The competitive environment is therefore best understood as a mosaic of global platforms, regional champions, and design-led specialists, each leveraging distinct strengths in safety, ergonomics, and brand equity.
Key Demand Drivers
Technological Innovation and Product Architecture
Innovation is moving beyond incremental feature additions toward integrated product architectures that adapt across stages of child development. Convertible car seats, all-in-one travel systems, and modular stroller platforms are gaining traction because they extend product lifecycles and reduce the need for multiple purchases. Advances in ergonomic design, weight reduction, and ease-of-use mechanisms are becoming decisive purchase criteria, especially as urban mobility patterns and multi-child family dynamics influence demand. Recent product recognition in the category underscores how engineered convenience, when paired with safety, can translate into market advantage. For example, industry accolades awarded to integrated stroller and car seat solutions highlight the commercial appeal of streamlined, multi-function products that address real-world usage pain points.
Regulatory and Safety Standards as Competitive Levers
Regulatory oversight and voluntary verification programs are increasingly shaping purchase decisions and market access. Federal safety standards govern a broad range of durable juvenile products, including strollers, child seats, and high chairs, creating a baseline that all players must meet. Beyond compliance, verification ecosystems are expanding in scope and visibility. The industry’s lead trade body formally rebranded to the Baby Safety Alliance to sharpen its focus on safety and quality, while extending certification to additional categories such as nursing pillows and child restraint systems. Its verification program now evaluates thousands of products across more than 30 categories using recognized standards, reinforcing the role of independent testing as a trust signal for consumers and retailers.
Policy dynamics are also influencing market behavior. Advocacy efforts have sought tariff exemptions for lifesaving baby and children’s safety products, reflecting concerns that trade measures could raise costs and disrupt supply for essential categories. In parallel, fiscal policy changes in select jurisdictions have removed sales tax on a wide range of durable juvenile products, improving affordability and potentially stimulating demand. These regulatory and fiscal signals illustrate how safety, access, and cost interact to shape market outcomes, and they reward companies that proactively align product portfolios with evolving compliance and consumer trust expectations.
Shifts in Consumer and Retail Behavior
Demand-side behavior is increasingly driven by total value rather than sticker price. Families are prioritizing products that combine safety assurance, ergonomic comfort, and longevity, while retailers and e-commerce channels amplify the importance of demonstrable quality and reviewable performance. The rise of travel-friendly designs, breathable materials, and easy-clean surfaces reflects practical usage needs that resonate across urban and suburban markets. In addition, brand ecosystems that connect car seats, strollers, and accessories into coherent systems are gaining preference because they simplify purchasing decisions and enhance user experience. Consumer willingness to invest in verified safety and durable construction supports premium tiers within the category, particularly where brands can communicate testing, materials, and design intent transparently.
Juvenile Life Insurance Market
Supply Chain and Materials Transition
Material choice is becoming a strategic variable rather than a purely technical one. The shift toward recycled polyester and naturally flame-retardant fabrics illustrates how sustainability and performance can be integrated without compromising safety or durability. Manufacturers that adopt recycled content and low-impact materials are aligning with retailer expectations, consumer sentiment, and regulatory trajectories, while also managing long-term input risk. At the same time, the sector continues to manage cost structures amid fluctuating raw material prices and logistics complexity. Companies that diversify sourcing, optimize product architecture for manufacturability, and invest in quality control are better positioned to protect margins while meeting elevated safety and sustainability expectations.
Competitive Landscape and Leading Strategies
The competitive field is defined by a mix of global platforms, regionally anchored brands, and design-focused specialists. Several companies stand out for the way they translate safety, durability, and brand positioning into distinct market strategies.
Baby Stroller and Pram Market
Artsana S.p.A. leverages the Chicco brand to emphasize safety, durability, and sustainability across strollers, car seats, highchairs, and related products. Its sustainability commitments, including the adoption of recycled materials in apparel and ancillary lines, signal an integrated approach to brand trust and material innovation. Newell Brands Inc. operates a broad portfolio through Graco, Baby Jogger, and Aprica, spanning car seats, strollers, highchairs, and playards. Its strength lies in scale, multi-brand architecture, and the ability to cover multiple price points and use cases, a strategy reinforced by recent industry recognition for integrated travel and safety products. Goodbaby International Holdings Limited maintains a global footprint with brands such as Evenflo, covering strollers, car seats, cribs, and bicycles, positioning the company to capture demand across categories and regions with a strong emphasis on accessible safety solutions.
Dorel Juvenile Group and Britax Child Safety Inc. illustrate complementary approaches within safety-centric segments. Dorel focuses on car seats, strollers, and play yards, while Britax emphasizes child safety seats and related durable products, recently extending its all-in-one car seat line with colorways and fabrics derived from naturally flame-retardant recycled materials. These moves highlight how safety credentials and material innovation can be combined to refresh portfolios and reinforce brand promise. Stokke AS and BabyBjörn AB represent design-led positioning, with Stokke specializing in durable strollers, high chairs, and children’s furniture, and BabyBjörn focusing on ergonomic strollers, high chairs, and carriers. Their strategies demonstrate that ergonomics and longevity can support premium positioning in mature markets.
Italian and European specialists such as Peg Perego S.p.A. and Inglesina S.p.A. continue to compete on strollers, car seats, and high chairs, often emphasizing craftsmanship, integration, and travel functionality. In Asia, Combi Corporation provides car seats, strollers, and child restraints with a focus on restraint quality and usability, while Ergobaby Inc. and BabyFirst LLC contribute specialized offerings in ergonomic carriers and car seats respectively. Recaro GmbH & Co. KG and BeSafe Group AG extend the safety-centric cohort with advanced restraint systems and child safety products, reinforcing the role of technical credibility in specific subcategories.
The landscape is evolving along two parallel tracks. Consolidation continues among scaled players seeking portfolio breadth, distribution efficiency, and compliance leverage, while differentiation persists among specialists competing on ergonomic excellence, material leadership, and safety verification. New entrants and brand extensions are most likely to succeed where they address unmet usage scenarios, such as travel-optimized systems, convertible products that span multiple stages, or verified safety narratives that resonate with cautious buyers. In this environment, competitive advantage increasingly depends on the ability to integrate product engineering, certification visibility, and supply chain resilience rather than on price alone.
Forward Outlook: Trends Shaping the Next Three to Five Years
Several trends are likely to define the market over the next three to five years, each carrying distinct commercial implications.
- Integrated, multi-stage product systems will capture a growing share of demand. Families are looking to reduce complexity and total cost by purchasing products that adapt across ages and use cases. Convertible car seats, modular strollers, and coordinated travel systems are well positioned to benefit, provided they deliver measurable convenience and safety without compromising durability.
- Safety verification and transparent materials will become baseline expectations. As verification programs broaden and consumer scrutiny intensifies, brands that can demonstrate testing rigor, material provenance, and compliant design will gain trust and retail preference. Sustainability attributes, including recycled fabrics and flame-retardant alternatives, are likely to move from differentiators to standard features in premium segments.
- Regional policy and fiscal environments will shape demand patterns. Tax adjustments, trade measures, and safety advocacy will influence affordability and supply economics in specific markets. Companies that monitor policy signals and maintain flexible sourcing and pricing strategies will be better equipped to navigate localized demand shifts and cost changes.
These trends point to commercial opportunities in portfolio simplification, certification-led brand building, and material innovation that aligns with both safety and sustainability goals. At the same time, uncertainty remains. Input cost volatility, potential trade policy changes, and the risk of safety incidents that can erode consumer confidence require disciplined quality management and scenario planning. Brands that over-index on features without reinforcing safety credibility or manufacturability may find it difficult to sustain premium positioning. Conversely, firms that balance integrated design, verifiable safety, and resilient supply chains are likely to convert market growth into share gains.
Strategic Actions for Decision Makers
Manufacturers should prioritize product architectures that extend lifecycle value while reinforcing safety and material transparency. Investing in convertible designs, travel-friendly mechanics, and verifiable testing narratives can strengthen both consumer trust and retail relationships. Sourcing strategies should balance cost control with material upgrades, particularly where recycled or naturally flame-retardant inputs can support sustainability claims without compromising performance. Portfolio decisions should favor systems that connect categories—such as car seats, strollers, and accessories—so that brand equity and user experience compound over time.
Investors should assess category exposure through the lens of safety-driven demand and integration trends. Companies with strong verification alignment, recognizable safety brands, and the ability to offer multi-stage solutions are better positioned to defend margins and grow share. Due diligence should consider regulatory exposure, certification breadth, and supply chain resilience, as these factors increasingly influence competitive outcomes. Portfolio diversification across price tiers and geographies can also mitigate concentration risk while capturing demand where affordability measures and urbanization patterns support expansion.
Purchasers and retail partners should emphasize clear safety communication, demonstrable quality, and product simplicity in category planning. Shelving and merchandising strategies that highlight verification, ergonomic benefits, and integrated systems can improve conversion among cautious buyers. Collaborating with suppliers on consistent material standards and transparent testing information can reduce returns, strengthen brand trust, and support premium positioning in key subcategories.
PW Consulting
For decision makers seeking deeper segmentation, regional breakdowns, and customized scenario analysis, the full PW Consulting report on the durable juvenile products market provides detailed data and tailored recommendations to support portfolio, investment, and procurement decisions.
For detailed analysis of this topic, please visit the official page: Durable Juvenile Products Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


