



Cling Film Market: Why 5.2% CAGR and Food Packaging Demand Are Reshaping Growth by 2032

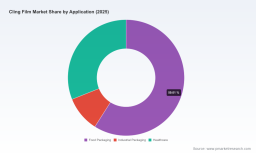
The Cling Film Market at a Crossroads: Navigating Structural Shifts and Strategic Opportunities (2026–2032)
The cling film market has evolved from a commoditized household staple into a strategically nuanced segment intersecting food safety, industrial efficiency, and sustainability mandates. Spanning a total revenue footprint of approximately $1.84 billion in 2025 and projected to reach $2.61 billion by 2032 at a 5.2 percent compound annual growth rate, the segment reflects steady expansion rather than explosive growth. This trajectory signals maturity punctuated by selective acceleration in high-value applications and geographies. Market participants who understand the underlying shift from volume-driven consumption to performance and compliance-led differentiation will be better positioned to capture margin and share over the next cycle.
Historically, the market expanded through casual adoption in home kitchens and basic food service environments. That dynamic is changing. Regulatory attention on single-use plastics, consumer sensitivity to material safety, and procurement teams’ focus on total cost of ownership are recalibrating demand. Growth is increasingly concentrated where cling film delivers measurable functional benefits such as extended shelf life, tamper evidence, hygiene assurance, and process efficiency. The persistence of a modest CAGR alongside a rising absolute market size indicates a market that is not shrinking but restructuring: slower volume expansion in mature channels, faster value creation in specialized uses, and a widening gap between commoditized offerings and differentiated products.
For decision makers, the immediate implication is that headline growth will not translate into uniform profitability. Success will depend on aligning product portfolios with the channels and applications that reward performance, navigating regulatory pathways without sacrificing usability, and building supply chain resilience in a market where raw material fluctuations and compliance costs can quickly erode thin margins. The following analysis examines the structural challenges, driving forces, competitive dynamics, forward-looking trends, and practical actions that shape the cling film landscape through 2032.
Market Landscape and Core Challenges
The market’s current configuration reflects a delicate balance between enduring utility and mounting external pressures. On the demand side, cling film continues to serve as a low-friction solution for wrapping, sealing, and displaying products across food service, retail, industrial, and healthcare environments. On the supply side, manufacturers operate in a fragmented competitive environment where no single group of firms controls a dominant share of global revenue, and where regional demand patterns differ substantially in scale and maturity. This fragmentation gives room for focused players to build defensible positions through specialization, while also creating opportunities for consolidation among those seeking scale, distribution leverage, or brand equity.
Regulatory and Consumer Pressure on Material Choices
One of the most consequential challenges is the shifting perception and regulation of conventional cling materials. Food safety expectations, environmental scrutiny, and downstream commitments from retailers and foodservice operators are pushing buyers to reconsider material selection, thickness, recyclability, and end-of-life pathways. In practice, this creates a compliance-and-preference tension: users value cling film for its convenience, seal integrity, and cost-effectiveness, yet they are increasingly asked to justify material choices in sustainability reporting or procurement evaluations. Manufacturers that can maintain functional performance while improving material profiles stand to gain trust and specification share; those that cannot articulate a credible transition path risk gradual displacement in sensitive categories.
Performance, Waste, and Total Cost of Ownership
A second challenge lies in the trade-off between film performance and material use. Over-engineering increases cost and environmental footprint, while under-engineering leads to tears, poor seals, contamination risk, and operational waste. Buyers are increasingly attentive to total cost of ownership rather than per-roll price alone. This includes considerations such as dispensing efficiency, ease of cutting, adhesion consistency, freezer compatibility, and the labor impact of film failure in professional kitchens or processing lines. In healthcare and food manufacturing contexts, these factors have direct consequences for safety, throughput, and compliance, making performance differentiation a meaningful source of value beyond commodity pricing.
Concentration, Channel Fragmentation, and Pricing Pressure
A third challenge is the uneven structure of demand and distribution. The market serves a broad mix of consumer retail, professional foodservice, institutional procurement, and industrial or healthcare applications, each with different purchasing rhythms, specification requirements, and competitive intensity. In channels where substitution is easy and brand loyalty is weak, price competition can compress margins quickly. In channels where performance, certification, or consistency matter more, there is room for premium positioning and longer-term supplier relationships. Companies that cannot distinguish between these environments may find themselves competing in the wrong dimension, defending price in segments where value should be the battleground.
Key Drivers Reshaping Demand and Supply
The market’s trajectory is being shaped by several interlocking forces that go beyond simple volume expansion. Understanding these drivers is essential because they determine where growth is likely to be most durable and where differentiation will command premium positioning.
Material Innovation and Functional Performance
Advances in polymer formulation, film structure, and adhesive cling characteristics are enabling products that perform better with less material and with greater consistency across temperature ranges and surface types. Stronger cling, improved tear resistance, sharper cut precision, and better freezer behavior are becoming relevant differentiators, particularly in professional and institutional channels where downtime, waste, and safety carry real costs. Innovation is also extending to user interface features such as integrated cutters and dispenser compatibility, which reduce handling friction and improve consistency in high-use environments. For manufacturers, the strategic question is whether innovation is aimed primarily at cost reduction or at measurable performance gains that procurement teams can feel and quantify.
Regulatory Environment and Sustainability Expectations
Policy and stakeholder expectations continue to influence material choices, packaging design, and reporting obligations. Even where direct bans are not in place, procurement standards, retail commitments, and corporate sustainability goals are shifting the conversation toward material efficiency, recyclability pathways, and transparency. This does not mean all conventional films are being replaced overnight; rather, it means that specification decisions are increasingly evaluated in a broader context that includes function, safety, waste, and downstream accountability. Companies that approach this as a design and communication challenge—producing films that meet actual performance needs while clearly articulating their material and handling profiles—are more likely to retain specifications during transitions than those that rely on generic claims.
Machine Stretch Film Market
Demand-Side Shifts in Foodservice, Retail, and Healthcare
Consumer and enterprise behavior is reshaping where cling film adds the most value. Foodservice and catering operations prioritize consistency, speed, hygiene, and portion control, making reliable wrap performance and dispensing convenience important operational inputs. Retail and food processing channels look for shelf-ready presentation, protection against contamination, and supply chain efficiency. Healthcare environments require materials and handling properties aligned with safety, cleanliness, and process control. Across these settings, the common thread is that cling film is not just a wrapper but a functional component of broader quality, safety, and efficiency systems. That perspective supports steady demand for products that demonstrably reduce failure rates, waste, or handling complexity.
Supply Chain Dynamics and Cost Structure
Raw material availability, energy costs, logistics, and production scale all influence the economics of cling film. In a market where many products compete on convenience and price, cost fluctuations can pressure margins quickly, particularly for undifferentiated offerings. At the same time, regional manufacturing and distribution footprints matter because they affect responsiveness, lead times, and the ability to serve local specifications efficiently. Companies that invest in stable sourcing, efficient conversion, and channel-aligned packaging formats are better positioned to manage volatility than those that depend on thin differentiation and reactive pricing. In practice, resilience is becoming part of the value proposition: reliable supply and consistent quality can be as important as the film itself, especially for professional and institutional buyers.
Competitive Landscape and Leading Strategies
The competitive environment combines well-known consumer brands, professional-grade suppliers, and regional manufacturers with specialized strengths. No single cluster of firms dominates the market, and the result is a landscape where multiple routes to advantage are available: brand recognition in consumer channels, performance credibility in foodservice and institutional settings, and niche engineering or distribution advantages in specific regions or applications.
Differentiation Through Grade, Application, and Channel Fit
Several established players have built positions by aligning product grades with specific use cases. Brands associated with consumer kitchens emphasize ease of use, familiar design, and reliable everyday sealing. Professional and foodservice-oriented suppliers tend to emphasize strength, cling consistency, cutterbox convenience, and performance under demanding conditions such as frequent handling, refrigeration, or freezing. In healthcare and institutional contexts, trust in consistency, safety, and specification fit can be more important than promotional visibility. The most effective competitors do not simply compete as cling film suppliers; they compete as solution providers for particular workflows, whether that means a busy commercial kitchen, a retail deli operation, or a processor’s line requirements.
PW Consulting
Brand Positioning and Functional Credibility
In a market where performance claims must survive daily use, credibility matters. Trademarks, product naming, and consistent communication around strength, clarity, seal integrity, and dispenser compatibility help buyers identify grades suited to their environment. For consumer-facing brands, accessibility and kitchen familiarity are central. For professional-facing brands, the emphasis shifts to repeatability, high-strength performance, and reduced handling errors. This dual structure creates room for parallel strategies: one route builds mass appeal and shelf visibility, another builds specification loyalty and channel relationships. The firms that manage both routes clearly tend to avoid diluting their message and instead tailor grade architecture to the right audience.
Consolidation, Specialization, and the Openings for New Entrants
Because the market is not highly concentrated, there is structural space for both consolidation and specialization. Larger players may pursue scale advantages, broader regional reach, or complementary portfolios that cover consumer and professional grades. Smaller and mid-sized manufacturers may pursue targeted leadership in freezer-grade films, specialty dispensers, catering-focused formats, or regional distribution strength. New entrants typically succeed when they solve a concrete friction point—such as cutterbox ergonomics, rewrapping consistency, freezer performance, or sustainable material transitions—rather than entering with a generic commodity offer. The likely trajectory over the forecast period is continued coexistence of broad consumer brands, professional specialists, and regional niche leaders, with selective moves to consolidate distribution or acquire specialized grades where capabilities complement one another.
Strategic Outlook: Key Trends Through 2032
Looking ahead, several trends are likely to define where value is created and where risk concentrates. These are not speculative outliers; they follow logically from the interplay of performance demand, regulatory posture, and procurement behavior already visible in the market.
Performance-Led and Material-Efficient Products Will Outperform Purely Commodity Offers
Over the next three to five years, buyer attention will increasingly favor films that deliver measurable functional benefits with efficient material use. This includes stronger cling, better cut control, improved freezer behavior, and formats that reduce waste during handling. Commercial kitchens, foodservice operators, retailers, and healthcare procurers are likely to favor grades that reduce failure rates and handling time. The commercial opportunity here is not only in premium pricing but in specification retention: when a film reduces operational friction, it becomes harder to replace on price alone.
Cellophane Market
Sustainability Will Become a Specification Factor, Not a Side Note
Sustainability considerations will continue to move from peripheral marketing to practical specification criteria. This does not necessarily mean an immediate shift away from all conventional films; it means that material choice, thickness efficiency, recyclability or recovery options, and documentation will increasingly matter in procurement evaluations. Companies that can present a coherent material narrative—grounded in real performance and transparent handling characteristics—will have an advantage in channels where downstream stakeholders ask harder questions. The risk is complacency: products that are functionally adequate but silent on material transition or efficiency may lose ground in specification reviews even if they remain acceptable in day-to-day use.
Professional and Institutional Channels Will Drive Higher-Value Growth
While consumer retail will remain important, a disproportionate share of value creation is likely to come from professional foodservice, retail back-of-house operations, food processing, and healthcare environments. These channels reward consistency, safety, efficiency, and total cost of ownership. They also tend to buy in ways that are less impulsive and more specification-driven, which favors suppliers that can demonstrate fit and reliability over time. The opportunity for manufacturers and distributors is to build channel-specific grade architectures and support tools that make adoption straightforward, rather than treating professional buyers as an afterthought to consumer branding.
Regional Divergence and Supply Chain Localization Will Shape Accessibility
Demand growth, regulatory cadence, and procurement norms will continue to vary by region. In higher-volume and faster-growing regions, accessibility, distribution reach, and format appropriateness will matter as much as product performance. In more mature markets, differentiation, compliance readiness, and professional-grade credibility will be more important than broad volume expansion. Companies that align production, distribution, and specification strategies to regional realities are more likely to convert demand into durable share than those pursuing a one-size strategy across all geographies.
Actionable Recommendations for Decision Makers
The strategic implications differ by role, but all participants should treat cling film as a functional component of broader operational, compliance, and brand systems rather than as a standalone commodity.
For Manufacturers and Brand Owners
- Develop grade architectures that explicitly match consumer, foodservice, institutional, and healthcare needs instead of forcing one product story across all channels.
- Invest in performance features that reduce operational friction, such as consistent cling, reliable cutting, freezer compatibility, and dispenser-friendly formats, because these translate into specification loyalty.
- Build a credible material and compliance narrative that balances function with evolving stakeholder expectations, focusing on transparency and real efficiency gains rather than vague sustainability language.
- Use regional distribution and format localization to improve responsiveness and reduce the cost of serving distinct procurement norms.
For Investors and Corporate Development Teams
- Look for companies with clear channel specialization, defensible performance differentials, and the ability to convert everyday usability into repeat specification in professional settings.
- Evaluate exposure to channels where total cost of ownership and safety matter more than price, since those segments typically support more resilient economics.
- Monitor consolidation potential around distribution strength, complementary grade portfolios, and regional capabilities, while remaining cautious about commoditized businesses vulnerable to price cycles.
- Consider sustainability as a strategic filter: the most durable opportunities are likely where material transition is tied to actual performance and procurement relevance.
For Procurement Teams and Buyers
- Evaluate cling film on total operational impact—seal reliability, tear resistance, freezer behavior, cutting convenience, and waste generated during use—rather than only on unit price.
- Align grade selection with application requirements, distinguishing everyday consumer use from high-frequency professional or healthcare contexts where consistency and safety carry more weight.
- Request clear product information on material characteristics and handling performance to support internal compliance, sustainability reporting, and specification decisions.
- Structure supplier relationships around consistency and issue resolution, because reliable performance in high-use environments can outweigh marginal cost differences.
The market’s medium-term direction is clear enough to warrant deliberate positioning, but the details that determine winning moves are highly segment-specific. Which grades are gaining specification share in professional foodservice, how procurement teams are weighting performance against material considerations in healthcare, and where regional demand is generating the most resilient growth all require closer scrutiny than top-line figures can provide. Decision makers who need segment-level demand patterns, application-grade dynamics, regional growth drivers, and competitive positioning detail will benefit from a more granular review of the full market dataset and scenario-based guidance. For those preparing investment theses, portfolio adjustments, or sourcing strategies, deeper segmentation intelligence can help convert the market’s broad momentum into focused, executable decisions.
For detailed analysis of this topic, please visit the official page: Cling Film Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Tags



PW Consulting
The Best-reviewed Subdivided Market Risk Analysis Firm in the US and East Asia.


